Generated by All in One SEO Pro v5.0.1.1, this is an llms-full.txt file, used by LLMs to index the site.
# Abe Student Loans: No Fees, No Credit Impact, Easy Application
Abe simplifies private student loans with clear, straightforward info and flexible terms, reducing confusion and stress for a better borrowing experience.
## Posts
### [What the Loss of “Professional Degree” Status Means to Graduate Nursing Programs](https://www.abestudentloans.com/blog/federal-loans/what-the-loss-of-professional-degree-status-means-to-graduate-nursing-programs/)
**Published:** December 9, 2025
**Author:** Abe
**Excerpt:**
Update: A June 2026 court order restored professional degree status to graduate nursing programs while the case is pending, raising the annual federal borrowing limit back to $50,000 — see Updated for 2026: Which Degrees Count as Professional for Federal Student Loans? for the current list.
Major changes are coming this year for certain graduate-level healthcare degrees, including advanced nursing. Under the One Big Beautiful Bill Act signed last year, some programs are losing their “professional degree” status for federal student lending purposes.
If you’re pursuing healthcare studies, you may be wondering if and how these changes will impact you and your education. In this blog, we break down exactly what changes are coming and what they could mean for you.
**Content:**
## **New Federal Student Loan Borrowing Limits For Graduate and Healthcare Programs**
Starting July 1, 2026, you will be limited to borrowing $20,500 in Federal Direct Loans per year if you are a new student who plans to earn a Doctor of Nursing Practice (DNP) or Master of Science in Nursing (MSN) degree. Other graduate healthcare programs will be subject to the same annual limits, such as:
- Audiologists
- Certified registered nurse anesthetists
- Physician assistants
- Physical therapists
The Federal aggregate lifetime borrowing cap for these degrees will be $100,000.
For many nursing and healthcare programs, these limits may fall well below the total cost of attendance, creating new funding gaps for students. This represents a significant change from Grad PLUS loans, which covered up to the full cost of attendance and will be eliminated on the same date.
## **Impacts to the Nationwide Nursing Shortage**
Limiting access to federal student loan funding for graduate nursing programs comes as the U.S. healthcare system continues to face a[ nationwide nursing shortage](https://www.aacnnursing.org/news-data/fact-sheets/nursing-shortage). Advanced practice nurses play a critical role in delivering care, particularly in rural and underserved communities, and demand for these professionals is expected to grow. The[ U.S. Bureau of Labor Statistics projects strong job growth for advanced practice registered nurses](https://www.bls.gov/ooh/healthcare/nurse-anesthetists-nurse-midwives-and-nurse-practitioners.htm) over the next decade.
Nurses represent the largest segment of the healthcare workforce, and their role is essential to patient access and quality of care. As the[ American Nurses Association](https://www.nursingworld.org) has emphasized, policies that limit pathways into nursing education can have lasting effects on the healthcare system.
> “Nurses make up the largest segment of the healthcare workforce and are the backbone of our nation’s health system.”
> — Jennifer Mensik Kennedy, PhD, MBA, RN, NEA-BC, FAAN, President, American Nurses Association
Leaders in nursing education, including the[ American Association of Colleges of Nursing](https://www.aacnnursing.org), have warned that new federal borrowing limits could reduce enrollment in graduate nursing programs by making advanced degrees less financially accessible. Over time, these constraints may slow the pipeline of qualified nurses entering the workforce, with implications for patient care nationwide.
## **What to Do If You’re Impacted**
If you planned to enroll in a program that lost its “professional degree” status, don’t get discouraged. There are still financing options available to help you achieve your dreams. Here’s what you can do.
### **Know the Cost of Your Degree**
The first thing you’ll want to do is figure out the exact cost of your degree. You should work with your school’s financial aid office to get a very clear picture of what your education will cost.
### **Apply for Grants and Scholarships**
Grants and scholarships are financial aid sources that typically don’t have to be paid back, so you should apply for as much assistance as you can. Many schools, as well as nursing and healthcare organizations, offer grants and scholarships to put toward your education.
If you have a job, you should ask your employer about any employer tuition assistance.
### **Fill the Gap with Private Loans**
Once you’ve exhausted all options for scholarships, grants, and other assistance, you can turn to private loans to fund the rest of your expenses. Look for lenders that offer loans tailored for graduate-level healthcare degrees.
[Abe® Healthcare Professional loans](https://www.abestudentloans.com/student-loans/graduate/healthcare-professionals/) are specifically designed for nursing, pharmacy, and allied health students, with options to cover up to 100% of school-certified costs and built-in repayment flexibility such as extended deferment and forbearance options. Apply for an Abe Healthcare Professional loan [here](https://www.abe.psl.sparrowfi.com/prequalification/program-routing?utm_source=2026NursingBloge&utm_medium=defaultmedium&utm_campaign=defaultcampaign&utm_term=defaultterm&utm_content=defaultcontent&_gl=1*qlz9fm*_gcl_au*MjA1MjMxMzA3LjE3NjAzNjIyNzQ.*_ga*MjUxNjM5MTEwLjE3NDM5NzQzMjY.*_ga_RQQGJ5585R*czE3Njc4MjEyNzkkbzEyOSRnMSR0MTc2NzgyMjU3OSRqNjAkbDAkaDA.).
**Categories:** Blog, Federal Loans
---
### [Updated for 2026: Which Degrees Count as Professional for Federal Student Loans?](https://www.abestudentloans.com/blog/updated-for-2026-which-degrees-count-as-professional-for-federal-student-loans/)
**Published:** August 26, 2026
**Author:** abelending
**Excerpt:**
The Department of Education has updated its list of professional degree programs following a federal court order. Here is what changed, which programs are on the list, and what it means for your federal borrowing limits.
**Content:**
**Last updated: August 2026.** *This post reflects U.S. Department of Education guidance issued June 29, 2026 and updated July 10, 2026. The list described here is interim and can change while the case is pending.*
A federal court order on June 24, 2026 changed which graduate programs the Department of Education treats as professional degrees. The list grew from 11 fields to 29 programs, which means a lot of students who were bracing for lower federal borrowing caps may temporarily qualify for the higher one.
If you’re a graduate or professional student, that classification matters more than it used to. Grad PLUS loans went away on July 1, 2026, and Direct Unsubsidized loans have new ceilings. With professional status, you can borrow up to $50,000 a year. Without it, $20,500. Below is more information on what’s changed, which programs are classified as graduate or professional, and what to confirm with your school as you budget for next year’s studies.
## Why the List of Professional Degrees Changed
The [One Big Beautiful Bill Act](https://www.abestudentloans.com/blog/abes-plain-honest-recap-of-the-big-beautiful-bills-impact-on-federal-student-loans/?utm_source=google&utm_medium=cpc&utm_campaign=hp-search-brand&utm_term=&utm_content=abe-student-loan), signed in 2025, eliminated Grad PLUS loans (which paid for up to the full cost of graduate-level studies) and created separate borrowing caps for graduate students and professional students. It left one question open: which programs count as professional?
The Department of Education answered that in its RISE (Reimagining and Improving Student Education) Final Rule. The rule applied a four-part test and originally narrowed the list to 11 core fields: medicine, osteopathic medicine, dentistry, pharmacy, optometry, podiatry, chiropractic, veterinary medicine, law, theology, and clinical psychology. Everything else was set to fall under graduate limits.
The definition drew immediate opposition from the professions it left out. Nursing and other professional organizations, along with a coalition of states, filed legal challenges.
On June 24, 2026, the U.S. District Court for the District of Columbia issued a preliminary stay that paused four of the criteria the Department used to decide which programs qualify (34 CFR 685.102(b)). The Department responded by expanding the list of programs treated as professional for as long as the stay is in effect.
The rest of the RISE rule was not affected. Grad PLUS elimination and the new loan limits still took effect on July 1, 2026.
You can read the Department’s guidance directly in the[ FSA Electronic Announcement](https://fsapartners.ed.gov/knowledge-center/library/electronic-announcements/2026-06-29/update-list-professional-degree-programs-due-court-order-updated-july-10-2026) (published June 29, 2026, updated July 10, 2026).
## Which Degrees Now Count as Professional?
Twenty-nine programs are currently treated as professional degrees:
### Healthcare Professional Degrees List
ProgramDegreeMedicineM.D.Osteopathic MedicineD.O.DentistryD.D.S. or D.M.D.PharmacyPharm.D.OptometryO.D.PodiatryD.P.M., D.P., or Pod.D.ChiropracticD.C. or D.C.M.Veterinary MedicineD.V.M.Physician Associate / Physician AssistantM.S.P.A. or P.A.Anesthesiologist AssistantC.A.A.AudiologyAu.D.Speech-Language PathologyS.L.P.Occupational TherapyO.T., M.S.O.T., or O.T.D.Physical TherapyP.T. or D.P.T.Athletic TrainingM.S.A.T. or M.A.T.### Nursing Professional Degrees List
ProgramDegreeRegistered NursingM.S.N.Nursing PracticeD.N.P.Nurse AnesthetistD.N.A.P.Graduate nursing was left off the original list, and we wrote about[ what the loss of professional degree status would have meant for graduate nursing programs](https://www.abestudentloans.com/blog/federal-loans/what-the-loss-of-professional-degree-status-means-to-graduate-nursing-programs/). The court order reversed that outcome, at least while the stay holds.
The Department clarified on July 10, 2026 that M.S.N. and D.N.P. programs qualify even if your school codes them under a different classification within the same nursing program family, as long as the credential awarded is the same. Nurse anesthesia programs qualify under their own classification.
### Psychology Professional Degrees List
ProgramDegreeClinical PsychologyPh.D. or Psy.D.Counseling PsychologyPsy.D.School PsychologyPsy.D.Clinical Child PsychologyPsy.D.Health / Medical PsychologyPsy.D.Family PsychologyPsy.D.Forensic PsychologyPsy.D.Clinical, Counseling, and Applied Psychology, OtherPsy.D.Clinical Psychology is the only field where the Ph.D. qualifies, and the Department added it on July 10, 2026 after leaving it off the initial list. In every other psychology field here, only the Psy.D. counts. The same degree earned as a Ph.D. or a master’s falls under graduate limits.
### Other Professional Degrees List
ProgramDegreeLawLL.B. or J.D.Divinity / MinistryM.Div.Rabbinical StudiesM.H.L.## What is No Longer Considered a Professional Degree?
The update cuts both ways. Alongside the 29 programs that now qualify, the Department published a second, shorter list: 25 programs explicitly not treated as professional for the duration of the court’s stay.
These 25 are not a random cross-section of graduate education. Under the RISE rule as written, a program could qualify by sitting in the same broad subject category as one of the 11 core professional degrees. The court paused that criterion, so a program now has to be the licensure-track degree itself rather than a neighbor of one. Theology, psychology, and pharmacy are the three fields where the qualifying degree sits alongside a large group of research and administrative programs, which is why nearly every exclusion falls into one of them.
This list is not a complete inventory of programs subject to graduate limits. Any graduate program that does not appear on the 29-program qualifying list is capped at $20,500 per year, whether or not the Department named it. The 25 below are the programs close enough to a qualifying degree that the Department felt it had to rule them out directly.
### Theology and Ministry Programs No Longer Considered Professional
- Theology and Theological Studies
- Pre-Theology and Pre-Ministerial Studies
- Theological and Ministerial Studies, Other
Divinity (M.Div.) and Rabbinical Studies (M.H.L.) still qualify.
### Psychology Programs No Longer Considered Professional
- Community Psychology
- Industrial and Organizational Psychology
- Educational Psychology
- Environmental Psychology
- Geropsychology
- Applied Psychology
- Applied Behavior Analysis
- Performance and Sport Psychology
- Somatic Psychology
- Transpersonal and Spiritual Psychology
The Psy.D. tracks listed above still qualify, as does the Ph.D. in Clinical Psychology.
### Pharmacy Programs No Longer Considered Professional
- Pharmacy Administration, Policy, and Regulatory Affairs
- Pharmaceutics and Drug Design
- Medicinal and Pharmaceutical Chemistry
- Natural Products Chemistry and Pharmacognosy
- Clinical and Industrial Drug Development
- Pharmacoeconomics and Pharmaceutical Economics
- Clinical, Hospital, and Managed Care Pharmacy
- Industrial and Physical Pharmacy and Cosmetic Sciences
- Pharmaceutical Sciences
- Pharmaceutical Marketing and Management
- Pharmacy, Pharmaceutical Sciences, and Administration, Other
The Pharm.D. still qualifies.
### Medical Programs Not Considered Professional Degrees
One medical category is excluded:
- Medicine, Other, a catch-all covering medical programs that do not award an M.D. or a D.O.
The M.D. and D.O. still qualify. Your school assigns the classification, and that assignment is what sets your borrowing cap. If your program is medical but does not award an M.D. or a D.O., confirm with your financial aid office which category yours falls under before you budget against the $50,000 limit.
## What This Means For Professional Degree Loan Limits
The difference between the two classifications is $29,500 a year, and $100,000 over the course of a program.
Graduate StudentsProfessional StudentsAnnual Limit$20,500$50,000Total Per Program of Study$100,000$200,000Both categories are subject to an overall lifetime cap of $257,500 across all federal student loans, not counting Parent PLUS.
**If you were already enrolled, these caps may not apply to you yet.** Students who borrowed a federal Direct Loan in their current program before July 1, 2026 and remained enrolled through June 30, 2026 keep their previous limits, including access to Grad PLUS, for up to three additional years or the time remaining to complete the program, whichever comes first.
One more wrinkle: the Department told schools they may consider holding loans for newly reclassified programs to the lower graduate caps, because the litigation is ongoing. Your school’s financial aid office makes that call, not the Department and not you. Confirm it with them.
For the official figures, see the[ federal loan limits page on studentaid.gov](https://studentaid.gov/understand-aid/types/loans/subsidized-unsubsidized).
### Are Private Student Loans Impacted by the Professional Degree Changes?
No. The professional versus graduate distinction is a federal Direct Loan rule, and private lenders do not use the Department of Education’s program list to set borrowing limits. Private student loan amounts are based on your school’s certified cost of attendance minus other aid you receive, and on credit approval. Some lenders set their own higher limits for medical, dental, and law programs, but those are the lender’s own categories, not the federal list.
The classification still matters for what you borrow privately, because it decides the size of the gap. A student held to the graduate cap of $20,500 a year has $29,500 more to cover than one certified at the professional cap of $50,000.
One planning note: If your program was newly added to the list and the stay is later lifted, money already disbursed at the higher limit stays put, but your remaining disbursements that year drop to the graduate cap. Ask your financial aid office what happens to your spring disbursement before you decide how much to borrow privately for the fall.
## What to Do If Federal Student Loans Don’t Fully Cover Your Program
Federal caps may fall short of your total cost of attendance even with professional status, and students in programs still classified as graduate face the $20,500 annual limit. Before you decide how to cover the difference, get the details confirmed by your school.
### 6 Questions to Ask Your Financial Aid Office
Your school, not the Department of Education, decides which classification it certifies you under. That makes your financial aid office the only office that can answer these.
1. **Which classification are you certifying my program under for 2026-27, graduate or professional?**
This single answer determines whether your federal ceiling is $20,500 or $50,000 for the year. Ask for it in writing.
2. **If my program is on the interim list, are you certifying at professional limits or holding it to graduate limits while the litigation is pending?**
The Department told schools they may set program-level limits, and suggested they consider holding temporarily reclassified programs to the graduate caps. Many schools are doing exactly that. Being on the list does not guarantee you get the higher cap.
3. **If the stay is lifted mid-year, what happens to my remaining disbursements?**
Money already disbursed at the higher limit stays put. Later disbursements that year drop to the graduate cap. If your spring disbursement is at risk, you want to know that in the fall, not in January.
4. **Do I qualify for grandfathering?**
If you borrowed a federal Direct Loan in this same program before July 1, 2026 and stayed enrolled through June 30, 2026, you may keep your previous limits, including Grad PLUS access, for up to three more years or the time left to finish, whichever comes first.
5. **How much of my aggregate limit have I already used?**
Prior degrees count. Schools are reverifying aggregate usage under the new rules, and the overall lifetime cap across federal student loans is $257,500, not counting Parent PLUS.
6. **What is my certified cost of attendance, and what is my remaining gap after all federal aid, grants, and scholarships?**
This is the number a private lender certifies against. It is also the only figure that tells you how much you actually need to cover.
### If Your Program Was Newly Added, Budget Against the Lower Cap
The expanded list applies only while the court’s stay is in effect, and it can change as the case proceeds. If your program was added in June or July of 2026, build your budget against the $20,500 graduate cap rather than the $50,000 professional cap, even if your school is currently certifying you at the higher one. If the higher limit holds, you have slack. If it doesn’t, you are not scrambling for $29,500 in the middle of the year.
### If There’s Still a Gap
Abe offers private student loans for [Graduate](https://www.abestudentloans.com/student-loans/graduate/), [Law](https://www.abestudentloans.com/student-loans/graduate/law/), [MBA](https://www.abestudentloans.com/student-loans/graduate/mba/), [Medical](https://www.abestudentloans.com/student-loans/graduate/medical/), [Dental](https://www.abestudentloans.com/student-loans/graduate/dental/), and [Healthcare Professional](https://www.abestudentloans.com/student-loans/graduate/healthcare-professionals/) programs, with aggregate limits up to $350,000, and up to $500,000 for medical and dental students.1 You can choose how you pay while you are still in school, including a flat payment or full deferment until after you graduate.3
[Checking your rate](https://www.abe.psl.sparrowfi.com/prequalification/program-routing?utm_source=google&utm_medium=cpc&utm_campaign=hp-search-brand&utm_term=&utm_content=abe-student-loan&_gl=1*bl49tx*_gcl_aw*R0NMLjE3ODUyNDE2OTMuQ2p3S0NBandwcUhUQmhBY0Vpd0FqMkFmdWxPYTJjZUk4aXN0MlV5Y3I0LURPV1BDY0dGWnB0Q21PSHpaazBzVkNpUXdKQUw0R3R4UFBCb0MwZ0FRQXZEX0J3RQ..*_gcl_au*MTE3MDIwNTIzMC4xNzgyMzM1NTIx*_ga*NTI1NDkwODE5LjE3ODIzMzU1MjE.*_ga_RQQGJ5585R*czE3ODU4NzEyNjckbzYyJGcxJHQxNzg1ODczNjgzJGozOSRsMCRoMA..) takes a few minutes and has no impact on your credit score.2
**Categories:** Blog
---
### [Abe’s Plain, Honest Recap of The Big Beautiful Bill’s Impact on Federal Student Loans](https://www.abestudentloans.com/blog/abes-plain-honest-recap-of-the-big-beautiful-bills-impact-on-federal-student-loans/)
**Published:** July 30, 2025
**Author:** Abe
**Excerpt:**
On July 4th, 2025, President Trump signed into law the One Big Beautiful Bill Act (commonly called the “Big Beautiful Bill”) after narrow passage by Congress. In addition to SNAP (subsidized food benefits) and Medicaid (subsidized medical care), the bill effectively reforms federal student loan programs.
Going forward, students and their families must take into account new rules and guidelines for both borrowing and repaying federal money for college and/or graduate school.
**Content:**
## **How the bill affects federal student loan repayment**
The bill phases out all existing income‑driven repayment plans—including SAVE, PAYE, and ICR—and replaces them with two options:
1. A standard, fixed payment program with terms of 10-25 years
2. The Repayment Assistance Plan (RAP) that uses the borrower’s income to determine their monthly payment amount (1%-10% of adjusted gross income), up to a term of 30 years.
Current holders of federal student loans have until July 1, 2028 to convert to one of these two repayment plans. It’s also important to note that if you are one of the 7.7 million borrowers in the SAVE program, interest on your loan will begin to accrue starting August 1, 2025.
As of July 1, 2026, new federal student loan borrowers will need to sign up for one of the two new repayment options. Which one should you choose? It depends.
With the standard, fixed payment plan, you’ll know exactly what your repayments and terms will be. On the other hand, if you are uneasy about committing to a repayment amount before you join the workforce and start earning a paycheck, you may be more comfortable choosing the Repayment Assistance Plan. The RAP plan also contains two notable features designed to help lower income borrowers. First, any interest not covered by the monthly payment is waived. And second, there is a subsidy for those whose payments barely reduce their loan’s principal amount. If your monthly payment reduces your principal by only $10, the federal subsidy will kick in to reduce it by $50 (this is just an example).
## **What about repayment deferment and forbearance?**
There are two ways to ‘pause payments’ on federal student loans: deferment and forbearance. What are the differences between them? First, deferment typically lasts longer than forbearance, and second, interest does not accrue on certain federal student loans in deferment while it does on loans in forbearance.
In-school payment deferment (waiting until after graduation to begin loan repayment) will still be available for students enrolled at least half-time. However, as of July 1, 2027, new borrowers will no longer be able to defer their payments *after* graduation due to unemployment or economic hardship.
Loan forbearance, the second form of payment suspension, will still be available for students experiencing financial difficulties. However, the length of time a borrower can be in forbearance will be shorter: 9 months instead of 12.
One notable exception is for students who pursue a career in public service or the non-profit sector. In such cases, they may still be eligible for Public Service Loan Forgiveness (PSLF).
## **New loan limits: how the bill impacts how much you can borrow for college**
### *Direct Student Loans*
There are two basic types of federal student loans. Direct Subsidized loans are for students that demonstrate financial need. The government pays the accruing interest on these loans while they’re in deferment to ease the overall financial burden on the borrower. Direct Unsubsidized loans are for students who don’t demonstrate financial need and therefore are responsible for paying all the interest on their loans.
The Big Beautiful Bill caps the maximum aggregate borrowing limit per student at $257,500 for both Direct Subsidized loans and Direct Unsubsidized loans.
### *Parent Plus Loans*
Parents or guardians who take out [Parent Plus](https://studentaid.gov/understand-aid/types/loans/plus/parent) loans before July 1, 2026 can continue to borrow under the current guidelines until the 2028-2029 academic year. Parent Plus loans will still be available for those who apply after July 1, 2026, but loan amounts will be capped at $20,000 per year with a maximum cap of $65,000 per child. Additionally, Parent Plus loans will only be available after exhausting the student’s annual Direct (subsidized or unsubsidized) loan eligibility.
### *Graduate School Loans*
As for graduate students, the [Grad Plus](https://studentaid.gov/understand-aid/types/loans/plus/grad) program will be eliminated on July 1, 2026. Students will no longer be allowed to borrow up to the total cost of their graduate degree. Instead, borrowing amounts will be capped at $20,500 a year with a lifetime graduate school maximum limit of $100,000.
There are exceptions in the bill for students seeking a professional graduate degree. If, for example, you’re studying to become a medical doctor or a lawyer, you can borrow up to $50,000 a year with a maximum aggregate cap of $200,000.
## **What about Pell Grants?**
[Pell Grants](https://studentaid.gov/understand-aid/types/grants/pell) are for lower income students. The new bill actually expands Pell Grants to include job-training programs. On the other hand, as of July 2026, students who qualify for a full-ride scholarship or have a very low [Student Aid Index](https://studentaid.gov/help-center/answers/article/what-is-sai) may become ineligible. The bill also raises the full-time requirement to 15 credits (up from 12).
## **How does the Big Beautiful Bill impact college and university financial aid programs?**
One objective of the Big Beautiful Bill is to incent higher education to validate its value. Under the new bill, schools risk losing federal funding for academic development and research programs if undergraduates end up earning less after graduation than someone with only a high school diploma. This could curtail a school’s financial aid program and therefore limit its ability to compete for incoming classes.
Additionally, the bill applies a higher tax rate on colleges with endowments: anywhere from 1.4 to 8%. Since colleges use their endowments to fund financial aid programs, this tax may also impact the amount of money they can award to students in the form of scholarships and grants. Again, there is an exception here. Institutions with fewer than 3,000 students are exempt from the endowment tax.
## **Now for the good news.**
While the Big Beautiful Bill definitely impacts how undergrad and grad students pay for college, the new rules and guidelines ease in over a period of several years. Despite the new lending limits, there will still be plenty of federal funding available and the two new repayment plans provide a choice of fixed payments or income-based payments – the latter similar to the current IDR (Income Driven) repayment plan.
It’s also important to remember that private student loans will always be an option for covering college expenses when college savings plans, federal loans, grants and scholarships fall short. In many cases, a private loan offers more deferment and forbearance options, especially for students experiencing financial hardship or job loss.
Now more than ever your school’s financial aid office should be your first call when determining the best way to pay for your education. Their financial aid officers are true heroes and guide millions of students and their families every year through the college financing planning process. If you have more questions about how the Big Beautiful Bill impacts your particular situation they will be glad to answer them.
**Categories:** Blog
---
### [How to Find the Right Cosigner for Your Student Loan](https://www.abestudentloans.com/blog/how-to-find-the-right-cosigner-for-your-student-loan/)
**Published:** July 29, 2026
**Author:** abelending
**Excerpt:**
Key Takeaways:
- Parents are usually a student’s first choice for cosigning their student loan, but they’re not the only option
- Any trusted adult who wants to help can be a cosigner
- Each lender will have its own requirements, but cosigners should generally be adults with stable income and good credit
- Asking someone to be a cosigner is a big responsibility, so it’s important you’re honest about what you’re asking and come prepared with facts
**Content:**
Choosing the right cosigner for your student loan is crucial, especially if you’re looking to increase your approval chances and get the best possible interest rate. Whether you’re trying to learn about cosigner requirements or need tips on how to ask someone to cosign your loan, this blog will help you better understand your options.
## **Who Can Be a Cosigner on a Student Loan?**
Most students immediately think of their parents [when looking for a cosigner](https://www.abestudentloans.com/blog/do-i-need-a-cosigner-for-my-student-loan/). But there are some scenarios where a parent isn’t in a position to cosign. If that’s the case, you’re not out of luck. Almost any creditworthy adult can be a student loan cosigner.
Here are some of your options:
- **Parents:** Any parent, step-parent, or legal guardian
- **Other Family Members:** Grandparents, aunts, uncles, siblings over the age of 18, or even a spouse
- **Family Friends:** Any trusted non-relative adult who wants to see you succeed
- **Mentors:** Advisors or other adult individuals you know in a professional or educational setting
### Avoid Risky Online Cosigner Sites
Keep in mind, your cosigner should always be someone you know personally and trust. Websites and services that claim they can match you with a qualified cosigner are extremely risky, and may even involve fraud.
It’s best to ask a close, trusted individual adult with whom you have an established relationship.
### Cosigner Qualifications
The biggest thing to consider before you ask someone to cosign your loan is whether they’re eligible. Specific cosigner requirements may differ between lenders, but are generally similar overall.
Depending on the relationship you have with them, you may not know the specifics of a potential cosigner’s financial history. But you can still check that they meet some overall requirements.
- **Age:** Cosigners need to be adults – usually at least 18 years old, though the exact age can vary depending on the lender or state
- **Citizenship:** Most lenders require cosigners to be U.S. citizens or permanent residents
- **Stable Income:** Cosigners should have a job that provides a stable source of income, they’ll need to prove this during [the application process](https://www.abestudentloans.com/blog/what-to-know-about-applying-for-private-student-loans/)
Beyond having a stable income, a cosigner should be creditworthy. They’ll likely need to show a history of on-time payments with no recent bankruptcies or debts sent to collections.
Credit score requirements will vary by lender, but a cosigner should fall in one of the following ranges:
- Good (670-739)
- Very Good (740-799)
- Excellent (800-850)
Higher credit scores typically unlock lower interest rates, which means you’ll end up paying less in the long run. You can learn more about how interest rates impact your total loan payment using our [**Student Loan Calculator**](https://www.abestudentloans.com/resources/student-loan-calculator/).
## How to Ask Someone to Cosign Your Student Loan
Asking someone to be your cosigner is a significant request that comes with a lot of responsibility. Once you’ve decided who you want as a cosigner, you should plan how you’re going to talk to them about it.
### Be Honest About the Responsibility
One of the most important things is being honest about what exactly you’re asking this person to do and what it means for them if they accept. Explain that cosigning your loan means they will share legal responsibility for repaying that money. Outline the associated risks, like impacts to their credit score and debt-to-income ratio. You can also point out that making on-time payments will help their credit score.
Acknowledging the gravity of your request will show your potential cosigner that you understand just how much responsibility you’re asking them to take on.
You should also be transparent with them about why you’re asking them to cosign – whether it’s because you don’t qualify on your own or do but want a lower interest rate. It may also help to share your goals with them, like the degree you’re looking to earn, how many years you expect to be in school, and what career you’re hoping to pursue after graduating.
### Come Prepared with the Facts
You should be ready to answer questions and present any information your cosigner may want to know about your financial needs.
One of the most important factors you’ll want to share is your total loan amount. This gives your cosigner a better idea of how much money they’re taking responsibility for. You should also tell your cosigner what you’ve done to ensure you’re borrowing the lowest possible amount in private student loans. Let them know [you’ve exhausted all other options](https://www.abestudentloans.com/blog/financial-aid-alternatives-to-consider-before-taking-out-a-private-student-loan/), including federal loans, school financial aid, and scholarships.
In addition to the loan amount, some other baseline facts you should be prepared to share include:
- **Lender:** Who you plan on borrowing from (or the different options you’re considering)
- **Interest Rates:** What interest rate range your potential lenders offer
- **Terms:** Repayment plans (option and term), grace period details, relief options, and other loan details
You can also explain that being a cosigner doesn’t have to be permanent. Some private student loans, like Abe®, offer early cosigner release13 which relieves them of their responsibilities. If that specific perk isn’t available, you have other options you can explore to release your cosigner, like refinancing your loan(s).
### Share Your Plans For Repayment
Another factor you should be prepared to discuss is how you’ll make payments after graduation. Since your cosigner will be held responsible for making payments as well, sharing any plans you have will help ease their mind and show that you’re thinking ahead.
For example, let them know if you have savings built up to put toward payments, or if you plan to work during school to build a savings account. You can also discuss job numbers or average salaries associated with your field of study.
### Don’t Expect an Answer on the Spot
Don’t expect your potential cosigner to give you an answer on the spot. Give your potential cosigner time to think about their decision, and keep in mind they may need to discuss it with a spouse or even a financial advisor.
## What Happens Next?
If the person you asked to be your cosigner says no, don’t take it personally. There may be factors you’re unaware of that impacted their decision. Start to think about who else you can talk to about cosigning your loan.
If your cosigner says yes, you should set aside time to look at your student loan application together. [When it’s time to apply](https://www.abestudentloans.com/blog/what-to-know-about-applying-for-private-student-loans/), you’ll both need information like your birth date, Social Security number, and income details – and they may need time to gather that documentation.
## Ready to Apply for Your Loan?
If you’re still looking for a private student loan, Abe offers loans with competitive rates, flexible repayment options,3 and early cosigner release after just 12 months of on-time payments.13 You can [find your rate](https://abe.psl.sparrowfi.com/) in minutes with no impact on your credit score.2
**Categories:** Blog
---
### [What Are the Differences Between Federal and Private Student Loans?](https://www.abestudentloans.com/blog/what-are-the-differences-between-federal-and-private-student-loans/)
**Published:** July 28, 2026
**Author:** abelending
**Excerpt:**
Federal student loans and private student loans have some similarities, but knowing the differences will help you make the best decision for your finances. Abe is here to help guide you through the details.
**Content:**
Student loans can come from many different funding sources. There are multiple lenders and loan types to choose from, but one of the most important distinctions is the difference between federal and private student loans. Understanding these two options and how they differ is a fundamental step in making a good financial decision.
Both federal and private student loans can seem complicated. Abe created this guide to clearly break down the differences, helping you choose the option that best fits your financial and educational needs.
## Federal vs. Private Student Loans: Key Differences
Federal and private student loans differ in several key categories, including the funding source, interest rates, eligibility, and repayment flexibility. Here’s a brief overview of each across these areas.
Federal Student LoansPrivate Student LoansFunding SourceThe U.S. Department of Education funds the loan.Banks, fintechs, credit unions, or other private lenders fund the loan.Interest RatesInterest rates are fixed and set each year.Interest rates can be fixed or variable, and are based on credit. Applicants with good credit often receive lower rates.EligibilityEligibility is based on economic need.Eligibility is based on creditworthiness: the ability of the borrower(s) to repay the loan.Repayment FlexibilityFlexible repayment plans, loan forgiveness available in some cases.Repayment and relief options vary by lender.Application ProcessApplicants must file the Free Application for Federal Student Aid (FAFSA®).Applicants should start by filing the FAFSA to identify any funding gap before applying for a private student loan, which can typically be done online.Lending LimitsBorrowers can take out a lifetime maximum of $257,500 in government loans, only $23,000 of which comes from subsidized loans.Limits vary by lender but are generally higher than federal student loan limits.CosignersCosigners are not required.Cosigners are typically not required but students applying with a limited credit history typically need a cosigner for approval.FeesTypically, 1.057% for Direct Subsidized/Unsubsidized loans and 4.228% for PLUS loans.Fees vary by private lender, but most do not charge origination fees.Federal loan origination fees shown apply to Direct Loans first disbursed on or after October 1, 2020, and before October 1, 2026. Rates are set by the U.S. Department of Education and are subject to change. Source: Federal Student Aid, studentaid.gov.## Loan Source
One of the most basic differences between federal and private student loans is who funds them. A federal loan, as the name suggests, is funded by the federal government — more specifically, the Department of Education. By contrast, a private loan, like Abe®, is funded by a private lender, such as a bank, credit union, or fintech company.
Because private student loans can be funded by varying sources, the terms offered by each lender can differ widely. Consequently, you should always compare rates, eligibility, repayment options, and other factors between lenders if you are considering a private student loan.
## Interest Rates
Federal and private student loans also differ in the interest rates offered. While federal rates are fixed and set each year, private student loan rates can be either fixed or variable, depending on the lender.
You can check current federal interest rates on the official [Federal Student Aid](https://studentaid.gov/understand-aid/types/loans/interest-rates) website. Keep in mind that Direct Subsidized Loans, Direct Unsubsidized Loans, and Direct PLUS Loans all have unique rates, so double-check to ensure you’re looking at whichever loan type applies to you.
Some private student loan lenders offer fixed rates, which do not change for the life of the loan, while others offer variable rates, which can fluctuate up or down across the life of the loan. In general, private student loan rates are often higher than federal student loan rates, but they can be lower for applicants with good credit in some cases. Student applicants can often qualify for a lower rate by adding a creditworthy cosigner to their application.
## Eligibility
Another important difference between federal and private student loans is how eligibility is determined. Federal student loans are awarded based on the financial need of the applicant(s). Applicants must complete and submit the [Free Application for Federal Student Aid](https://www.usa.gov/fafsa) (FAFSA®) form for the government to determine whether they are eligible and for how much.
Private student loans are based on creditworthiness, just like car or home loans. Applying for a private student loan will entail a credit check, where the lender pulls your credit report to get a picture of your ability to pay back the borrowed amount.
Because a hard credit pull impacts your credit score, many lenders offer prequalification tools to give you an idea of your eligibility before submitting for a hard credit pull. Prequalification involves a soft credit pull, which does not impact the credit score(s) of the applicant(s), but gives you enough information upfront to make an informed decision before moving forward with submitting for a hard credit pull.
Many student applicants applying for an education loan do not have a credit history, which is where [cosigners](https://www.abestudentloans.com/cosigners/) come in. While you do not necessarily need to have a cosigner to apply for a private student loan, having one can improve your approval chances and may get you a better rate.
Private student loans may allow higher borrowing limits for eligible students than federal student loan alternatives. Currently, there is a [$257,500 lifetime maximum](https://studentaid.gov/announcements-events/big-updates/definitions#loan-limits) borrowing limit on federal student loans for any student applicant, and only $23,000 of that can be [subsidized](https://www.abestudentloans.com/resources/student-loan-college-financing-glossary/#federal-student-loans). The difference comes down to who covers the interest: on subsidized loans, the government pays the interest while you’re enrolled at least half-time and through your grace period, but these are reserved for undergraduates with demonstrated financial need. Unsubsidized loans are open more broadly, to undergraduate and graduate students regardless of need, but interest starts adding up the moment the loan is disbursed, so the balance can grow before the first payment is ever made and it is the borrower’s responsibility to pay it back. Private student loan borrowing limits typically go beyond the federal cap for those who are eligible.
## Fees
Federal student loans charge you an origination fee. This is a charge to cover processing of your loan and may vary depending on the type of federal student loan you are seeking. Origination fees are typically 1.057% of the total loan amount for Direct Subsidized and Unsubsidized loans and 4.228% for Direct PLUS loans.
Private student loans typically do not charge origination fees. For private lenders who do charge origination fees, the amount varies depending on the lender.
## Benefits, Discounts, and Rewards
Both federal and private student loans offer varying borrower benefits and discounts that are worth considering. Federal student loans offer a [1% interest rate reduction](https://www.ed.gov/about/news/press-release/us-department-of-education-announces-student-loan-interest-rate-reduction) for eligible borrowers who enroll in auto pay, and some government or not-for-profit employees may qualify for [public student loan forgiveness (PSLF)](https://studentaid.gov/manage-loans/forgiveness-cancellation/public-service), a program that forgives a borrower’s remaining balance after meeting certain employment and repayment criteria.
As with many other categories, private student loan benefits, discounts, and rewards vary by lender. Abe offers an [interest rate discount for auto pay](https://www.abestudentloans.com/loan-details/#rate-discounts),18 as well as rate reductions for every six months of consecutive, on-time payments, up to 0.25%.9 Graduates may also receive a 2% reduction of their principal balance upon request as a reward for completing their degree,8 and borrowers can apply to release their cosigner after just 12 months of on-time payments.13
## Repayment Flexibility
While federal student loans may come with lower borrowing limits, they do tend to be more flexible than many private student loan options. The Department of Education allows you to change your repayment plan based on your current needs, and loan forgiveness is sometimes available for certain borrowers.
As in many other categories, repayment options vary by lender when it comes to private student loans. Some lenders are inflexible, but Abe [offers multiple loan options](https://www.abestudentloans.com/loan-details/#options), including five different loan terms,3 in-school payment plans, deferment,20 and the potential for rate discounts. And if the unexpected happens while you’re still in school, Abe offers In-School Default Protection4 which automatically shifts eligible loans into full deferment — pausing payments while you are enrolled in school rather than letting the loan slip toward default. It’s a built-in way for your repayment to flex when your circumstances change, much like the adjustments you’d make on the federal side.
## Other Factors to Consider
Funding source, interest rates, eligibility, borrower benefits, and repayment flexibility are the most important differences between federal and private student loans. However, there are other, smaller distinctions to consider, too.
Many federal undergraduate loans are subsidized, which means the government will cover any interest the loan accrues while you are enrolled at least half-time. Unsubsidized loans are available to a wider range of students but charge and collect on interest while you are enrolled. Private student loans are more similar to unsubsidized loans, as you are responsible for paying back the interest that accrues while you are enrolled in school.
The application process likewise varies between the two. Applying for a federal student loan means filling out the FAFSA, which involves providing documentation to prove your eligibility, and selecting at least one school to receive your information. With a private student loan, you must complete an application and may also be required to provide documentation to verify your creditworthiness rather than your financial need.
If you want to attend graduate school, you should also consider how federal and private student loans differ. All federal graduate student loans are unsubsidized, but the borrowing limit is often much higher than undergraduate limits. Abe likewise offers higher limits for graduate and professional programs.1 Private lenders vary widely in their graduate options and terms, so always perform thorough research before making a decision.
## Federal vs. Private Student Loans: Which Is Right for You?
In general, it’s best to max out your federal opportunities before pursuing a private student loan. The savings potential from unsubsidized loans, wider availability, and repayment flexibility all make federal student loans worth prioritizing. Once you have received all the federal aid you can, though, a private loan can be a useful way to cover the remaining costs.
After you have maximized your federal aid, you should compare private student loans to get the best deal for your needs. Start by looking at each lender’s [eligibility criteria](https://www.abestudentloans.com/loan-details/#eligibility) to see what you may qualify for, and then compare interest rates, repayment options, and loan terms. That includes expected payoff timelines, what the loan covers, and borrowing limits.
Private lenders offering more flexibility and potential discounts are worth considering above more rigid options. As you look, remember to consider whether you would need a cosigner or how having one could help you secure better loan terms. Having a cosigner with good credit can be an excellent way to reduce your overall payments, where available.
## Learn More About Private Student Loans Today
Now that you know what the difference is between federal and private student loans, you can take steps toward a more informed decision. Taking out a loan is a big responsibility, so thorough research is crucial to making the best choice. That includes recognizing why it’s important to maximize federal opportunities before applying for a private student loan, as well as how to choose between private lenders to cover the rest.
You can explore our [frequently asked questions](https://www.abestudentloans.com/resources/#faq) to learn more about private student loans and what to expect from an Abe student loan. Our [blog](https://www.abestudentloans.com/blog/) has additional resources for you to learn about student loans to help you make a more confident decision.
**Categories:** Blog
---
### [The College Investor - New Graduate School Loan Limits Start July 1: What Students Need to Know](https://www.abestudentloans.com/news/the-college-investor-new-graduate-school-loan-limits-start-july-1-what-students-need-to-know/)
**Published:** June 19, 2026
**Author:** abelending
**Excerpt:** The way students pay for graduate school is about to change. Starting July 1, 2026, the federal government will stop offering Grad PLUS loans to new borrowers and will set new caps on how much graduate and professional students can borrow each year.
**Categories:** News
---
### [Financial Aid Alternatives to Consider Before Taking Out a Private Student Loan](https://www.abestudentloans.com/blog/financial-aid-alternatives-to-consider-before-taking-out-a-private-student-loan/)
**Published:** June 17, 2026
**Author:** abelending
**Excerpt:**
Private student loans can help bridge funding gaps, but they should be the final step after exploring other options first. Learn about financial aid alternatives, from federal student loans and grants to 529 plans and employer tuition assistance, that can reduce or eliminate the need to borrow privately.
**Content:**
The cost of college is more than just tuition; it’s also room and board, books, supplies, living expenses, and fees. When your existing financial aid offer doesn’t cover everything, a private student loan can fill the gap. But before you borrow, it’s worth considering other sources of aid first.
Understanding the financial aid landscape is particularly important this year. [Changes from the One Big Beautiful Bill Act (OBBBA)](/blog/abes-plain-honest-recap-of-the-big-beautiful-bills-impact-on-federal-student-loans/), effective July 1, 2026, cap Parent PLUS and graduate loan limits, which could leave some families with a larger gap to fill. The phaseout of the federal Grad PLUS loan, which pays up to the full cost of graduate-level programs, also begins July 1.
This guide from Abe® walks through the options to consider before you borrow privately, from federal loans and grants to savings plans and employer benefits.
## What is a private student loan?
A private student loan is a credit-based education loan issued by a bank, credit union, or online lender, not backed by the U.S. government, that typically requires a credit check or cosigner and lacks federal borrower protections like income-driven repayment or loan forgiveness.
Private student loans can be a helpful tool, but they work best after you’ve exhausted federal aid, grants, scholarships, savings, and school or state-based programs. For perspective, about 14% of all student loans in 2024–25 were nonfederal, a category that includes private, state, and institutional loans \[1\].
## Before taking out a private student loan, maximize federal student aid by filing the FAFSA.
Most students who need financial assistance should apply for federal student loans before researching other sources of debt. These loans generally offer stronger borrower protections and broader eligibility than private student loan products.
The first step is to file the FAFSA, the Free Application for Federal Student Aid. That single application can unlock several types of federal support, including:
### Direct Subsidized Loans
Need-based loans for eligible undergraduate students: The government covers the interest while you are enrolled at least half-time, during your grace period, and during approved deferment periods.
### Direct Unsubsidized Loans
Available to eligible undergraduate and graduate students and not based on financial need: Interest starts adding up from the day the loan is disbursed, including while you are in school.
### Pell Grants
A Pell Grant is a need-based federal grant from the U.S. Department of Education that helps undergraduate students pay for college and does not have to be repaid. Eligibility and the award amount are determined by the FAFSA, based primarily on the Student Aid Index, cost of attendance, and enrollment status.
### Work-Study
Federal Work-Study is a need-based program that funds part-time jobs for undergraduate and graduate students. Eligibility is determined through the FAFSA.
**Pro Tip:** FAFSA processing delays have pushed out aid offers in recent years, leaving some students less time to compare options before May 1 decision deadlines \[2\]. File as early as you can, and keep a backup plan in case your award arrives late.
## Explore grants and scholarship opportunities.
Grants and scholarships are money you don’t have to pay back, which makes them the most cost-effective way to reduce how much you borrow, especially through private student loans. A little extra effort here can lower your loan balance for years to come.
### Grants
A grant is need-based financial aid, usually from the federal government, a state, or your school, that does not have to be repaid.
The opportunity is real. Among private loan borrowers, 36% received Pell Grants and 51% received need-based grant aid from some source \[3\]. That overlap suggests many students who turned to private loans might have borrowed less by researching more grant opportunities first.
### Scholarships
A scholarship is merit or criteria-based funding awarded by schools, organizations, or private entities that does not have to be repaid.
### Where to Find Grants and Scholarships
You can find grant and scholarship money in more places than most families realize. Start here:
- Federal Pell Grants, awarded through the FAFSA.
- State-specific grant programs, often run through your state’s higher education agency.
- Institutional grants and merit scholarships offered directly by the colleges themselves.
- Private and nonprofit scholarships, community foundations, and professional associations.
Employer scholarships deserve a closer look too. Some companies fund awards for employees or their family members, and these often draw smaller applicant pools. For a deeper list of places to search, see Abe’s roundup of[ where to find college scholarships](https://www.abestudentloans.com/blog/scholarships/top-14-places-to-find-college-scholarships/).
**Pro tip:** if your financial circumstances have changed since you filed the FAFSA, ask your school to reconsider your aid package. Many schools will reassess an award when a family’s situation shifts.
## Use 529 plans and education savings strategies.
Saving changes the math; yet, the tool built for it sits largely unused. Close to 70% of college savers are not using a 529 plan, and roughly $1.3 trillion in education savings sits in cash, retirement, and other non-529 accounts \[2\].
### What is a 529 Plan?
A 529 plan is a tax-advantaged savings account built specifically for education expenses. Your contributions grow tax-free, and withdrawals for qualified education costs are not taxed at the federal level.
How you own those savings matters for financial aid. The federal aid formula counts up to 5.64% of parent-owned assets, compared with about 20% for student-owned assets \[2\]. When it’s practical, steering college savings into a parent-owned 529 can improve your eligibility for more need-based federal aid.
Here is how common account types compare:
Account typeImpact on federal aidParent-owned 529Lower impact; up to 5.64% of assets assessedStudent-owned 529Lower impact; treated as a parent asset, so up to 5.64% of assets assessedUTMA or UGMA custodial accountHigher impact; up to 20% of assets assessedTaxable brokerage accountFully countable as assets, with no education tax advantagesFigures apply to dependent students and reflect the Student Aid Index (SAI) on the current FAFSA. A 529 is assessed at a maximum of 5.64% whether a parent or the student owns it.
### Trump Accounts: A New Education Savings Option
The One Big Beautiful Bill Act also created Trump Accounts, a new tax-deferred investment account for children under 18. Children who are U.S. citizens and born between January 1, 2025, and December 31, 2028, qualify for a one-time $1,000 federal seed deposit, and parents, relatives, and employers can add up to $5,000 a year once contributions open in July 2026 \[7\].
The money is invested in low-cost stock index funds, and after the child turns 18, it can go toward education, a first home, or starting a business without the standard early-withdrawal penalty \[7\]. There is a tradeoff worth understanding: a Trump Account is not a dedicated education account. Its education withdrawals are not federally tax-free the way a 529’s are, and how it affects financial aid is still being clarified. For families saving specifically for college, a Trump Account tends to work best alongside a 529 rather than in place of one \[7\].
**Pro Tip:** Starting late still helps. Every dollar you save is a dollar you do not borrow with interest attached.
## Investigate school and state-based aid programs.
Beyond federal aid and outside scholarships, your school and your state may offer other sources of assistance that cost less than a private loan. These programs are easy to miss because they are not always advertised.
It’s worth researching options like these \[4\]:
- Institutional emergency loans or grants, which are short-term and often interest-free.
- Tuition installment or payment plans that spread your bill across the semester without interest.
- State-specific loan programs, which often carry fixed rates and borrower protections.
- College completion grants for students close to graduation who hit a funding shortfall.
Reach out to your school’s financial aid office early in the process and ask which institutional and state options you qualify for before you look at private loans.
## Consider Income Share Agreements and Employer Tuition Assistance
Two more alternatives tend to fly under the radar. One ties repayment to your future earnings, and the other can cover costs you would otherwise borrow.
### Income Share Agreement (ISA)
An income share agreement (ISA) is a financing arrangement in which a student receives a loan for education and pays back an agreed-upon percentage of their post-graduation income for a set period after they begin working.
ISAs come with tradeoffs. Supporters point to potential gains in completion and recruitment, while critics warn that some agreements are lightly regulated and can produce discriminatory outcomes \[5\]. If you consider one, read the terms closely, including the income threshold, the percentage you owe, any payment cap, and the length of the contract.
### Employer Tuition Assistance
Many employers offer tuition reimbursement, and under current IRS rules they can provide up to $5,250 per year tax-free. These benefits are often undervalued and can reduce or even remove the need for a private student loan. Before you borrow, check with your HR department to see what your employer, or a parent’s employer, offers.
### Military Education Benefits
Military families have additional options worth exploring, including the GI Bill and Tuition Assistance, which can fund education without borrowing.
## If you need a private student loan to close the gap…
### Plan Borrowing and Repayment Carefully
Sometimes a private student loan is the right call after every other source comes up short. Start from one principle: do not borrow money you don’t actually need, and use a loan repayment estimator to see the long-term cost before you commit \[4\]. From there, a simple flow keeps you on track:
1. Add up your total cost of attendance, then subtract all grants, scholarships, savings, and federal loans.
2. Identify the exact gap that remains. That figure is the most you should borrow.
3. Run the numbers through a[ loan repayment calculator](https://www.abestudentloans.com/resources/student-loan-calculator/) to project monthly payments across different rates and terms.
4. Compare at least three to five loans on rates, fees, and repayment flexibility.
5. Choose the smallest amount and the shortest term you can comfortably handle.
It also helps to understand disbursement timing. Loans for a full academic year are usually split into equal disbursements by term. For example, a $10,000 loan covering fall and spring is typically released as two $5,000 disbursements, one applied to each term \[4\].
Borrow conservatively. Student loan delinquency rates run high compared with other types of consumer debt, which is a good reason to keep your balance as low as you reasonably can \[6\].
### Seek Professional Financial Aid Counseling and Resources
Good guidance can change the quality of a borrowing decision, and plenty of students don’t realize help is available. In-person financial aid counseling tends to be more effective, though many aid offices lack the resources to offer it widely \[6\]. That makes it worth asking your school directly for a one-on-one meeting.
Keep in mind that schools cannot require steps beyond the federally mandated entrance counseling before you access federal student loans \[6\], so the initiative to seek extra guidance usually has to come from you. A few resources to lean on:
- Your school’s financial aid office. Ask about the Self-Certification form you will need for a private student loan.
- [StudentAid.gov](https://studentaid.gov/) for federal loan tools and FAFSA filing.
- Nonprofit credit counseling organizations, such as agencies that belong to the National Foundation for Credit Counseling (NFCC).
- Abe’s[ blog](https://www.abestudentloans.com/blog/) for ongoing student loan and college financing guidance.
An informed decision now can save you thousands of dollars and years of repayment stress later.
## Abe private student loans can help cover what’s left.
If you’ve worked through these alternatives and still have a gap between your costs and your resources, a private student loan can bridge the difference. When you reach that point, compare Abe’s [competitive rates and borrower benefits](https://www.abestudentloans.com/) and[ find your rate](https://abe.psl.sparrowfi.com) in minutes with no impact on your credit score.2
## Frequently Asked Questions
### What is the first step before considering a private student loan?
Start by filing the FAFSA, the Free Application for Federal Student Aid. It unlocks federal subsidized and unsubsidized loans, grants, and work-study, which generally offer lower rates and stronger borrower protections than private student loans.
### How do grants and scholarships reduce the need to borrow?
Grants and scholarships are money you do not repay, so every dollar you win directly lowers the amount you need to finance. Prioritizing these awards, from federal Pell Grants to institutional and private scholarships, can shrink or even close the gap that might otherwise require a private student loan.
### Can students get federal loans without parental involvement?
Yes. Independent students can access federal Direct Loans by filing the FAFSA on their own. Dependent students facing special circumstances, such as estrangement from their parents, can request a dependency override through their school’s financial aid office to be considered independent.
### What payment plans or emergency aid are available from schools?
Many colleges offer interest-free tuition installment plans that break semester costs into monthly payments, along with emergency grants or short-term institutional loans for students hit by unexpected shortfalls. Contact your financial aid office early to learn what your school provides.
### When is a private student loan appropriate despite other options?
A private student loan makes sense once you have maximized federal aid, grants, scholarships, savings, and institutional programs and still have a verified gap between your cost of attendance and your available resources. At that point, compare several loans on rates, terms, and borrower protections before you commit.
## External References
\[1\] [financialplanningassociation.org. Rethinking education funding.](https://www.financialplanningassociation.org/learning/publications/journal/JAN26-rethinking-education-funding-OPEN)
\[2\] [am.jpmorgan.com. FAFSA Fiasco: Navigating the chaos, challenges, and changing rules.](https://am.jpmorgan.com/content/dam/jpm-am-aem/americas/us/en/investment-strategies/fafsa-fiasco-navigating-the-chaos-challenges-and-changing-rules.pdf)
\[3\] [ticas.org. Private Student Loans Facts and Trends.](https://ticas.org/wp-content/uploads/2025/09/Private-Student-Loans-Facts-and-Trends_updated-9-2025.pdf)
\[4\] [buffalo.edu. Types of private loans.](https://www.buffalo.edu/financialaid/basics/types/loans/private.html)
\[5\] [aplu.org. Addressing student need beyond crisis management.](https://www.aplu.org/wp-content/uploads/addressing-student-need-beyond-crisis-management.pdf)
\[6\] [federalreserve.gov. Student loan counseling challenges and opportunities.](https://www.federalreserve.gov/consumerscommunities/files/student-loan-counseling-challenges-and-opportunities-2016.pdf)
\[7\] [irs.gov. Trump Accounts.](https://www.irs.gov/trumpaccounts)
**Categories:** Blog
---
### [Top 14 Places to Find College Scholarships](https://www.abestudentloans.com/blog/scholarships/top-14-places-to-find-college-scholarships/)
**Published:** April 1, 2026
**Author:** abelending
**Excerpt:**
Applying for college scholarships can be time-consuming, but the biggest challenge is usually finding them. It’s not that scholarships don’t exist; it’s that they’re scattered everywhere. They’re offered by schools, businesses, community organizations, and foundations you may have never heard of.
To make your search a little easier, we’ve pulled together a list of trusted sources where you can look for scholarships, along with some tips to keep in mind when applying. Whether you’re a high school senior just getting started, a current college student, or a parent helping your child navigate the process, this list is for you.
**Content:**
## What Kinds of Scholarships Are Out There?
Most people know about academic and athletic scholarships, but those are just the beginning. Scholarships exist for all kinds of students and situations, including:
- Your religion, cultural background, or ancestry
- Your intended major or career path
- Community service and volunteer work
- Artistic ability, writing, or creative talent
- Financial need or first-generation student status
- “Unusual” scholarships based on unique traits — even things like height or left-handedness
The point is: don’t assume you won’t qualify for something. Cast a wide net.
## Where to Find College Scholarships
### Through School
#### 1. Your High School Guidance Office
If you’re a high school student, this is your best first stop. Your guidance counselors maintain lists of local and regional scholarships, some of which are only available to students from your specific school or district. That means less competition and better odds.
Stop by regularly throughout the year. New opportunities pop up in fall and spring, but some are added throughout the year and have rolling deadlines. Don’t wait until senior year to start asking.
#### 2. Your College’s Financial Aid Office
Once you’ve decided which school you’re going to attend, your next stop should be the financial aid office. Your school has scholarships you won’t find anywhere else, often tied to your specific major, background, or situation. Some are automatically considered when you apply for aid. Others require separate applications that you’ll need to seek out.
Check your school’s financial aid website and set up a meeting with a counselor. They know which scholarships are available and can help you figure out which ones you may qualify for. This is worth doing every year, not just as an incoming freshman. New scholarships become available often, and your eligibility can change.
**Pro tip:** When you’re accepted to colleges, each school will send you a Financial Aid Award Letter showing how much aid you’ll receive, including scholarships, grants, and loans. Comparing these letters side by side can make a big difference in how much you borrow overall.
### Online
#### 3. U.S. Department of Labor’s Free Scholarship Search Tool
The U.S. Department of Labor maintains a free scholarship database on its [CareerOneStop](https://www.careeronestop.org/toolkit/training/find-scholarships.aspx) site. It connects students with thousands of opportunities from a wide range of sources — and the best part is you don’t need to sign up for anything to use it.
The database includes fellowships and grants in addition to scholarships, but you can filter down to view just the type of aid you’re looking for. You can also filter by your current education level, location, field of study, and more. It’s straightforward, trusted, and completely free.
#### 4. Fastweb
[Fastweb.com](https://www.fastweb.com) is one of the most popular free scholarship search sites out there. To use it, you’ll create a profile with details about your background, academics, and interests. The more thorough you are, the better your matches will be.
Once your profile is set up, Fastweb matches you with scholarships you may qualify for and sends regular notifications as new ones are added. The types of scholarships available include merit-based awards, scholarships for high school vs. college students, state-specific opportunities, and even quirky “unusual” scholarships.
Fair warning: expect some marketing emails since the service is free. But the personalized matches are genuinely useful.
#### 5. Scholarships.com
Similar to Fastweb, [Scholarships.com](https://www.scholarships.com) offers a free, searchable database with thousands of opportunities. You’ll create a profile and answer questions about yourself to get matched with scholarships based on your academic record, background, intended major, and more
Categories span academic achievement, community involvement, career goals, heritage, religion, and more. It’s worth setting up a profile on both Fastweb and Scholarships.com. The overlap isn’t total, so you’ll likely find different opportunities on each.
#### 6. Cappex
[Cappex.com](https://www.cappex.com) combines college matching with scholarship searches. Answer questions about yourself and browse opportunities that fit your profile. It also includes a “lotteries” section for no-essay scholarships great for students who want to add some lower-effort entries to the mix.
#### 7. Niche
[Niche.com](https://www.niche.com) is more than quick-entry scholarships. Their platform helps you discover merit-based and need-based opportunities across a wide range of categories, from major-specific awards to scholarships from private educational trusts and organizations like Fulbright and ROTC programs. Create a free profile to get matched with personalized scholarships based on your background, interests, and academic path.
#### 8. College Board and FinAid.org
The [College Board’s scholarship search](https://bigfuture.collegeboard.org/scholarship-search) is another solid, well-known resource. If you’ve taken the SAT, you may already have an account. Their database is extensive and updated regularly.
[FinAid.org](https://www.finaid.org) is a long-standing resource for all things financial aid, including a scholarship search tool and guides to help you understand your options. It’s especially helpful for parents who want to get a fuller picture of the financial aid process.
#### 9. Scholly
[Scholly](https://myscholly.com) is a scholarship matching app that’s particularly popular with students looking for a mobile-friendly search experience. Unlike the free sites, Scholly charges a small monthly fee, but it’s known for surfacing scholarships that are harder to find elsewhere. Worth considering if you’re doing a serious search.
### Businesses
#### 10. Your Employer (or Your Parents’ Employers)
This one surprises a lot of students. Many companies — even smaller ones — offer scholarship or tuition assistance programs for employees and their families. If you have a part-time job, ask your HR department whether the company offers any scholarships and what the requirements are. Many programs are open to part-time workers, not just full-time employees.
Then ask your parents to do the same. Their employer’s HR or benefits department may offer scholarships for employees’ children that your family doesn’t know about. These programs often have smaller applicant pools — which means better odds for you.
#### 11. Corporate Scholarships
Major corporations understand that tomorrow’s workforce depends on accessible education today. Fortune 500 companies — from tech giants like Google and Microsoft to household names like Coca-Cola, McDonald’s, Walmart, Amazon, and Mercedes-Benz — sponsor scholarship programs for employees, their families, and sometimes the general public.
These corporate scholarships often target specific fields like computer science or engineering, support underrepresented groups, or help employees’ children afford college. Some are need-based, others are merit-based, and many offer substantial awards ranging from a few thousand dollars to full tuition coverage.
If you’re not sure where to start with this one, you can [browse Fortune 500 corporate scholarship opportunities here](https://www.collegescholarships.org/fortune500.htm). The site breaks down programs by company and provides details on eligibility requirements and award amounts.
These require more effort than a simple sweepstakes entry, but the payoff can be significant.
### Organizations
#### 12. In Your Community
This one may not be as obvious, but local organizations are one of the best-kept secrets in scholarship hunting. Rotary clubs, Kiwanis, chambers of commerce, labor unions, churches, and community foundations often have small scholarships that don’t get much attention — and that’s exactly why you should apply for them.
They’re usually modest amounts ($500–$2,000), but they add up. And because fewer students apply, your chances of winning are significantly better than with big national scholarships. Importantly, these scholarships rarely show up in national databases — so you’ll need to do a little legwork.
Ask around. Check bulletin boards at your library. Search your town’s website. Call your local community foundation. You might be surprised what’s out there.
#### 13. Professional Associations in Your Field
Planning to study nursing? Engineering? Teaching? Business? Professional associations in almost every field offer scholarships for students entering their industry. These are often less competitive than general scholarships because only students pursuing that specific field apply.
A quick search for “\[your major\] scholarship professional association” is a good starting point.
### Lenders
#### 14. Scholarships from Student Loan Companies
Some student loan companies offer scholarships and sweepstakes to help students reduce borrowing costs. You don’t need to be a borrower to enter, and many have simple entry requirements with no essay or minimum GPA required.
Abe® runs regular scholarship sweepstakes with straightforward entry forms. [Check out our Sweepstakes page here](/sweepstakes).
Other student loan companies run similar programs, so it’s worth checking any lender’s website you’re already researching to see if they offer scholarships or sweepstakes.
## A Few Tips for Your Scholarship Search
### Apply a Lot…And Keep Applying
One or two applications won’t cut it. Students who win meaningful scholarship money usually apply to 20, 30, sometimes 50+ opportunities. Treat it like a part-time job, especially in your senior year of high school and during college. Set a weekly goal for how many applications you’ll submit.
### Small Scholarships Matter More Than You Think
Don’t skip the $500 ones. Four of those equal $2,000 you don’t have to borrow — and over four years, that adds up to real money. Smaller scholarships often have fewer applicants, which means your odds are genuinely better.
### Local College Scholarships Usually Beat National
Your odds of winning a $1,000 scholarship from a local organization are often far better than your odds with a $10,000 national program that gets 50,000 applications. Don’t overlook what’s in your own backyard.
### Watch Out for Scams
Legitimate scholarships never ask you to pay an application fee. If someone wants money up front to “guarantee” your scholarship or to access a list of opportunities, walk away. Free databases like the ones listed above are all you need.
### Keep a Simple Tracking Spreadsheet
As you apply to more scholarships, it’s easy to lose track of deadlines, requirements, and what you’ve already submitted. A simple spreadsheet with the scholarship name, amount, deadline, requirements, and status can save you a lot of stress.
## Stay Connected with Abe
We regularly run scholarship sweepstakes for students and parents. Entering is simple with no essays or hoops to jump through. [Check out our Sweepstakes page here](/sweepstakes).
Once you’ve explored all your financial aid options — scholarships, federal grants, and federal student loans — Abe is here with plain, honest private student loans when you need them.
**Categories:** Blog, Scholarships
---
### [What to Know About Applying for Private Student Loans](https://www.abestudentloans.com/blog/what-to-know-about-applying-for-private-student-loans/)
**Published:** May 22, 2026
**Author:** abelending
**Excerpt:**
Private student loans can help cover the gap between financial aid and the full cost of attendance for college. But comparing lenders, understanding rates, and meeting school billing deadlines takes preparation. This straightforward guide from Abe® covers how to apply for a private student loan, how long the process typically takes, and best practices to help you borrow with confidence.
**Content:**
## How to Apply for a Private Student Loan: An Overview
Specific steps and requirements vary by lender, but the overall application process is similar. Below is a simple breakdown of how to apply for a private student loan.
### Determine How Much You Need to Borrow
Add up any federal student loans, scholarships, grants, savings, and work-study funds you expect to receive, then subtract that total from your school’s cost of attendance. Make sure when you calculate the total cost of attendance, you take into account things like tuition, room & board, meal plans, books, lab fees, and any other fees the school charges. The difference is the amount a private student loan would need to cover.
### Compare Your Options
When comparing private student loans, evaluate these key factors:
#### Interest Rate Type
Fixed rates stay the same for the life of the loan and generally range from about 3% to more than 17%. Variable rates can change over time based on market conditions and typically start between 4% and 18%.
#### Repayment Terms
Consider the length of the repayment period and what your estimated monthly payment would be. Common repayment terms range from 5 to 20 years. A shorter term usually means a higher monthly payment with less interest paid over the life of the loan, while a longer term lowers the monthly payment and increases the total cost of borrowing.
#### Fees
Check for application, origination, or late payment fees. Many lenders don’t charge application or origination fees, while others may charge them as a flat amount or as a percentage of the loan that’s added to your balance. Late payment fees are typically a small percentage of the past-due amount or a flat dollar charge.
#### Borrower Benefits
Look at features like rate discounts, graduation rewards, payment relief options, and flexibility during repayment. Rate discounts, such as those for auto pay or consistent on-time payments, can reduce the interest you pay over the life of the loan. Payment relief and flexibility features, like forbearance, deferment, and grace period extensions, can help if your situation changes after you start repayment.
Choosing the right lender and rate type can lead to substantial savings, so make sure to research your options thoroughly. Abe offers a choice of five payment terms, six different payment relief options, a 2% graduation reward, and doesn’t charge application, origination, or other fees.
### Gather All Your Documents
Once you know how much you need to borrow and you’ve picked your lender, gather the information you’ll need for the application. Always check the lender’s requirements, but many applications ask for:
- Your birth date and Social Security number (and your cosigner’s, if applicable)
- Your mailing address
- Your email and phone number
- Your school’s name
- Your grade level, and expected graduation date
- Your income (and your cosigner’s, if applicable)
- Your requested loan amount
### Submit Your Application
When you’re ready, complete the application on the lender’s website. One key difference between private student loans and federal loans is that private lenders use credit to evaluate the application. Submitting a full application usually triggers a hard credit inquiry. To help you compare options before that step, many loans, like Abe, offer a [prequalification tool](https://www.abe.psl.sparrowfi.com/prequalification/program-routing?utm_source=defaultsource&utm_medium=defaultmedium&utm_campaign=defaultcampaign&utm_term=defaultterm&utm_content=defaultcontent&_gl=1*jwi4ul*_gcl_au*MjA0MTQ5OTczNy4xNzcyNTYwNjY1*_ga*MjA0NTgzNDA0NS4xNzY0NzY5MjY1*_ga_RQQGJ5585R*czE3NzgwMTQ0NzUkbzEzNyRnMSR0MTc3ODAxNDQ3NyRqNTgkbDAkaDA.) that uses a soft credit check and shows estimated rates without affecting your credit score.2
After you submit your application, keep an eye out for important communications from your lender. Some applicants may need to provide additional documentation. If you’re approved, you will have a limited time (often 30 calendar days) to accept the loan terms and provide any supporting documentation, so it helps to apply early enough to meet your school’s billing deadline.
Tip: If you want to review your credit information ahead of time, you can access your credit reports for free at [AnnualCreditReport.com](http://annualcreditreport.com). Seeing what’s on your report can help you understand how credit may impact your eligibility and terms when applying for a private student loan.
## How Long Does It Take To Get A Student Loan?
The private student loan process can span several weeks from application to disbursement, so starting early helps you avoid delays and gives your school enough time to certify the loan.
### When Should You Apply For Private Student Loans?
Unlike federal aid, private student loans typically don’t have a universal application deadline. Plan to apply at least 6 to 8 weeks before your next term’s bill is due to allow time for review, school certification, and disbursement.
### How Long Do Private Student Loans Take to Process?
Private student loans typically take between one and eight weeks from application to school disbursement. In some cases, it may be faster.
Timing depends on the credit review, how much documentation is required, and how quickly your school responds to the certification request from the lender. You can help keep things moving by submitting complete information and responding immediately to any requests from the lender.
## Tips for Applying for Private Student Loans
A few best practices can help simplify the private student loan application process and potentially save you money over the life of your loan.
### Start Early
As soon as you know when you will enroll and which school you’re going to, begin estimating costs and reviewing your funding options. Before applying for a private student loan, it is usually best to exhaust grants, scholarships, and federal student loans.
Even if your payment due date is still months away, giving yourself more time can help you avoid feeling rushed while you gather information and make decisions.
### Only Borrow What You Need
When a lender approves your application, the approved amount is typically a maximum based on the amount you request and the amount certified by your school. You don’t need to borrow the full amount you’re approved for. Borrowing less can reduce your total cost over time and may make repayment more manageable.
### Do Your Research Ahead of Time
Review the lender’s eligibility requirements and understand how the loan works before you apply. When comparing options, consider:
- Interest rate type (fixed or variable)
- Repayment options while in school
- Repayment term length and estimated monthly payment after school
- Grace periods and deferment options
- Total cost of borrowing over time
- Any fees, if applicable
- Whether you have access to a creditworthy cosigner
An Abe student loan includes a [prequalification ](https://www.abe.psl.sparrowfi.com/prequalification/program-routing?utm_source=defaultsource&utm_medium=defaultmedium&utm_campaign=defaultcampaign&utm_term=defaultterm&utm_content=defaultcontent&_gl=1*rklwv8*_gcl_au*MjA0MTQ5OTczNy4xNzcyNTYwNjY1*_ga*MjA0NTgzNDA0NS4xNzY0NzY5MjY1*_ga_RQQGJ5585R*czE3NzgwNzcyOTgkbzEzOCRnMCR0MTc3ODA3NzI5OCRqNjAkbDAkaDA.)[tool](https://www.abe.psl.sparrowfi.com/prequalification/program-routing?utm_source=defaultsource&utm_medium=defaultmedium&utm_campaign=defaultcampaign&utm_term=defaultterm&utm_content=defaultcontent&_gl=1*rklwv8*_gcl_au*MjA0MTQ5OTczNy4xNzcyNTYwNjY1*_ga*MjA0NTgzNDA0NS4xNzY0NzY5MjY1*_ga_RQQGJ5585R*czE3NzgwNzcyOTgkbzEzOCRnMCR0MTc3ODA3NzI5OCRqNjAkbDAkaDA.)2 that can help you see potential options and rates to simplify comparison without impacting your credit score.
### Explore Options to Save
As you compare options, look for ways to reduce the cost of borrowing. For example, Abe student loans offer [rate](https://www.abestudentloans.com/#rate-discounts)[ discounts](https://www.abestudentloans.com/#rate-discounts) such as an auto-pay discount of 0.25%18 and a good payment behavior benefit that can reduce your rate by 0.05% for each 6-month period of consecutive, on-time principal and interest payments, up to an additional 0.25% rate reduction.9 Abe also offers a graduation reward to borrowers—reducing their principal balance by 2% of their net disbursed loan amount upon request after graduation.8
### Boost Your Credit Score
Because private student loans involve a credit review, stronger credit can improve approval chances and may help you qualify for a lower rate.
If you already have a credit history, focus on paying bills on time and keeping credit card balances low. If you have limited or no credit history, maintaining one or two accounts in good standing over time can help establish a record of on-time payments.
Be mindful of timing. Opening new credit accounts or applying for other loans shortly before applying for a student loan can affect your credit score.
### Consider a Cosigner
If you have a limited credit history or a lower credit score, [applying with a creditworthy cosigner](https://www.abestudentloans.com/cosigners/) can improve approval chances and may help you qualify for a lower rate.
Most cosigners are parents or grandparents, but a guardian or another trusted adult may also be able to cosign if they meet the lender’s requirements.
If you are not a U.S. citizen, many lenders require a U.S. citizen cosigner, even if you have a credit history in another country.
## Start Your Private Student Loan Journey with Abe
Once you know what to expect, applying for private student loans can be quick and easy. With a plan, the right documents, and enough time before your school’s bill is due, you can move through the process with fewer surprises.
When you’re ready, explore Abe’s private student loan options for [undergraduate](https://www.abestudentloans.com/student-loans/undergraduate/) or [graduate](https://www.abestudentloans.com/student-loans/graduate/) school, and [find your rate](https://www.abe.psl.sparrowfi.com/prequalification/program-routing?utm_source=defaultsource&utm_medium=defaultmedium&utm_campaign=defaultcampaign&utm_term=defaultterm&utm_content=defaultcontent&_gl=1*rklwv8*_gcl_au*MjA0MTQ5OTczNy4xNzcyNTYwNjY1*_ga*MjA0NTgzNDA0NS4xNzY0NzY5MjY1*_ga_RQQGJ5585R*czE3NzgwNzcyOTgkbzEzOCRnMCR0MTc3ODA3NzI5OCRqNjAkbDAkaDA.) in minutes with no impact on your credit score.2
**Categories:** Blog
---
### [Do I Need a Cosigner for My Student Loan?](https://www.abestudentloans.com/blog/do-i-need-a-cosigner-for-my-student-loan/)
**Published:** May 22, 2026
**Author:** abelending
**Excerpt:**
Key Takeaways:
- Most federal student loans don't require a cosigner because they don't do credit checks
- Private loans do require credit checks
- Many undergrads will need a cosigner for their private student loans because they don't have an established credit history
- Even if you qualify for a private student loan by yourself, you may want to consider a cosigner to secure a better interest rate
**Content:**
Whether or not you need a cosigner for a student loan depends on several factors, including the type of loan, the borrower’s credit history, and the policies of the individual lender. This article provides an overview of what a cosigner is, how cosigner requirements vary by loan type, the advantages of applying with a cosigner, and key considerations for borrowers who choose to do so.
## What is a Cosigner?
A [cosigner](https://www.abestudentloans.com/cosigners/) is a creditworthy adult who signs onto a loan alongside the primary borrower, essentially sharing legal responsibility for the full amount owed. This practice, known as cosigning, is common in situations where the primary borrower has little to no credit history or a poor credit record.
Cosigners are most often a parent, grandparent, or legal guardian, though any qualifying family member or trusted adult may serve in this role. Most lenders require cosigners to be United States citizens with a demonstrated steady income and good credit history.
By cosigning a loan, the cosigner assumes joint liability for the debt. Should the primary borrower fail to make payments, the lender is legally entitled to pursue repayment from the cosigner.
## Cosigner Requirements by Loan Type
Your financial situation and the type of loan you’re taking out will ultimately determine whether or not you’ll need a cosigner.
### Federal Student Loans
Federal student loans generally don’t require a cosigner because they don’t involve a credit check during the application process. Because creditworthiness is not evaluated for most federal loans, students with no established credit history are not required to have an adult cosign on their behalf.
The only exception to this is Federal Direct PLUS Loans, which include:
- **Parent PLUS Loans** – Federal loans that eligible parents may take out to help finance their child’s undergraduate education.
- **Grad PLUS Loans** – Federal loans available to eligible graduate and professional students to help cover the cost of their education.
Unlike most federal loans, PLUS loans do require a credit check. Applicants must not have an adverse credit history to qualify. Those with credit issues may still be eligible for a PLUS loan, but are required to complete PLUS Credit Counseling. Borrowers can also file an appeal requesting further review or may obtain an endorser, which is the federal loan equivalent of a cosigner, to satisfy loan requirements.
### Private Student Loans
Unlike federal loans, the majority of private student loans do require a credit check to evaluate the applicant’s financial history and assess creditworthiness.
This credit evaluation is the primary reason many student borrowers need a cosigner. Students applying for loans directly out of high school often lack an established credit history and don’t have a stable income. Without a financial history, private lenders are generally unable to assess the risk of lending to a student borrower and will typically require a creditworthy adult to cosign the loan.
Even borrowers who do have some credit or financial history may still need a cosigner in the following circumstances:
- Borrowers with a low credit score
- Borrowers without a stable income
- Borrowers with a high debt-to-income ratio
#### When a Cosigner May Not Be Required for a Private Loan
Certain borrowers may qualify for a private student loan without a cosigner. For example, students who took time between high school and college to build credit, earn income, and establish a financial history may meet a lender’s creditworthiness standards independently.
Even student borrowers who can qualify without a creditworthy cosigner should consider adding a cosigner to help them achieve a lower interest rate.
### Loans for International Students
International students seeking private loans to finance undergraduate or graduate education in the United States will generally need a cosigner. Each lender will have their own set of criteria, but will typically require cosigners to be U.S. citizens or permanent residents.
## Benefits of Applying With a Cosigner
In addition to meeting lender requirements, there are several advantages to applying for a student loan with a cosigner, even for borrowers who may qualify independently.
### Higher Approval Rating
Applying with a creditworthy cosigner generally increases the likelihood of loan approval and may offer you a lower interest rate.
3 out of 4 approved Abe® applicants have a cosigner.
### Lower Interest Rates
A cosigner with a strong FICO score and steady income may help you secure a lower rate, since they share responsibility for the loan. A lower interest rate reduces both the monthly payment amount and the total cost of the loan over its repayment period.
### Credit Building
For borrowers with no credit history or a limited financial record, a student loan cosigned by a creditworthy adult provides an opportunity to establish or improve credit. Consistent, on-time payments over the life of the loan demonstrate creditworthiness to future lenders and can positively impact the borrower’s credit score. A strong credit history can improve a borrower’s eligibility and rate terms for future loans, including those for vehicles and real estate.
Since students are often in school for multiple years, establishing credit early during your college career can also result in lower interest rates when borrowing private loans for future years of college and graduate school.
## What to Know About Having a Cosigner
### Who Can Be a Cosigner
Many student borrowers turn to their parents when looking for a cosigner. If you can’t ask your parents for help, or if they aren’t qualified to be a cosigner, you have other options. Cosigners can be any guardian or family member, like a grandparent, aunt, or uncle. You could also ask a mentor or trustworthy adult in your life. It is important to note that the cosigner is legally responsible for the debt, and any missed or late payments can negatively affect the cosigner’s credit.
### Cosigner Release
Applying for a student loan with a cosigner doesn’t mean they have to stay on the loan forever. Many lenders offer a cosigner release option, which allows the cosigner to be removed from the loan after certain conditions are met — typically a defined period of on-time payments that demonstrates the primary borrower’s financial capability to manage the loan independently. The specific terms of cosigner release vary by lender; some may offer release after only 12 months of on-time payments, while others require the borrower to reach a midpoint in the repayment period.
## Learn More About Applying With a Cosigner
Cosigners are great options to consider when applying for your student loans, whether you need one to get approved or are just looking to secure a better interest rate. If you want to learn more about [applying for an Abe® student loan with a cosigner](https://www.abestudentloans.com/cosigners/), contact us or [find your rate online](http://abe.psl.sparrowfi.com/?utm_source=defaultsource&utm_medium=defaultmedium&utm_campaign=defaultcampaign&utm_term=defaultterm&utm_content=defaultcontent&_gl=1*xgi9ut*_gcl_au*NDUwMDAwNjEzLjE3NjI5MjgwNDg.*_ga*MTMzMTQ1MTI1MC4xNzYyOTI4MDQ5*_ga_RQQGJ5585R*czE3NjcxMjU1OTMkbzckZzEkdDE3NjcxMjcxODQkajYwJGwwJGgw).
**Categories:** Blog
---
### [How Many People Take Out Variable-Rate Student Loans?](https://www.abestudentloans.com/news/how-many-people-take-out-variable-rate-student-loans/)
**Published:** May 26, 2026
**Author:** abelending
**Categories:** News
---
### [Keeping Graduate Students’ Goals on Course: Abe Announces New Programs and Policies](https://www.abestudentloans.com/press-release/keeping-graduate-students-goals-on-course-abe-announces-new-programs-and-policies/)
**Published:** May 13, 2026
**Author:** abelending
**Excerpt:** Changes Include a New Scholarship Sweepstakes, Higher Aggregate Debt Limits, and Extended Repayment Deferment During Leaves of Absence
**Content:**
**BOSTON—May 9, 2026—**[AbeSM](https://www.abestudentloans.com/), which takes a transparent, built-for-real-life approach to private student lending, announces new policies and programs to help keep graduate students and their families on a steady path toward achieving their goals. The changes apply to students enrolled in or repaying Abe loans for master’s and doctoral degree programs, graduate-level certificate programs, or specialty programs such as medical and dental school.
New Abe policies and initiatives include a scholarship sweepstakes, higher maximum aggregate student loan debt limits, and loan repayment deferment options during authorized leaves of absence.
“Our goal is to help students pursue an education without interruption and with peace of mind,” said Steve Winnie, Chief Operating Officer, Monogram LLC, which created and administers Abe.
**Abe’s New Scholarship Option**
Abe will award a $5,000 scholarship‡ to the winner of Abe’s Graduate Scholarship Sweepstakes, which launched May 1, 2026 and closes July 31, 2026.
The no-essay sweepstakes is open to legal residents of the U.S./District of Columbia, age 18-plus, who are enrolled in a graduate-level program at an eligible institution, or the parents of these students. Entrants do not need an Abe student loan to be eligible and there are no GPA requirements.
To enter, please click this [link](https://www.abestudentloans.com/sweepstakes/graduate-college-scholarship-sweepstakes/?utm_source=defaultsource&utm_medium=defaultmedium&utm_campaign=defaultcampaign&utm_term=defaultterm&utm_content=defaultcontent). For the sweepstakes rules, click [here](https://www.abestudentloans.com/sweepstakes/graduate-college-scholarship-sweepstakes/official-rules/).
**New Debt Limits1**
Abe has raised its maximum aggregate student loan debt limits, which account for applicants’ total federal and private debt, to:
- $300,000 for applicants applying for undergraduate loan programs, up from $225,000
- $350,000 for applicants applying for graduate and graduate certificate loan programs, up from $225,000
- $500,000 for applicants applying for graduate medical and dental school loan programs, up from $350,000
The aggregate student loan debt limit for applicants applying for MBA, law or healthcare professional loan programs remains at $350,000.
**Extended Deferment Due to Leaves of Absence**
For the first time, Abe will recognize an extended authorized leave of absence, whether students are pursuing specialized opportunities, or a research project before finishing their studies.
The maximum extension for those with Abe medical school, dental school or healthcare professional loans is 12 months. The maximum for those with Abe graduate school, MBA or law school loans is six months. 2
**About Abe**
AbeSM student loans bring a plain, honest, “built-for-real-life” approach to private student lending. Abe covers up to the full cost of an education, and offers a unique combination of repayment plans, loan terms and deferment/forbearance options. Abe was created by Monogram LLC, the leader in data-driven private student lending products and programs. More information can be found at [abestudentloans.com](https://www.abestudentloans.com/), [Facebook](https://www.facebook.com/people/Abe-Student-Loans/61559721178214/) or [Instagram](https://www.instagram.com/abestudentloans/).
\###
‡ NO PURCHASE NECESSARY. Open to legal residents of the 50 U.S./D.C., age 18+ who are currently a student or parent of a student enrolled in a graduate program at an Eligible Institution. Void where prohibited. Ends 07/31/26. [Click for Official Rules](https://www.abestudentloans.com/sweepstakes/graduate-college-scholarship-sweepstakes/).
1. The minimum loan amount is **$1,000**, except for (a) student applicants who are permanent residents of Iowa in which case the minimum loan amount is **$1,001**, and (b) student applicants or cosigners who are permanent residents of Massachusetts in which case the minimum loan amount is **$6,001**. The maximum loan amount to cover in-school expenses for each academic year is determined by the school’s cost of attendance, minus other financial aid, as certified by the school. The requested loan amount cannot cause an individual applicant’s aggregate student loan debt (which includes federal and private student loans) to exceed **$300,000** per applicant applying for an undergraduate loan, **$350,000** per applicant applying for a graduate, graduate certificate, Healthcare Professionals, Law or MBA loan, or **$500,000** per applicant applying for a Medical or Dental loan.
2. For borrowers enrolled at an approved school and during an in-school period, grace period, or additional deferment period, if the school grants the borrower an authorized leave of absence (“LOA”), the loan will remain in the current deferment status. The school must certify that the LOA has been granted to the student or the LOA must be validated through the National Student Clearinghouse (“NSC”). Any such LOA may not exceed **12-months** in length for Abe Medical, Dental or Healthcare Professionals borrowers, or **six months** in length for all other Abe borrowers and shall not cause the loan to be in an in-school or grace period beyond the date that is sixty-six (66) months from the first disbursement date or an additional deferment period beyond forty-eight (48) months. If, after the aforementioned approved LOA, the student borrower is not re-enrolled in a graduate certificate or degree seeking program at an approved school, the repayment term will begin.
**Categories:** Press Release
---
### [The College Investor - Best Student Loan Rates for December 2, 2025: Low as 2.85%](https://www.abestudentloans.com/review/the-college-investor-best-student-loan-rates-for-december-2-2025-low-as-2-85/)
**Published:** December 2, 2025
**Author:** abelending
**Excerpt:** Student loan rates have dropped a bit going into the last month of the year. As of December 2, 2025, private student loan lenders are offering fixed rates as low as 2.85% APR and variable rates starting as low as 3.78% APR, depending on credit profile, degree program, and repayment term.
**Categories:** Review
---
### [The College Investor - Best Student Loan Rates for December 23, 2025: Low as 2.75%](https://www.abestudentloans.com/review/the-college-investor-best-student-loan-rates-for-december-23-2025-low-as-2-75/)
**Published:** December 23, 2025
**Author:** abelending
**Excerpt:** Student loan rates have dropped after the Fed rate cut last week. As of December 23, 2025, private student loan lenders are offering fixed rates as low as 2.75% APR and variable rates starting as low as 3.78% APR, depending on credit profile, degree program, and repayment term.
**Categories:** Review
---
### [Money - Student Loan Interest Rates for January 2026](https://www.abestudentloans.com/review/money-student-loan-interest-rates-for-january-2026/)
**Published:** December 29, 2025
**Author:** abelending
**Excerpt:** As the spring semester approaches, some college students are realizing they'll need additional funds to cover tuition bills, rent and meal plans. If that's you, make sure you're mapping out your expenses and comparing financing options carefully.
**Categories:** Review
---
### [Money - Best Private Student Loans of January 2026](https://www.abestudentloans.com/review/money-best-private-student-loans-of-january-2026/)
**Published:** December 29, 2025
**Author:** abelending
**Excerpt:** With the spring semester kicking off in the coming weeks, some students and parents are shopping around for private loans to help pay for tuition, fees, dorm expenses and meal plans. As with any financial product, it's critical you take the time to shop around.
**Categories:** Review
---
### [The College Investor - Abe Student Loans Review: Pros And Cons](https://www.abestudentloans.com/review/the-college-investor-abe-student-loans-review-pros-and-cons/)
**Published:** January 1, 2026
**Author:** abelending
**Excerpt:** In this review, we cover the key features, strengths, and weaknesses, to help you decide if Abe Student Loans is worth considering.
**Categories:** Review
---
### [WSJ Buyside - Best Graduate Student Loans of January 2026](https://www.abestudentloans.com/review/wsj-buyside-best-graduate-student-loans-of-january-2026/)
**Published:** January 2, 2026
**Author:** abelending
**Excerpt:** Federal Direct Unsubsidized Loans are often the cheapest borrowing option, followed by Direct Plus Loans and private graduate student loans
**Categories:** Review
---
### [Credible - Best Part-Time Student Loans in January 2026](https://www.abestudentloans.com/review/credible-best-part-time-student-loans-in-january-2026/)
**Published:** January 5, 2026
**Author:** abelending
**Excerpt:** Part-time students can typically still take out student loans, but your options are more limited if you’re below half-time enrollment.
**Categories:** Review
---
### [Credible - Best Private Student Loan Companies of 2026](https://www.abestudentloans.com/review/credible-best-private-student-loan-companies-of-2026/)
**Published:** January 8, 2026
**Author:** abelending
**Excerpt:** Get the flexibility you need for your loan payments. Compare top private lenders and secure the lower rates you're looking for.
**Categories:** Review
---
### [Nerdwallet - Best Private Student Loans of January 2026](https://www.abestudentloans.com/review/nerdwallet-best-private-student-loans-of-january-2026/)
**Published:** January 12, 2026
**Author:** abelending
**Excerpt:** The best private student loans offer competitive interest and annual percentage rates, have low origination, disbursement or prepayment fees (or none at all) and are offered by credible lenders.
Private student loans, which are offered by lenders instead of the government, can be a good option if federal loans, grants and other aid options don’t cover all of your education costs. However, unlike federal loans that have terms and conditions determined by the federal government, private student loans can have variable or fixed interest rates that depend on your credit score. They also lack the benefits of federal loans, such as valuable borrower protections, affordable income-driven repayment plans and forgiveness programs.
Before you apply for a private student loan, exhaust all federal student loans and other financial aid you can get. (Start by filling out the Free Application for Federal Student Aid, or FAFSA, to qualify for federal college loans and need-based grants and scholarships.)
If you still have remaining education costs, look for a private student loan. Compare your options below, where NerdWallet's editorial team show each private loan’s rating, interest rates and minimum credit score needed.
**Categories:** Review
---
### [Nerdwallet - Abe Review: Private Student Loans](https://www.abestudentloans.com/review/nerdwallet-abe-review-private-student-loans/)
**Published:** January 16, 2026
**Author:** abelending
**Excerpt:** Best for borrowers looking for a loan with flexible repayment plans and a long grace period.
**Categories:** Review
---
### [The College Investor - 10 Best Private Student Loan Lenders for College](https://www.abestudentloans.com/review/the-college-investor-10-best-private-student-loan-lenders-for-college-2/)
**Published:** January 22, 2026
**Author:** abelending
**Excerpt:** Private student loans can be a valuable tool when it comes to paying for college. They typically offer low interest rates for qualified borrowers, have flexible repayment terms, and some even offer extra features like career coaching and more.
**Categories:** Review
---
### [Forbes - Best Student Loan Interest Rates](https://www.abestudentloans.com/review/forbes-best-student-loan-interest-rates/)
**Published:** January 22, 2026
**Author:** abelending
**Excerpt:** Getting a low rate on a student loan can save you thousands of dollars over the course of your loan term.
**Categories:** Review
---
### [The College Investor - What Parents Should Know When Comparing Student Loans](https://www.abestudentloans.com/uncategorized/the-college-investor-what-parents-should-know-when-comparing-student-loans/)
**Published:** July 16, 2025
**Author:** abelending
**Excerpt:** For many parents, shopping for a student loan becomes a balancing act: finding the lowest rate while making sure the loan terms don’t create problems down the road.
**Categories:** Uncategorized
---
### [Credible - What Is the Monthly Payment on a $30,000 Student Loan?](https://www.abestudentloans.com/uncategorized/credible-what-is-the-monthly-payment-on-a-30000-student-loan/)
**Published:** October 21, 2025
**Author:** abelending
**Excerpt:** Your monthly payment will vary based on the type of loan you have, your interest rate, repayment term, and other factors.
**Categories:** Uncategorized
---
### [U.S. News - A New Federal Law Means You Might Need Private Student Loans Next Year. Get Prepared Now.](https://www.abestudentloans.com/uncategorized/u-s-news-a-new-federal-law-means-you-might-need-private-student-loans-next-year-get-prepared-now/)
**Published:** October 16, 2025
**Author:** abelending
**Excerpt:** Future college borrowers can take steps now to get approved for loans and potentially save money.
**Categories:** Uncategorized
---
### [Money.com - Student Loan Interest Rates for October 2025](https://www.abestudentloans.com/uncategorized/money-com-student-loan-interest-rates-for-october-2025/)
**Published:** October 2, 2025
**Author:** abelending
**Excerpt:** To help you make smart borrowing decisions, here’s Money’s guide to everything you need to know about student loan interest rates right now.
**Categories:** Uncategorized
---
### [Even More to Celebrate: Abe Announces $7,500 Home for the Holidays Scholarship Sweepstakes](https://www.abestudentloans.com/press-release/even-more-to-celebrate-abe-announces-7500-home-for-the-holidays-scholarship-sweepstakes/)
**Published:** November 4, 2025
**Author:** abelending
**Excerpt:** Five Lucky Undergraduates, Graduate Students, or Parents to Win $1,500 Scholarships
**Content:**
BOSTON, Nov. 4, 2025 /PRNewswire/ — When families are on a strict budget to pay for college or graduate school, an extra $1,500 can provide a welcome financial boost, especially during the holidays.
Now several lucky students or parents of these students will enjoy that additional lift as holiday celebrations approach. [AbeSM](https://www.abestudentloans.com/), an innovative private student lending program, has launched the Abe Home for the Holidays Scholarship Sweepstakes and is giving away $7,500. Five winners will each receive $1,500 to put toward undergraduate or graduate school expenses, travel or even gifts. For a chance to win, students and parents should enter the free sweepstakes by December 1, 2025 at [abestudentloans.com/scholarship-holiday2025](https://www.abestudentloans.com/scholarship-holiday2025).\* Winners will be selected on or around December 3.
## Five winners will each receive $1,500 to put toward undergraduate or graduate school expenses, travel or even gifts.
> “We’re excited that this new scholarship sweepstakes will make recipients’ holidays even happier,” said Steve Winnie, Chief Operating Officer, Monogram LLC, which administers Abe student loans. “Whether winners use the money to travel home for winter break or to upgrade their computers, we are pleased to reward their hard work and commitment to education.”
The Abe Home for the Holidays Scholarship Sweepstakes is open to legal residents of the U.S./District of Columbia, age 18-plus, who are enrolled in an undergraduate or graduate program in an eligible U.S. institution, or parents of these students. Entrants do not need to have an Abe student loan to be considered. To review the full sweepstakes rules, visit [abestudentloans.com/scholarship-holiday2025-official-rules](https://www.abestudentloans.com/scholarship-holiday2025-official-rules).
The Home for the Holidays Scholarship Sweepstakes is the latest innovation from Abe, which brings a different kind of program to the private student loan marketplace—one that stands out for its borrower-supportive features, extending throughout repayment, and especially when “life happens”. In addition to low rates and a “no fees … ever” approach, these features include:
- Flexible repayment options to keep borrowers in control
- Longer grace periods than other lenders
- Forbearance in case of job loss or illness
- In-school default protection
- 2% loan principal balance reduction at graduation
More information about these loans for undergraduate and graduate students, as well as those enrolled in graduate certificate programs and MBA, law, medical, dental or healthcare professional degree programs, is available at [abestudentloans.com](https://www.abestudentloans.com/).
**About Abe**
AbeSM student loans are focused on creating more supportive borrower experiences that better meet the needs of today’s college students. In addition to clear, transparent information, Abe offers a unique combination of repayment plans, loan terms and deferment/forbearance options. Abe was created by Monogram LLC, the leader in data-driven private student lending products and programs. The Monogram team has originated more than $23 billion in private student loans and assisted 1.5 million borrowers at thousands of schools. More information is available at [abestudentloans.com](https://www.abestudentloans.com/), [Facebook](https://www.facebook.com/people/Abe-Student-Loans/61559721178214/) or [Instagram](https://www.instagram.com/abestudentloans/).
\*NO PURCHASE OR PAYMENT NECESSARY. See [abestudentloans.com/scholarship-holiday2025-official-rules](https://www.abestudentloans.com/scholarship-holiday2025-official-rules) for Official Rules and complete details. Void where prohibited.
Contact Dawn Ringel
617-285-0652;
SOURCE Monogram LLC
**Categories:** Press Release
---
### [Abe Student Loans Celebrates First Birthday by Giving Families a Present--$20,000 in Abe Scholarships](https://www.abestudentloans.com/press-release/abe-student-loans-celebrates-first-birthday-by-giving-families-a-present-20000-in-abe-scholarships/)
**Published:** June 5, 2025
**Author:** abelending
**Excerpt:** Abe to Offer 15 $1,000 Scholarships and One $5,000 Grand Prize Scholarship; Sweepstakes is Now Open
**Content:**
BOSTON, June 5, 2025 /PRNewswire/ — [Abe Student Loans](https://www.abestudentloans.com/), an innovative private student lending program, is celebrating its first birthday by giving students and their families a present—$20,000 in new scholarships.
Undergraduates and their parents are encouraged to enter the [Abe Birthday Scholarship Sweepstakes](http://abestudentloans.com/birthday-scholarship) for a chance to win one of 15 $1,000 awards or the $5,000 grand prize. The call for entries is open at [abestudentloans.com/birthday-scholarship](https://www.abestudentloans.com/birthday-scholarship).
The “no essay” sweepstakes is for legal residents of all 50 states and the District of Columbia who are 18 or older. These include students or parents of students enrolled in an eligible institution, per the [contest rules](https://www.abestudentloans.com/birthday-scholarship-official-rules/).\*
Abe will draw one winning entry per week beginning the week of June 8, 2025 and ending the week of September 14. After the final week, Abe will also draw the $5,000 winner.
Individuals do not need to apply for an Abe Student Loan to participate. For the best chance of winning, they should enter every week.
> *“Since we introduced Abe last year, it’s been a pleasure to partner with students who are committed to advancing through education. Now we’re delighted to open up even more college financing opportunities,” said Steve Winnie, Chief Operating Officer, Monogram LLC, a leading provider of private student lending programs*.
Private student loans fill families’ college financing gaps after accounting for all federal student loans, scholarships, grants and work-study programs. Monogram launched Abe to bring a different kind of program to the private student loan marketplace—one that not only offers transparency and clarity, but stands out for its borrower-supportive features, extending throughout repayment, and especially when “life happens”.
In addition to low rates and a “no fees….ever” approach, these features include:
- Flexible repayment options to keep borrowers in control
- Longer grace periods than other lenders
- Forbearance in case of job loss or illness
- In-school default protection
- 2% loan principal balance reduction at graduation
- Rate reductions for every six months of on-time payments (up to 0.25%)
More information about these loans for undergraduate and graduate students, as well as those enrolled in graduate certificate programs and MBA, law, medical, dental or healthcare degree programs, is available at [abestudentloans.com/birthday-scholarship](https://www.abestudentloans.com/birthday-scholarship).
**About Abe**
AbeSM provides “plain, honest student loans” focused on creating more supportive borrower experiences that better meet the needs of today’s college students. In addition to clear, transparent information, Abe offers a unique combination of repayment plans, loan terms and deferment/forbearance options. Abe was created by Monogram LLC, the leader in data-driven private student lending products and programs. For more than 30 years, the Monogram team has originated and managed more than $30 billion in private student loan assets. More information is available at [abestudentloans.com](https://www.abestudentloans.com/), [Facebook](https://www.facebook.com/people/Abe-Student-Loans/61559721178214/) or [Instagram](https://www.instagram.com/abestudentloans/).
\*NO PURCHASE NECESSARY. See [website](https://www.abestudentloans.com/birthday-scholarship/) for Official Rules and complete details. Void where prohibited.
Contact Dawn Ringel
617-285-0652;
SOURCE Monogram LLC
**Categories:** Press Release
---
### [Introducing Abe, a Plain, Honest and Borrower-Supportive Student Loan Product](https://www.abestudentloans.com/press-release/introducing-abe-a-plain-honest-and-borrower-supportive-student-loan-product/)
**Published:** June 3, 2024
**Author:** abelending
**Excerpt:** Private student loan provider uses transparency and product features to deliver an honest and simple student loan experience
**Content:**
BOSTON, June 3, 2024 /PRNewswire/ — Just in time for the busy private student loan application season, a new product called AbeSM launches today that seeks to help students get more comfortable, or at least less uncomfortable, with borrowing thousands of dollars to finance an investment in their higher education.
> *“Abe began with us being honest with ourselves about how customers really feel about borrowing money for college and, perhaps more importantly, their genuine concerns about paying it back,” said Seth Gelber, President and Chief Executive Officer at Monogram LLC, creators of Abe. “Students’ and their families’ heads are spinning with everything that’s been going on with federal loans. On top of that, they’re often confused about where private student loans fit into the financing landscape.”*
## Abe brings transparency and clarity to the private student loan process along with distinct product features.
“All the private student lenders make it relatively easy for students to borrow money,” Gelber pointed out, “while Abe uses information and loan features to take the stress out of the hard part – repaying the loan. That’s where we’re really focused on creating a better, more supportive borrower experience.”
Abe brings transparency and clarity to the private student loan process along with distinct product features that better support students for as long as they have their loans. These borrower-supportive product features include:
- In-school default protection
- Rate reductions for every six months of on-time payments (up to 0.25%)
- Expanded grace period and deferment options
- Forbearance in case of job loss or illness
- A broader range of loan terms (5, 7, 10, 15 & 20 years)
- 2% loan principal balance reduction at graduation
Abe also acknowledges and supports the changing needs and more diverse lives of today’s college students. For example, in addition to traditional undergraduate and graduate school degrees, Abe loans can be used to pay for half-time and less than half-time enrollment as well as post-graduate certificate programs – an increasingly popular way for students to bolster their skills in their chosen field and give themselves a competitive edge in the job market. Abe also welcomes international and DACA (Deferred Action for Childhood Arrivals) students provided they have a U.S. or permanent alien resident cosigner.
**About Abe**
AbeSM provides ‘plain, honest student loans’ focused on creating more supportive borrower experiences that better meet the needs of today’s college students. In addition to clear, transparent information, Abe offers a unique combination of repayment plans, loan terms and deferment/forbearance options for U.S. and international students, candidates for undergraduate and graduate degrees and post-college certificates, and individuals taking different routes to complete their studies. Abe was created by Monogram LLC, the leader in data-driven private student lending products and programs. For more than 30 years, the Monogram team has originated and managed more than $30 billion in private student loan assets. More information is available at [monogramllc.com](https://www.monogramllc.com/).
Contact: Dawn Ringel, Incenter Marketing
or 617-285-0652
SOURCE Monogram
**Categories:** Press Release
---
## Pages
### [Home](https://www.abestudentloans.com/)
**Published:** March 13, 2024
**Author:** abelending
**Content:**
**Enter for a chance to win $1,500† in Abe’s Undergraduate Scholarship Sweepstakes!**
# Plain, honest student loans.
- Available for Undergrad, Grad, and Grad Specialty programs
- Up to 100% of college expenses covered[1](#f1)
- No application fees, processing fees, or late fees
- Find your rate in minutes[2](#f2) with no impact on your credit score
- Four repayment options, five loan terms[3](#f3)
- [In-School Default Protection](#options-terms)[4 ](#f4)saves you from default if you fall short while making payments in-school
[Find My Rate](http://abe.psl.sparrowfi.com)
## Our rates are low.
But there’s more to it.
Opting for a fixed rate means the rate won’t change for the life of your loan.[5](#f5) Remember, your actual rate will depend on your, or your cosigner’s, if applicable, credit. Applying with a creditworthy cosigner may result in a lower interest rate.
Undergraduate Fixed Rates\*
Abe.
2.08% – 16.58% APR6,7
Earnest
2.19% – 16.49% APR
College Ave
2.19% – 17.99% APR
Sallie Mae
2.39% – 17.49% APR
SoFi
2.45% – 15.99% APR
*\*Comparisons based on competitors’ websites (as of 7/27/26).
Lowest Annual Percentage Rates include a 0.25% discount when auto pay is elected.18*




### No Fees
No application fees, origination fees, late payment fees, forbearance fees, or fees to pay by debit card.
### 2% Grad Reward8
Upon request after graduating, reduce your principal balance by 2% of your net disbursed loan amount.
### Fast-Track Your Rate Reduction
For every six months of on-time principal and interest payments, Abe® lowers your rate by 0.05% — for a total reduction of up to 0.25%.[9](#f9) Unlike other providers that require you to make years of payments first,\* Abe lets you start to lower your rate (and build a good credit history) much sooner.
g
### 5, 7, 10, 15, or 20 Years3
The term, or duration, impacts both the cost of a loan and your monthly payment amount. The longer the loan, the more interest you’ll pay but the lower your monthly cost will be. Abe has five terms — giving you more options for weighing the length/cost of your loan against a monthly payment you’re comfortable making.
### 6 Payment Relief Options
Abe is there for you with six different payment relief options that let you defer payments according to your education goals and timeline. For example, you may enroll in a medical internship or residency10 or it may take longer for you to get on your financial feet after you graduate. You can also defer payments if you lose your job11 or suffer a serious illness.12
### Early Cosigner Release13
Abe recognizes the shared commitment you and your cosigner make when taking out your student loan. That’s why, after just 12 months of on-time principal and interest payments, you can apply to release your cosigner – allowing you to take sole responsibility for the loan moving forward.
### Stress Less, Save More Time With the Returning Borrower Advantage14
[Reapply Now](http://abe.psl.sparrowfi.com)
When you come back for another Abe student loan, you not only have a higher chance of approval — you likely won’t need to resubmit income documentation again. Less paperwork, less waiting. Just a straightforward path to the money you need.
\*Comparisons based on competitors’ websites as of 7/27/26.
## Find the loan that fits your goals.
No matter where you are headed on your education journey, Abe can help you get there.

### Undergraduate
For undergraduate students enrolled in a bachelor’s or associate’s degree program.
**Learn More**

### Graduate
For graduate students enrolled in a degree or certificate program.
**Learn More**

### Law
For graduate students enrolled in a law degree program.
**Learn More**

### MBA
For graduate students enrolled in an MBA degree program.
**Learn More**

### Medical
For graduate students enrolled in a doctoral degree program: Doctor of Medicine (MD), Osteopathic Medicine (DO), Veterinary Medicine (DVM, VMD), or Podiatric Medicine (PM).
**Learn More**

### Dental
For graduate students enrolled in a dentistry degree program (Pediatric Dentistry, Periodontics, Oral Surgeon etc.).
**Learn More**

### Healthcare Professionals
For graduate students enrolled in a nursing, pharmacy, or allied health professional degree program (e.g., Dietitians, OT, Speech Pathologist, Audiologist, Dental Hygienist etc.).
**Learn More**
## Why Borrowers Are Choosing Abe
The Abe student loan experience, told by the people who lived it.
### "Abe was able to get me a great rate on my loan.
The loan process was smooth and I am very happy I was able to work with them.”
Gavin, Verified Borrower

### "I've dealt with a few different loans, but Abe is on a different level.
The entire application process was incredibly smooth. I was able to see my rates with a soft credit pull, which gave me peace of mind right from the start. Customer service is amazing.”
Joe, Verified Borrower

### "Easy process,
fast disbursement.”
Paola, Verified Borrower

### "Abe really helped me when I needed it most.
I didn’t think I would be able to afford college, but I applied for a loan and the process was smooth and manageable.”
Anonymous, Verified Borrower

### "The loan experience was very easy.
I feel the rate was fair. It allowed Isabelle to attend the school of her choice.“
Sean, Verified Borrower

### "Very Helpful
First time navigating school loans for my daughter, and they were very helpful when it came to choosing the right loan for her.“
Jennette, Verified Borrower

## How Abe stacks up.\*
### Zero Fees
### Grace Period15,16
### Repayment Options3
### Repayment Terms3
### Past Due Balances17
### On-Time Discount9
### Graduate Loans
### Graduate Certificate Loans
### Grad Reward8
### In-School Default Protection4
### Abe.
####
Up to 12 Months^
4
5, 7, 10, 15, & 20 Years
18 Months
####
####
####
####
####
### Zero Fees
### Grace Period15,16
### Repayment Options3
### Repayment Terms3
### Past Due Balances17
### On-Time Discount9
### Graduate Loans
### Graduate Certificate Loans
### Grad Reward8
### In-School Default Protection4
#### Sallie Mae
####
6 Months
3
10 to 15 Years
12 Months
####
####
####
####
####
### Zero Fees
### Grace Period15,16
### Repayment Options3
### Repayment Terms3
### Past Due Balances17
### On-Time Discount9
### Graduate Loans
### Graduate Certificate Loans
### Grad Reward8
### In-School Default Protection4
#### SoFi
####
6 Months
4
5, 7, 10, 15 & 20 Years
12 Months
####
####
####
####
####
### Zero Fees
### Grace Period15,16
### Repayment Options3
### Repayment Terms3
### Past Due Balances17
### On-Time Discount9
### Graduate Loans
### Graduate Certificate Loans
### Grad Reward8
### In-School Default Protection4
#### CollegeAve
####
6 Months
4
5, 8, 10, & 15 Years
12 Months
####
####
####
####
####
### Zero Fees
### Grace Period15,16
### Repayment Options3
### Repayment Terms3
### Past Due Balances17
### On-Time Discount9
### Graduate Loans
### Graduate Certificate Loans
### Grad Reward8
### In-School Default Protection4
#### Earnest
####
9 Months
4
5, 7, 10, 12, & 15 Years
12 Months
####
####
####
####
####
\*Comparisons based on competitors’ websites (as of 7/27/26).
^6 months grace guaranteed + possible 6 months grace extension.
- [Rate Discounts](#rate-discounts)
- [Student Loans](#degree-programs)
- [International](#international)
- [Options & Terms](#options-terms)
- [Payment Relief](#payment-relief)
Rate Discounts
Rate Discounts
## Lowering your rate. &
### Reduce your rate by up to 0.50% by building a good payment history.
Abe allows you to reduce your rate by 0.25% by electing auto pay18, even while you are enrolled in school, and up to an additional 0.25% interest rate reduction for making on-time principal and interest payments9 during the repayment term.
[Find My Rate](http://abe.psl.sparrowfi.com)
Student Loans
Student Loans
## [Student loans custom-fit to your degree. &](/student-loans)
### [Undergraduate Student Loans $](https://www.abestudentloans.com/student-loans/undergraduate)
An Abe student loan can be used to earn an associate, B.A., or B.S. degree at approved private and public universities and colleges. The aggregate loan limit1 for undergraduate students is $300,000.
### Post-Bachelor Graduate Certificates
Post-bachelor Graduate Certificate students can use an Abe loan to cover the costs associated with specialized certificates in their field and start their careers at a higher level. The aggregate loan limit1 for Graduate Certificate students is $350,000.
### [Graduate Student Loans $]()
Whether you're earning a master's, doctoral, or professional degree, Abe's graduate student loans offer the same benefits as our undergraduate loans.
Advanced degrees often require more funding. Abe's aggregate loan limit1 is $350,000 for Graduate, Law, MBA, and Healthcare Professional programs, and $500,000 for Medical and Dental programs.
### Less Than Half-Time Students
An Abe student loan can help students who just need a few more credits to finish their degree, including summer and Jan Plan courses.
International
International
## We welcome the world.19
### U.S. Citizens
### Permanent Residents
### DACA Recipients with a U.S. Cosigner
### International Students with a U.S. Cosigner
Options & Terms
Options & Terms
## More repayment options, more power to the individual.
Determining the right Abe loan for you means figuring out your ideal total loan cost vs. monthly payment amount.
Whether you can start repaying while in school or if you need to defer until after graduation, the rule of thumb is the shorter the loan term, the less interest you’ll pay and the lower the total cost of your loan.
Abe has five different loan terms: 5, 7, 10, 15, or 20 years.[3](#f3) Use the configurator in our online application to see how adjusting the length of your loan changes the monthly payment, and then choose the shortest term with a payment amount you’re comfortable making.
[Find My Rate](http://abe.psl.sparrowfi.com)
### In-School Payments[3](#f3)
- Making principal and interest payments lowers the cost of the loan the most
- Interest only payments reduce the long-term cost
- Low, flat payments steadily chip away at your balance
### Deferred Payments
- Wait until you graduate to start repayment20
### Five Different Loan Terms:
- 5, 7, 10, 15, or 20 years[3](#f3)
### In-School Default Protection4 saves you from default.
If you elect to make interest only or flat payments while in-school but fall short, In-School Default Protection will save you from default by automatically switching you to a deferred payment program. Abe also features an extra year of in-school deferment20 – up to 60 months (5 years) in case it takes a little longer to get your degree.
Payment Relief
Payment Relief
## Life happens. That's okay.
### Most students don't worry about borrowing money. They worry about paying it back.
### What if you need more time before starting repayment? What if life throws you a curveball?
### 6 months of grace and then 6 more.
Once you graduate, you have to look for a job. You may have to move. Buy a car. If you need 6 months before starting repayment, you got it.15 Then if you need 6 more months, that’s fine, too.16
### Health and family first.
If you end up out of work due to illness or go on unpaid FMLA leave, Abe provides up to 12 months of medical forbearance.12
### Re-enrollment, medical internships, and residencies.
If you re-enroll in school, or enter a medical internship or residency, we offer deferment options.10
### Extended payment relief.
If you have gone through a reduced payment program and still need relief to get back on your feet, you may be eligible for a term extension of 60 months (5 years), which will lower your monthly payments.21
### A safety net just in case.
A lot can happen over the life of a loan. You may lose your job, or suffer from a financial hardship,11 or be impacted by a natural disaster.22 Abe is there for you with opportunities for payment relief.
### Past-due balances.
Falling behind and accumulating a past-due school balance can happen, particularly during financial emergencies or unexpected circumstances. If this occurs, an Abe loan can be used to cover the outstanding balance within 18 months of the academic period end date.17
## Enter for a chance to win $1,500† for undergraduate college expenses!
### Every month through December 31, 2026, Abe is helping undergraduate students and their families cover college costs.
[Enter Now](https://www.abestudentloans.com/resources/scholarships/undergraduate-college-scholarship-sweepstakes/)
## A Plain, Honest Guide to Private Student Loans
Abe believes that if you give people the honest, straightforward information they need to make good decisions, they will. That’s why we created the Plain, Honest Guide to Private Student Loans and invite you to download it here.
[Download Our Guide](/resources/#student-loan-guide)

---
### [Healthcare Professionals](https://www.abestudentloans.com/student-loans/graduate/healthcare-professionals/)
**Published:** May 27, 2025
**Author:** abelending
**Content:**
# Healthcare Professionals Student Loans
No application fees, processing fees, or late fees
Four repayment options, five loan terms3
Available to students enrolled full time, part-time, or less than half time
Up to 100% of all school costs associated with healthcare professions1
Find your rate in minutes2 with no impact to your credit score
[Find My Rate](http://abe.psl.sparrowfi.com)
## Caring for others begins with investing in yourself.
Whether you’re becoming a dietitian, occupational therapist, speech pathologist, audiologist, or dental hygienist, an Abe® Healthcare Professionals student loan can help you get there. Applying with a cosigner may help you get the best possible rate.
### Fixed Rates
### 2.08%
### to 15.58% APR[6](#f6),[7](#f7)
### Variable Rates
### 3.50%
### to 15.21% APR[6](#f6),[7](#f7)
*Lowest APRs (Annual Percentage Rates) include a 0.25% discount when auto pay is elected.18*
## Apply in minutes with 3 easy steps.
1
### Find your rate2
f
2
### Choose your repayment option and term3
3
### Finish your application and submit
[Find My Rate](http://abe.psl.sparrowfi.com)
Have questions before you take the next step? Check out our [FAQs](https://www.abestudentloans.com/resources/#faq) or [Contact Us](#contact).










### Your path to practice.
From first class to first patient, every healthcare journey looks a little different. An Abe Healthcare Professionals student loan is built to support all of them, with flexible financing that fits your timeline, training, and career goals.
#### An Abe Healthcare Professionals student loan can help support medical career milestones such as:
- Program coursework and clinicals
- Licensing or certification exams
- Internships, fieldwork, or residencies
- Graduation and career launch
- [Borrower Benefits](#borrower-benefits)
- [Cosigner Information](#cosigner-information)
- [Repayment Options](#repayment-options)
- [Repayment Terms](#repayment-terms)
- [Payment Relief](#payment-relief)
### Borrower Benefits
### Reduce your rate by up to 0.50% by building a good payment history.
Abe allows you to reduce your rate by 0.25% by electing auto pay18, even while you are enrolled in school, and up to an additional 0.25% interest rate reduction for making on-time principal and interest payments9 during the repayment term.
### 2% Grad Reward8
Upon request after graduating, reduce your principal balance by 2% of your net disbursed loan amount.
### Early Cosigner Release13
Abe recognizes the shared commitment you and your cosigner made when taking out your student loan. That’s why, after just 12 months of on-time principal and interest payments, you can apply to release your cosigner – allowing you to take sole responsibility for the loan moving forward.
[Find My Rate](http://abe.psl.sparrowfi.com)
### Cosigner Information
### A cosigner significantly increases your approval chances.
### 3 out of 4 approved applicants have a cosigner.
You don’t have to have a cosigner to apply for an Abe loan. That said, there are several reasons why it’s a really good idea to have one.
### Applying with a creditworthy cosigner may result in a lower interest rate.
[Learn More About Cosigners](https://www.abestudentloans.com/cosigners/)
### Repayment Options3
IMMEDIATE REPAYMENT
Make full payments in school.
INTEREST ONLY
Pay only interest in school.
FLAT PAYMENT
Make flat partial payments in school.
FULLY DEFERRED
Full payments after you graduate.
### Make full principal and interest payments while you study.
- Start making principal and interest payments right away
- Making higher monthly payments while you are still in school saves you the most money overall
[Find My Rate](http://abe.psl.sparrowfi.com)

### Make only interest payments while in school.
- Interest only payments reduce the long-term cost of your loan
- This is a good option if you can't make full payments while in school but still want to make life easier after you graduate by making smaller monthly payments now
[Find My Rate](http://abe.psl.sparrowfi.com)

### Make $25 payments each month during school to reduce your accrued interest.
- Steadily chip away at your loan's interest by making low, flat monthly payments while you study
- This is a great option if you can't quite afford full interest payments just yet, but still want to start making a dent in the overall cost of your loan right away
[Find My Rate](http://abe.psl.sparrowfi.com)

### Wait to make payments until after you graduate and are earning money.
- Waiting until you graduate before you start making payments allows you to focus on your studies without worrying about loan payments
- Keep in mind interest will continue to accrue on your loan during this time, making this the most expensive option over all
[Find My Rate](http://abe.psl.sparrowfi.com)

### In-School Default Protection4 protects you from default.
If you elect to make interest only or flat payments while in-school but fall short, In-School Default Protection will save you from default by automatically switching you to a deferred payment program. Abe also features an extra year of in-school deferment20 – up to 60 months (5 years) in case it takes a little longer to get your degree.
### Repayment Terms
### Abe has five different loan terms:
#### 5, 7, 10, 15, or 20 years.3
The shorter the term, the more you save on interest payments. Longer terms mean lower monthly payments, but higher overall cost of the loan.
Use the configurator to see how adjusting the length of your loan changes the monthly payment, and then choose the shortest term with a payment amount you’re comfortable making.
[Find My Rate](http://abe.psl.sparrowfi.com)
### Payment Relief
### 6 months of grace and then 6 more.
Once you graduate, you have to look for a job. You may have to move. Buy a car. If you need 6 months before starting repayment, you got it.15 Then if you need 6 more months, that’s fine, too.16
### Past due balances.
Falling behind and accumulating a past-due school balance can happen, particularly during financial emergencies or unexpected circumstances. If this occurs, an Abe loan can be used to cover the outstanding balance within 18 months of the academic period end date.17
### Re-enrollment, medical internships, and residencies.
If you re-enroll in school, or enter a medical internship or residency, we offer derment options.10
### Health and family first.
If you end up out of work due to illness or go on unpaid FMLA leave, Abe provides up to 12 months of medical forbearance.12
### A safety net just in case.
A lot can happen over the life of a loan. You may lose your job, or suffer from a financial hardship,11 or be impacted by a natural disaster.22 Abe is there for you with opportunities for payment relief.
### Extended payment relief.
If you have gone through a reduced payment program and still need relief to get back on your feet, you may be eligible for a term extension of 60 months (5 years), which will lower your monthly payments.21
## How Abe stacks up.\*
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
### Abe.
####
Up to 12 Months^
5, 7, 10, 15 or 20 Years
####
####
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
#### CollegeAve
####
6 Months
5, 8, 10 or 15 Years
####
####
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
#### Earnest
####
9 Months
5, 7, 10, 12 or 15 Years
####
####
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
#### Sallie Mae
####
6 Months
10 to 15 Years
####
####
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
#### SoFi
####
6 Months
5, 7, 10, 15 or 20 Years
####
####
\*Comparisons based on competitors’ websites (as of 7/27/26).
^6 months grace guaranteed + possible 6 months grace extension.
## Apply in minutes with 3 easy steps.
1
### Find your rate2
f
2
### Choose your repayment option and term3
3
### Finish your application and submit
[Find My Rate](http://abe.psl.sparrowfi.com)
Have questions before you take the next step? Check out our [FAQs](https://www.abestudentloans.com/resources/#faq) or [Contact Us](#contact).
## Abe Healthcare Professionals Student Loan FAQs
### Who can apply for an Abe Healthcare Professionals student loan?
Graduate students enrolled in a nursing, pharmacy, or allied health professional (e.g., Dieticians, OT, Speech Pathologist, Audiologist, Dental Hygienist etc.) degree program at an eligible school can apply.24 You must also meet the following criteria:
- You’re at the legal age of majority, or at least 17 years of age at the time of application if applying with a cosigner who meets age of majority requirements in the cosigner’s state of residence
- You’re a U.S. citizen, permanent resident alien or an Eligible Non-Citizen (DACA recipient) applying with an eligible cosigner who is a U.S. citizen or permanent resident alien, or an international student applying with an eligible cosigner who is a U.S. citizen or permanent resident alien
### What can an Abe Healthcare Professionals student loan be used to pay for?
An Abe Healthcare Professionals student loan can be used to pay for up to 100% of the total cost of healthcare profession school expenses,1 including:
- Tuition and fees
- Room and board (on or off campus)
- Books and supplies
- Clinical supplies, lab fees, and simulation tools
- Licensing or certification exam fees (if approved by your school)
- A laptop or tablet for coursework and clinical documentation
- Travel related to clinical placements or internships
- Everyday living expenses while you’re enrolled
### How much can I borrow?
An Abe Healthcare Professionals student loan enables you to borrow from $1,000 up to your school’s certified cost of attendance,1 minus any other aid you’re receiving from funding such as federal loans, grants and scholarships.
### What information do I need to apply?
Applying for an Abe Healthcare Professionals student loan is quick and easy, but having a few things ready can make it even faster:
- Your date of birth and Social Security number
- Mailing and email adress and phone number
- Your school name and grade level as well as expected graduation date
- The amount you’d like to borrow
- Employment and income info (for you and your cosigner, if you have one)23
- A valid ID (like a driver’s license or passport)
If you’re applying with a cosigner, they’ll need to provide similar information. Don’t worry, we’ll walk you through it step by step.
### What happens if I need help making payments later?
Life doesn’t always go as planned. Abe Healthcare Professionals student loans come with built-in flexibility like deferment and forbearance if things get tough after graduation and you need more time.
### Is there a penalty for paying off my loan early?
Nope. You can pay off your loan at any time with no prepayment penalties.
## Find the loan that fits your goals.
No matter where you are headed on your education journey, Abe can help you get there.
- [Undergraduate](https://www.abestudentloans.com/student-loans/undergraduate/)
- [Graduate](https://www.abestudentloans.com/student-loans/graduate/)
- [Law](https://www.abestudentloans.com/student-loans/graduate/law/)
- [MBA](https://www.abestudentloans.com/student-loans/graduate/mba/)
- [Medical](https://www.abestudentloans.com/student-loans/graduate/medical/)
- [Dental](https://www.abestudentloans.com/student-loans/graduate/dental/)
- [Healthcare Professionals](https://www.abestudentloans.com/student-loans/graduate/healthcare-professionals/)
---
### [Dental School](https://www.abestudentloans.com/student-loans/graduate/dental/)
**Published:** May 27, 2025
**Author:** abelending
**Content:**
# Dental School
Student Loans
No application fees, processing fees, or late fees
Four repayment options, five loan terms3
Available to students enrolled full time, part-time, or less than half time
Up to 100% of all costs associated with dental school1
Find your rate in minutes2 with no impact to your credit score
[Find My Rate](http://abe.psl.sparrowfi.com)
## Dental school takes focus, precision, and a serious commitment.
That’s why Abe® offers low rates and flexible repayment options3 to help you stay locked in on clinicals, licensure, and launching your career. Apply on your own or with a cosigner to access the best possible rate.
### Fixed Rates
### 2.08%
### to 15.58% APR[6](#f6),[7](#f7)
### Variable Rates
### 3.50%
### to 15.21% APR[6](#f6),[7](#f7)
*Lowest APRs (Annual Percentage Rates) include a 0.25% discount when auto pay is elected.18*
## Apply in minutes with 3 easy steps.
1
### Find your rate2
f
2
### Choose your repayment option and term3
3
### Finish your application and submit
[Find My Rate](http://abe.psl.sparrowfi.com)
Have questions before you take the next step? Check out our [FAQs](https://www.abestudentloans.com/resources/#faq) or [Contact Us](#contact).











### Specialties covered, from Ortho to Endo.
Whether you’re planning to enter practice after dental school or continue into a specialized residency, Abe is here for the full journey. Your Abe Dental School student loan can help cover up to 100% of the school certified cost of your next step toward specialization.1
#### Your Abe Dental School student loan can help with:
- Tuition and fees for postdoctoral programs in orthodontics, endodontics, periodontics, prosthodontics, oral surgery, and more
- Required equipment and board exam costs for specialty certification
- Living expenses during extended training programs
- Transportation expenses tied to residency or specialty placements
- [Borrower Benefits](#borrower-benefits)
- [Cosigner Information](#cosigner-information)
- [Repayment Options](#repayment-options)
- [Repayment Terms](#repayment-terms)
- [Payment Relief](#payment-relief)
### Borrower Benefits
### Reduce your rate by up to 0.50% by building a good payment history.
Abe allows you to reduce your rate by 0.25% by electing auto pay18, even while you are enrolled in school, and up to an additional 0.25% interest rate reduction for making on-time principal and interest payments9 during the repayment term.
### 2% Grad Reward8
Upon request after graduating, reduce your principal balance by 2% of your net disbursed loan amount.
### Early Cosigner Release13
Abe recognizes the shared commitment you and your cosigner made when taking out your student loan. That’s why, after just 12 months of on-time principal and interest payments, you can apply to release your cosigner – allowing you to take sole responsibility for the loan moving forward.
[Find My Rate](http://abe.psl.sparrowfi.com)
### Cosigner Information
### A cosigner significantly increases your approval chances.
### 3 out of 4 approved applicants have a cosigner.
You don’t have to have a cosigner to apply for an Abe loan. That said, there are several reasons why it’s a really good idea to have one.
### Applying with a creditworthy cosigner may result in a lower interest rate.
[Learn More About Cosigners](https://www.abestudentloans.com/cosigners/)
### Repayment Options3
IMMEDIATE REPAYMENT
Make full payments in school.
INTEREST ONLY
Pay only interest in school.
FLAT PAYMENT
Make flat partial payments in school.
FULLY DEFERRED
Full payments after you graduate.
### Make full principal and interest payments while you study.
- Start making principal and interest payments right away
- Making higher monthly payments while you are still in school saves you the most money overall
[Find My Rate](http://abe.psl.sparrowfi.com)

### Make only interest payments while in school.
- Interest only payments reduce the long-term cost of your loan
- This is a good option if you can't make full payments while in school but still want to make life easier after you graduate by making smaller monthly payments now
[Find My Rate](http://abe.psl.sparrowfi.com)

### Make $25 payments each month during school to reduce your accrued interest.
- Steadily chip away at your loan's interest by making low, flat monthly payments while you study
- This is a great option if you can't quite afford full interest payments just yet, but still want to start making a dent in the overall cost of your loan right away
[Find My Rate](http://abe.psl.sparrowfi.com)

### Wait to make payments until after you graduate and are earning money.
- Waiting until you graduate before you start making payments allows you to focus on your studies without worrying about loan payments
- Keep in mind interest will continue to accrue on your loan during this time, making this the most expensive option over all
[Find My Rate](http://abe.psl.sparrowfi.com)

### In-School Default Protection4 protects you from default.
If you elect to make interest only or flat payments while in-school but fall short, In-School Default Protection will save you from default by automatically switching you to a deferred payment program. Abe also features an extra year of in-school deferment20 – up to 60 months (5 years) in case it takes a little longer to get your degree.
### Repayment Terms
### Abe has five different loan terms:
#### 5, 7, 10, 15, or 20 years.3
The shorter the term, the more you save on interest payments. Longer terms mean lower monthly payments, but higher overall cost of the loan.
Use the configurator to see how adjusting the length of your loan changes the monthly payment, and then choose the shortest term with a payment amount you’re comfortable making.
[Find My Rate](http://abe.psl.sparrowfi.com)
### Payment Relief
### 6 months of grace and then 6 more.
Once you graduate, you have to look for a job. You may have to move. Buy a car. If you need 6 months before starting repayment, you got it.15 Then if you need 6 more months, that’s fine, too.16
### Past due balances.
Falling behind and accumulating a past-due school balance can happen, particularly during financial emergencies or unexpected circumstances. If this occurs, an Abe loan can be used to cover the outstanding balance within 18 months of the academic period end date.17
### Re-enrollment, dental residencies, and specialty programs.
If you return to school for a specialty program—like orthodontics, endodontics, or oral surgery—or extend your training through a dental residency, deferment options10 are available in 12 month increments.
### Health and family first.
If you end up out of work due to illness or go on unpaid FMLA leave, Abe provides up to 12 months of medical forbearance.12
### A safety net just in case.
A lot can happen over the life of a loan. You may lose your job, or suffer from a financial hardship,11 or be impacted by a natural disaster.22 Abe is there for you with opportunities for payment relief.
### Extended payment relief.
If you have gone through a reduced payment program and still need relief to get back on your feet, you may be eligible for a term extension of 60 months (5 years), which will lower your monthly payments.21
## How Abe stacks up.\*
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
### Abe.
####
Up to 12 Months^
5, 7, 10, 15 or 20 Years
####
####
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
#### CollegeAve
####
6 Months
5, 8, 10 or 15 Years
####
####
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
#### Earnest
####
9 Months
5, 7, 10, 12 or 15 Years
####
####
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
#### Sallie Mae
####
6 Months
10 to 15 Years
####
####
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
#### SoFi
####
6 Months
5, 7, 10, 15 or 20 Years
####
####
\*Comparisons based on competitors’ websites (as of 7/27/26).
^6 months grace guaranteed + possible 6 months grace extension.
## Apply in minutes with 3 easy steps.
1
### Find your rate2
f
2
### Choose your repayment option and term3
3
### Finish your application and submit
[Find My Rate](http://abe.psl.sparrowfi.com)
Have questions before you take the next step? Check out our [FAQs](https://www.abestudentloans.com/resources/#faq) or [Contact Us](#contact).
## Abe Dental School Student Loan FAQs
### Who can apply for an Abe Dental School student loan?
Graduate students enrolled in a dentistry degree program (Pediatric dentistry, Periodontics, Oral Surgeon etc.) at an eligible school can apply.24 You must also meet the following criteria:
- You’re at the legal age of majority, or at least 17 years of age at the time of application if applying with a cosigner who meets age of majority requirements in the cosigner’s state of residence
- You’re a U.S. citizen, permanent resident alien or an Eligible Non-Citizen (DACA recipient) applying with an eligible cosigner who is a U.S. citizen or permanent resident alien, or an international student applying with an eligible cosigner who is a U.S. citizen or permanent resident alien
### What can an Abe Dental School student loan be used to pay for?
An Abe Dental School student loan can be used to pay for up to 100% of the total cost of dental school expenses,1 including:
- Tuition and fees
- Room and board (on or off campus)
- Books and supplies
- Dental equipment kits, loupes, and lab fees
- Clinical supplies and PPE
- Licensing exams (if approved by your school)
- A laptop or tablet for coursework and clinical documentation
- Travel related to externships or specialty programs
- Everyday living expenses while you’re enrolled
### How much can I borrow?
An Abe Dental School student loan enables you to borrow from $1,000 up to your school’s certified cost of attendance,1 minus any other aid you’re receiving from funding such as federal loans, grants and scholarships.
### What information do I need to apply?
Applying for an Abe Dental School student loan is quick and easy, but having a few things ready can make it even faster:
- Your date of birth and Social Security number
- Mailing and email adress and phone number
- Your school name and grade level as well as expected graduation date
- The amount you’d like to borrow
- Employment and income info (for you and your cosigner, if you have one)23
- A valid ID (like a driver’s license or passport)
If you’re applying with a cosigner, they’ll need to provide similar information. Don’t worry, we’ll walk you through it step by step.
### What happens if I need help making payments later?
Life doesn’t always go as planned. Abe Dental School student loans come with built-in flexibility like deferment and forbearance if things get tough after graduation and you need more time.
### Is there a penalty for paying off my loan early?
Nope. You can pay off your loan at any time with no prepayment penalties.
## Find the loan that fits your goals.
No matter where you are headed on your education journey, Abe can help you get there.
- [Undergraduate](https://www.abestudentloans.com/student-loans/undergraduate/)
- [Graduate](https://www.abestudentloans.com/student-loans/graduate/)
- [Law](https://www.abestudentloans.com/student-loans/graduate/law/)
- [MBA](https://www.abestudentloans.com/student-loans/graduate/mba/)
- [Medical](https://www.abestudentloans.com/student-loans/graduate/medical/)
- [Dental](https://www.abestudentloans.com/student-loans/graduate/dental/)
- [Healthcare Professionals](https://www.abestudentloans.com/student-loans/graduate/healthcare-professionals/)
---
### [Medical School](https://www.abestudentloans.com/student-loans/graduate/medical/)
**Published:** May 27, 2025
**Author:** abelending
**Content:**
# Medical School
Student Loans
No application fees, processing fees, or late fees
Four repayment options, five loan terms3
Available to students enrolled full time, part-time, or less than half time
Up to 100% of all costs associated with medical school1
Find your rate in minutes2 with no impact to your credit score
[Find My Rate](http://abe.psl.sparrowfi.com)
## From first year through residency, an Abe® Medical School student loan helps you focus on becoming the amazing doctor you’re meant to be.
Low rates and expanded repayment options3 let you tailor your Abe loan to your timeline. Applying with a cosigner may help you get an even lower rate.
### Fixed Rates
### 2.08%
### to 15.58% APR[6](#f6),[7](#f7)
### Variable Rates
### 3.50%
### to 15.21% APR[6](#f6),[7](#f7)
*Lowest APRs (Annual Percentage Rates) include a 0.25% discount when auto pay is elected.18*
#### Abe Named Best Private Student Loan for Medical School in July 2026
## Apply in minutes with 3 easy steps.
1
### Find your rate2
f
2
### Choose your repayment option and term3
3
### Finish your application and submit
[Find My Rate](http://abe.psl.sparrowfi.com)
Have questions before you take the next step? Check out our [FAQs](https://www.abestudentloans.com/resources/#faq) or [Contact Us](#contact).











### What counts as a medical school expense?
An Abe Medical School student loan can cover more than just your classes, it’s designed to cover up to the full cost of attendance.1
#### Here’s what an Abe Medical School student loan could help pay for:
- **Board exams** like USMLE Step 1, Step 2, and Step 3
- **Required equipment** like stethoscopes, scrubs, and diagnostic kits
- **Technology** including tablets, laptops, or clinical software
- **Licensing and credentialing fees**
- **Living expenses**, including rent, groceries, and transportation
- **Health insurance premiums** if included in your school’s cost of attendance
- [Borrower Benefits](#borrower-benefits)
- [Cosigner Information](#cosigner-information)
- [Repayment Options](#repayment-options)
- [Repayment Terms](#repayment-terms)
- [Payment Relief](#payment-relief)
### Borrower Benefits
### Reduce your rate by up to 0.50% by building a good payment history.
Abe allows you to reduce your rate by 0.25% by electing auto pay18, even while you are enrolled in school, and up to an additional 0.25% interest rate reduction for making on-time principal and interest payments9 during the repayment term.
### 2% Grad Reward8
Upon request after graduating, reduce your principal balance by 2% of your net disbursed loan amount.
### Early Cosigner Release13
Abe recognizes the shared commitment you and your cosigner made when taking out your student loan. That’s why, after just 12 months of on-time principal and interest payments, you can apply to release your cosigner – allowing you to take sole responsibility for the loan moving forward.
[Find My Rate](http://abe.psl.sparrowfi.com)
### Cosigner Information
### A cosigner significantly increases your approval chances.
### 3 out of 4 approved applicants have a cosigner.
You don’t have to have a cosigner to apply for an Abe loan. That said, there are several reasons why it’s a really good idea to have one.
### Applying with a creditworthy cosigner may result in a lower interest rate.
[Learn More About Cosigners](https://www.abestudentloans.com/cosigners/)
### Repayment Options3
IMMEDIATE REPAYMENT
Make full payments in school.
INTEREST ONLY
Pay only interest in school.
FLAT PAYMENT
Make flat partial payments in school.
FULLY DEFERRED
Full payments after you graduate.
### Make full principal and interest payments while you study.
- Start making principal and interest payments right away
- Making higher monthly payments while you are still in school saves you the most money overall
[Find My Rate](http://abe.psl.sparrowfi.com)

### Make only interest payments while in school.
- Interest only payments reduce the long-term cost of your loan
- This is a good option if you can't make full payments while in school but still want to make life easier after you graduate by making smaller monthly payments now
[Find My Rate](http://abe.psl.sparrowfi.com)

### Make $25 payments each month during school to reduce your accrued interest.
- Steadily chip away at your loan's interest by making low, flat monthly payments while you study
- This is a great option if you can't quite afford full interest payments just yet, but still want to start making a dent in the overall cost of your loan right away
[Find My Rate](http://abe.psl.sparrowfi.com)

### Wait to make payments until after you graduate and are earning money.
- Waiting until you graduate before you start making payments allows you to focus on your studies without worrying about loan payments
- Keep in mind interest will continue to accrue on your loan during this time, making this the most expensive option over all
[Find My Rate](http://abe.psl.sparrowfi.com)

### In-School Default Protection4 protects you from default.
If you elect to make interest only or flat payments while in-school but fall short, In-School Default Protection will save you from default by automatically switching you to a deferred payment program. Abe also features an extra year of in-school deferment20 – up to 60 months (5 years) in case it takes a little longer to get your degree.
### Repayment Terms
### Abe has five different loan terms:
#### 5, 7, 10, 15, or 20 years.3
The shorter the term, the more you save on interest payments. Longer terms mean lower monthly payments, but higher overall cost of the loan.
Use the configurator to see how adjusting the length of your loan changes the monthly payment, and then choose the shortest term with a payment amount you’re comfortable making.
[Find My Rate](http://abe.psl.sparrowfi.com)
### Payment Relief
### 6 months of grace and then 6 more.
Once you graduate, you have to look for a job. You may have to move. Buy a car. If you need 6 months before starting repayment, you got it.15 Then if you need 6 more months, that’s fine, too.16
### Past due balances.
Falling behind and accumulating a past-due school balance can happen, particularly during financial emergencies or unexpected circumstances. If this occurs, an Abe loan can be used to cover the outstanding balance within 18 months of the academic period end date.17
### Re-enrollment, medical internships, and residencies.
If you re-enroll in school, or enter a medical internship or residency, we offer deferment options.10
### Health and family first.
If you end up out of work due to illness or go on unpaid FMLA leave, Abe provides up to 12 months of medical forbearance.12
### A safety net just in case.
A lot can happen over the life of a loan. You may lose your job, or suffer from a financial hardship,11 or be impacted by a natural disaster.22 Abe is there for you with opportunities for payment relief.
### Extended payment relief.
If you have gone through a reduced payment program and still need relief to get back on your feet, you may be eligible for a term extension of 60 months (5 years), which will lower your monthly payments.21
## How Abe stacks up.\*
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
### Abe.
####
Up to 12 Months^
5, 7, 10, 15 or 20 Years
####
####
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
#### CollegeAve
####
6 Months
5, 8, 10 or 15 Years
####
####
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
#### Earnest
####
9 Months
5, 7, 10, 12 or 15 Years
####
####
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
#### Sallie Mae
####
6 Months
10 to 15 Years
####
####
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
#### SoFi
####
6 Months
5, 7, 10, 15 or 20 Years
####
####
\*Comparisons based on competitors’ websites (as of 7/27/26).
^6 months grace guaranteed + possible 6 months grace extension.
## Apply in minutes with 3 easy steps.
1
### Find your rate2
f
2
### Choose your repayment option and term3
3
### Finish your application and submit
[Find My Rate](http://abe.psl.sparrowfi.com)
Have questions before you take the next step? Check out our [FAQs](https://www.abestudentloans.com/resources/#faq) or [Contact Us](#contact).
## Abe Medical School Student Loan FAQs
### Who can apply for a Medical School student loan?
Graduate students enrolled in doctoral degree programs (Doctor of Medicine (MD), Osteopathic Medicine (DO), Veterinary Medicine (DVM, VMD), or Podiatric Medicine (PM)) at an eligible school can apply.24 You must also meet the following criteria:
- You’re at the legal age of majority, or at least 17 years of age at the time of application if applying with a cosigner who meets age of majority requirements in the cosigner’s state of residence
- You’re a U.S. citizen, permanent resident alien or an Eligible Non-Citizen (DACA recipient) applying with an eligible cosigner who is a U.S. citizen or permanent resident alien, or an international student applying with an eligible cosigner who is a U.S. citizen or permanent resident alien
### What can a Medical School student loan be used to pay for?
A Medical School student loan can be used to pay for up to 100% of the total cost of medical school expenses,1 including:
- Tuition and fees
- Room and board (on or off campus)
- Books, supplies, and required medical equipment
- A laptop, tablet or other tech for coursework and clinicals
- Board exam fees (Step 1, Step 2, Step 3)
- Licensing and credentialing costs
- Everyday living expenses while you’re enrolled
### How much can I borrow?
A Medical School student loan enables you to borrow from $1,000 up to your school’s certified cost of attendance,1 minus any other aid you’re receiving from funding such as federal loans, grants and scholarships.
### What information do I need to apply?
Applying for a Medical School student loan is quick and easy, but having a few things ready can make it even faster:
- Your date of birth and Social Security number
- Mailing and email adress and phone number
- Your school name and grade level as well as expected graduation date
- The amount you’d like to borrow
- Employment and income info (for you and your cosigner, if you have one)23
- A valid ID (like a driver’s license or passport)
If you’re applying with a cosigner, they’ll need to provide similar information. Don’t worry, we’ll walk you through it step by step.
### What happens if I need help making payments later?
Life doesn’t always go as planned. Medical School student loans come with built-in flexibility like deferment and forbearance if things get tough after graduation and you need more time.
### Is there a penalty for paying off my loan early?
Nope. You can pay off your loan at any time with no prepayment penalties.
## Find the loan that fits your goals.
No matter where you are headed on your education journey, Abe can help you get there.
- [Undergraduate](https://www.abestudentloans.com/student-loans/undergraduate/)
- [Graduate](https://www.abestudentloans.com/student-loans/graduate/)
- [Law](https://www.abestudentloans.com/student-loans/graduate/law/)
- [MBA](https://www.abestudentloans.com/student-loans/graduate/mba/)
- [Medical](https://www.abestudentloans.com/student-loans/graduate/medical/)
- [Dental](https://www.abestudentloans.com/student-loans/graduate/dental/)
- [Healthcare Professionals](https://www.abestudentloans.com/student-loans/graduate/healthcare-professionals/)
---
### [MBA](https://www.abestudentloans.com/student-loans/graduate/mba/)
**Published:** May 27, 2025
**Author:** abelending
**Content:**
# MBA
Student Loans
No application fees, processing fees, or late fees
Four repayment options, five loan terms3
Available to students enrolled full time, part-time, or less than half time
Up to 100% of MBA expenses covered1
Find your rate in minutes2 with no impact to your credit score
[Find My Rate](http://abe.psl.sparrowfi.com)
## Low rates that work almost as hard for your MBA as you do.
Earning your MBA degree means investing in your potential—whether you’re pivoting careers, leveling up your leadership role, or launching something of your own. Apply solo or with a cosigner, and choose the repayment plan3 that fits your timeline.
### Fixed Rates
### 2.08%
### to 15.58% APR[6](#f6),[7](#f7)
### Variable Rates
### 3.50%
### to 15.21% APR[6](#f6),[7](#f7)
*Lowest APRs (Annual Percentage Rates) include a 0.25% discount when auto pay is elected.18*
## Apply in minutes with 3 easy steps.
1
### Find your rate2
f
2
### Choose your repayment option and term3
3
### Finish your application and submit
[Find My Rate](http://abe.psl.sparrowfi.com)
Have questions before you take the next step? Check out our [FAQs](https://www.abestudentloans.com/resources/#faq) or [Contact Us](#contact).











### What’s the ROI on an MBA degree?
An MBA is more than a degree, it’s a launchpad. In 2024, the median starting salary for MBA grads in the U.S. was **$120,000**, nearly **75% higher** than for bachelor’s degree holders.ˆ At top business schools, total compensation often exceeds **$200,000**, especially in financing, consulting, and tech.˜ °
ˆGMAC Corporate Recruiters Survey 2024. ˜ Poets & Quants 2024 MBA Salary Report. °U.S. News MBA ROI Rankings.
- [Borrower Benefits](#borrower-benefits)
- [Cosigner Information](#cosigner-information)
- [Repayment Options](#repayment-options)
- [Repayment Terms](#repayment-terms)
- [Payment Relief](#payment-relief)
### Borrower Benefits
### Reduce your rate by up to 0.50% by building a good payment history.
Abe® allows you to reduce your rate by 0.25% by electing auto pay18, even while you are enrolled in school, and up to an additional 0.25% interest rate reduction for making on-time principal and interest payments9 during the repayment term.
### 2% Grad Reward8
Upon request after graduating, reduce your principal balance by 2% of your net disbursed loan amount.
### Early Cosigner Release13
Abe recognizes the shared commitment you and your cosigner made when taking out your student loan. That’s why, after just 12 months of on-time principal and interest payments, you can apply to release your cosigner – allowing you to take sole responsibility for the loan moving forward.
[Find My Rate](http://abe.psl.sparrowfi.com)
### Cosigner Information
### A cosigner significantly increases your approval chances.
### 3 out of 4 approved applicants have a cosigner.
You don’t have to have a cosigner to apply for an Abe loan. That said, there are several reasons why it’s a really good idea to have one.
### Applying with a creditworthy cosigner may result in a lower interest rate.
[Learn More About Cosigners](https://www.abestudentloans.com/cosigners/)
### Repayment Options3
IMMEDIATE REPAYMENT
Make full payments in school.
INTEREST ONLY
Pay only interest in school.
FLAT PAYMENT
Make flat partial payments in school.
FULLY DEFERRED
Full payments after you graduate.
### Make full principal and interest payments while you study.
- Start making principal and interest payments right away
- Making higher monthly payments while you are still in school saves you the most money overall
[Find My Rate](http://abe.psl.sparrowfi.com)

### Make only interest payments while in school.
- Interest only payments reduce the long-term cost of your loan
- This is a good option if you can't make full payments while in school but still want to make life easier after you graduate by making smaller monthly payments now
[Find My Rate](http://abe.psl.sparrowfi.com)

### Make $25 payments each month during school to reduce your accrued interest.
- Steadily chip away at your loan's interest by making low, flat monthly payments while you study
- This is a great option if you can't quite afford full interest payments just yet, but still want to start making a dent in the overall cost of your loan right away
[Find My Rate](http://abe.psl.sparrowfi.com)

### Wait to make payments until after you graduate and are earning money.
- Waiting until you graduate before you start making payments allows you to focus on your studies without worrying about loan payments
- Keep in mind interest will continue to accrue on your loan during this time, making this the most expensive option over all
[Find My Rate](http://abe.psl.sparrowfi.com)

### In-School Default Protection4 protects you from default.
If you elect to make interest only or flat payments while in-school but fall short, In-School Default Protection will save you from default by automatically switching you to a deferred payment program. Abe also features an extra year of in-school deferment20 – up to 60 months (5 years) in case it takes a little longer to get your degree.
### Repayment Terms
### Abe has five different loan terms:
#### 5, 7, 10, 15, or 20 years.3
The shorter the term, the more you save on interest payments. Longer terms mean lower monthly payments, but higher overall cost of the loan.
Use the configurator to see how adjusting the length of your loan changes the monthly payment, and then choose the shortest term with a payment amount you’re comfortable making.
[Find My Rate](http://abe.psl.sparrowfi.com)
### Payment Relief
### 6 months of grace and then 6 more.
Once you graduate, you have to look for a job. You may have to move. Buy a car. If you need 6 months before starting repayment, you got it.15 Then if you need 6 more months, that’s fine, too.16
### Past due balances.
Falling behind and accumulating a past-due school balance can happen, particularly during financial emergencies or unexpected circumstances. If this occurs, an Abe loan can be used to cover the outstanding balance within 18 months of the academic period end date.17
### Deferment options for re-enrollment and extended programs.
If you re-enroll in school for a dual degree, take time for an international rotation, or extend your MBA program, deferment options are available.10 Abe gives you the flexibility to pause payments while you continue building your business education.
### Health and family first.
If you end up out of work due to illness or go on unpaid FMLA leave, Abe provides up to 12 months of medical forbearance.12
### A safety net just in case.
A lot can happen over the life of a loan. You may lose your job, or suffer from a financial hardship,11 or be impacted by a natural disaster.22 Abe is there for you with opportunities for payment relief.
### Extended payment relief.
If you have gone through a reduced payment program and still need relief to get back on your feet, you may be eligible for a term extension of 60 months (5 years), which will lower your monthly payments.21
## How Abe stacks up.\*
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
### Abe.
####
Up to 12 Months^
5, 7, 10, 15 or 20 Years
####
####
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
#### CollegeAve
####
6 Months
5, 8, 10 or 15 Years
####
####
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
#### Earnest
####
9 Months
5, 7, 10, 12 or 15 Years
####
####
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
#### Sallie Mae
####
6 Months
10 to 15 Years
####
####
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
#### SoFi
####
6 Months
5, 7, 10, 15 or 20 Years
####
####
\*Comparisons based on competitors’ websites (as of 7/27/26).
^6 months grace guaranteed + possible 6 months grace extension.
## Apply in minutes with 3 easy steps.
1
### Find your rate2
f
2
### Choose your repayment option and term3
3
### Finish your application and submit
[Find My Rate](http://abe.psl.sparrowfi.com)
Have questions before you take the next step? Check out our [FAQs](https://www.abestudentloans.com/resources/#faq) or [Contact Us](#contact).
## Abe MBA Student Loan FAQs
### Who can apply for an Abe MBA student loan?
Graduate students enrolled in an MBA degree program at an eligible school can apply.24 You must also meet the following criteria:
- You’re at the legal age of majority, or at least 17 years of age at the time of application if applying with a cosigner who meets age of majority requirements in the cosigner’s state of residence
- You’re a U.S. citizen, permanent resident alien or an Eligible Non-Citizen (DACA recipient) applying with an eligible cosigner who is a U.S. citizen or permanent resident alien, or an international student applying with an eligible cosigner who is a U.S. citizen or permanent resident alien
### What can an Abe MBA student loan be used to pay for?
An Abe MBA student loan can be used to pay for up to 100% of the total cost of an MBA degree,1 including:
- Tuition and fees
- Room and board (on or off campus)
- Books and supplies
- A laptop or other tech needed for school
- Transportation and travel
- Study abroad or global immersion programs (if part of your MBA curriculum)
- Everyday living expenses while you’re enrolled
### How much can I borrow?
An Abe MBA student loan enables you to borrow from $1,000 up to your school’s certified cost of attendance,1 minus any other aid you’re receiving from funding such as federal loans, grants and scholarships.
### What information do I need to apply?
Applying for an Abe MBA student loan is quick and easy, but having a few things ready can make it even faster:
- Your date of birth and Social Security number
- Mailing and email adress and phone number
- Your school name and grade level as well as expected graduation date
- The amount you’d like to borrow
- Employment and income info (for you and your cosigner, if you have one)23
- A valid ID (like a driver’s license or passport)
If you’re applying with a cosigner, they’ll need to provide similar information. Don’t worry, we’ll walk you through it step by step.
### What happens if I need help making payments later?
Life doesn’t always go as planned. Abe MBA student loans come with built-in flexibility like deferment and forbearance if things get tough after graduation and you need more time.
### Is there a penalty for paying off my loan early?
Nope. You can pay off your loan at any time with no prepayment penalties.
## Find the loan that fits your goals.
No matter where you are headed on your education journey, Abe can help you get there.
- [Undergraduate](https://www.abestudentloans.com/student-loans/undergraduate/)
- [Graduate](https://www.abestudentloans.com/student-loans/graduate/)
- [Law](https://www.abestudentloans.com/student-loans/graduate/law/)
- [MBA](https://www.abestudentloans.com/student-loans/graduate/mba/)
- [Medical](https://www.abestudentloans.com/student-loans/graduate/medical/)
- [Dental](https://www.abestudentloans.com/student-loans/graduate/dental/)
- [Healthcare Professionals](https://www.abestudentloans.com/student-loans/graduate/healthcare-professionals/)
---
### [Law School](https://www.abestudentloans.com/student-loans/graduate/law/)
**Published:** May 27, 2025
**Author:** abelending
**Content:**
# Law School
Student Loans
No application fees, processing fees, or late fees
Four repayment options, five loan terms3
Available to students enrolled full time, part-time, or less than half time
Up to 100% of all costs associated with Law School1
Find your rate in minutes2 with no impact to your credit score
[Find My Rate](http://abe.psl.sparrowfi.com)
## Law school is tough enough without having to worry about paying for it.
Abe’s® low rates and expanded repayment options3 let you focus on becoming the legal eagle you’re meant to be. Applying with a cosigner may help you get an even lower rate.
### Fixed Rates
### 2.08%
### to 15.58% APR[6](#f6),[7](#f7)
### Variable Rates
### 3.50%
### to 15.21% APR[6](#f6),[7](#f7)
*Lowest APRs (Annual Percentage Rates) include a 0.25% discount when auto pay is elected.18*
## Apply in minutes with 3 easy steps.
1
### Find your rate2
f
2
### Choose your repayment option and term3
3
### Finish your application and submit
[Find My Rate](http://abe.psl.sparrowfi.com)
Have questions before you take the next step? Check out our [FAQs](https://www.abestudentloans.com/resources/#faq) or [Contact Us](#contact).










- [Borrower Benefits](#borrower-benefits)
- [Cosigner Information](#cosigner-information)
- [Repayment Options](#repayment-options)
- [Repayment Terms](#repayment-terms)
- [Payment Relief](#payment-relief)
### Borrower Benefits
### Reduce your rate by up to 0.50% by building a good payment history.
Abe allows you to reduce your rate by 0.25% by electing auto pay18, even while you are enrolled in school, and up to an additional 0.25% interest rate reduction for making on-time principal and interest payments9 during the repayment term.
### 2% Grad Reward8
Upon request after graduating, reduce your principal balance by 2% of your net disbursed loan amount.
### Early Cosigner Release13
Abe recognizes the shared commitment you and your cosigner made when taking out your student loan. That’s why, after just 12 months of on-time principal and interest payments, you can apply to release your cosigner – allowing you to take sole responsibility for the loan moving forward.
[Find My Rate](http://abe.psl.sparrowfi.com)
### Cosigner Information
### A cosigner significantly increases your approval chances.
### 3 out of 4 approved applicants have a cosigner.
You don’t have to have a cosigner to apply for an Abe loan. That said, there are several reasons why it’s a really good idea to have one.
### Applying with a creditworthy cosigner may result in a lower interest rate.
[Learn More About Cosigners](https://www.abestudentloans.com/cosigners/)
### Repayment Options3
IMMEDIATE REPAYMENT
Make full payments in school.
INTEREST ONLY
Pay only interest in school.
FLAT PAYMENT
Make flat partial payments in school.
FULLY DEFERRED
Full payments after you graduate.
### Make full principal and interest payments while you study.
- Start making principal and interest payments right away
- Making higher monthly payments while you are still in school saves you the most money overall
[Find My Rate](http://abe.psl.sparrowfi.com)

### Make only interest payments while in school.
- Interest only payments reduce the long-term cost of your loan
- This is a good option if you can't make full payments while in school but still want to make life easier after you graduate by making smaller monthly payments now
[Find My Rate](http://abe.psl.sparrowfi.com)

### Make $25 payments each month during school to reduce your accrued interest.
- Steadily chip away at your loan's interest by making low, flat monthly payments while you study
- This is a great option if you can't quite afford full interest payments just yet, but still want to start making a dent in the overall cost of your loan right away
[Find My Rate](http://abe.psl.sparrowfi.com)

### Wait to make payments until after you graduate and are earning money.
- Waiting until you graduate before you start making payments allows you to focus on your studies without worrying about loan payments
- Keep in mind interest will continue to accrue on your loan during this time, making this the most expensive option over all
[Find My Rate](http://abe.psl.sparrowfi.com)

### In-School Default Protection4 protects you from default.
If you elect to make interest only or flat payments while in-school but fall short, In-School Default Protection will save you from default by automatically switching you to a deferred payment program. Abe also features an extra year of in-school deferment20 – up to 60 months (5 years) in case it takes a little longer to get your degree.
### Repayment Terms
### Abe has five different loan terms:
#### 5, 7, 10, 15, or 20 years.3
The shorter the term, the more you save on interest payments. Longer terms mean lower monthly payments, but higher overall cost of the loan.
Use the configurator to see how adjusting the length of your loan changes the monthly payment, and then choose the shortest term with a payment amount you’re comfortable making.
[Find My Rate](http://abe.psl.sparrowfi.com)
### Payment Relief
### 9 months of grace and then 3 more.
Law school doesn’t end at graduation. Whether you’re preparing for the bar, relocating, or easing into your career, you may find you need more time before you start repayment. An Abe Law School student loan gives you 9 months of grace15 and an optional 3 month extension if you need it.16
### Past due balances.
Falling behind and accumulating a past-due school balance can happen, particularly during financial emergencies or unexpected circumstances. If this occurs, an Abe Law School student loan can be used to cover the outstanding balance within 18 months of the academic period end date.17
### Deferment options for clerkships and continued education.
If you re-enroll in school or take on a judicial clerkship or fellowship after graduation, Abe offers deferment options.10
### Health and family first.
If you end up out of work due to illness or go on unpaid FMLA leave, Abe provides up to 12 months of medical forbearance.12
### A safety net just in case.
A lot can happen over the life of a loan. You may lose your job, or suffer from a financial hardship,11 or be impacted by a natural disaster.22 Abe is there for you with opportunities for payment relief.
### Extended payment relief.
If you have gone through a reduced payment program and still need relief to get back on your feet, you may be eligible for a term extension of 60 months (5 years), which will lower your monthly payments.21
## How Abe stacks up.\*
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
### Abe.
####
Up to 12 Months^
5, 7, 10, 15 or 20 Years
####
####
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
#### CollegeAve
####
6 Months
5, 8, 10 or 15 Years
####
####
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
#### Earnest
####
9 Months
5, 7, 10, 12 or 15 Years
####
####
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
#### Sallie Mae
####
6 Months
10 to 15 Years
####
####
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
#### SoFi
####
6 Months
5, 7, 10, 15 or 20 Years
####
####
\*Comparisons based on competitors’ websites (as of 7/27/26).
^9 months grace guaranteed + possible 3 months grace extension.
## Apply in minutes with 3 easy steps.
1
### Find your rate2
f
2
### Choose your repayment option and term3
3
### Finish your application and submit
[Find My Rate](http://abe.psl.sparrowfi.com)
Have questions before you take the next step? Check out our [FAQs](https://www.abestudentloans.com/resources/#faq) or [Contact Us](#contact).
## Abe Law School Student Loan FAQs
### Who can apply for an Abe Law School student loan?
Graduate students enrolled in a law degree program at an eligible school can apply.24 You must also meet the following criteria:
- You’re at the legal age of majority, or at least 17 years of age at the time of application if applying with a cosigner who meets age of majority requirements in the cosigner’s state of residence
- You’re a U.S. citizen, permanent resident alien or an Eligible Non-Citizen (DACA recipient) applying with an eligible cosigner who is a U.S. citizen or permanent resident alien, or an international student applying with an eligible cosigner who is a U.S. citizen or permanent resident alien
### What can an Abe Law School student loan be used to pay for?
An Abe Law School student loan can be used to pay for up to 100% of the total cost of law school,1 including:
- Tuition and fees
- Room and board (on or off campus)
- Books and supplies
- A laptop or other tech needed for school
- Everyday living expenses while you’re enrolled
### How much can I borrow?
An Abe Law School student loan enables you to borrow from $1,000 up to your school’s certified cost of attendance,1 minus any other aid you’re receiving from funding such as federal loans, grants and scholarships.
### What information do I need to apply?
Applying for an Abe Law School student loan is quick and easy, but having a few things ready can make it even faster:
- Your date of birth and Social Security number
- Mailing and email adress and phone number
- Your school name and grade level as well as expected graduation date
- The amount you’d like to borrow
- Employment and income info (for you and your cosigner, if you have one)23
- A valid ID (like a driver’s license or passport)
If you’re applying with a cosigner, they’ll need to provide similar information. Don’t worry, we’ll walk you through it step by step.
### What happens if I need help making payments later?
Life doesn’t always go as planned. Abe Law School student loans come with built-in flexibility like deferment and forbearance if things get tough after graduation and you need more time.
### Is there a penalty for paying off my loan early?
Nope. You can pay off your loan at any time with no prepayment penalties.
## Find the loan that fits your goals.
No matter where you are headed on your education journey, Abe can help you get there.
- [Undergraduate](https://www.abestudentloans.com/student-loans/undergraduate/)
- [Graduate](https://www.abestudentloans.com/student-loans/graduate/)
- [Law](https://www.abestudentloans.com/student-loans/graduate/law/)
- [MBA](https://www.abestudentloans.com/student-loans/graduate/mba/)
- [Medical](https://www.abestudentloans.com/student-loans/graduate/medical/)
- [Dental](https://www.abestudentloans.com/student-loans/graduate/dental/)
- [Healthcare Professionals](https://www.abestudentloans.com/student-loans/graduate/healthcare-professionals/)
---
### [Graduate](https://www.abestudentloans.com/student-loans/graduate/)
**Published:** May 27, 2025
**Author:** abelending
**Content:**
# Graduate
Student Loans
No application fees, processing fees, or late fees
Four repayment options, five loan terms3
Available to students enrolled full time, part-time, or less than half time
Up to 100% of graduate school expenses covered including tuition, technology, books and more1
Find your rate in minutes2 with no impact to your credit score
[Find My Rate](http://abe.psl.sparrowfi.com)
## Rates that respect your goals.
Whether you’re borrowing solo or with a cosigner, Abe® offers competitive rates designed to support your next move, not just your next semester. Choose the rate type and loan term3 that fits your career timeline, and lock in the financing that keeps you focused on your future.
### Fixed Rates
### 2.08%
#### to 15.58% APR[6](#f6),[7](#f7)
### Variable Rates
### 3.50%
#### to 15.21% APR[6](#f6),[7](#f7)
*Lowest APRs (Annual Percentage Rates) include a 0.25% discount when auto pay is elected.18*
## Apply in minutes with 3 easy steps.
1
### Find your rate2
f
2
### Choose your repayment option and term3
3
### Finish your application and submit
[Find My Rate](http://abe.psl.sparrowfi.com)
Have questions before you take the next step? Check out our [FAQs](https://www.abestudentloans.com/resources/#faq) or [Contact Us](#contact).
## See how Abe stacks up against the Federal Grad PLUS Loan.
[Recent changes to federal student loan programs](/blog/federal-loans/abes-plain-honest-recap-of-the-big-beautiful-bills-impact-on-federal-student-loans/) mean the Federal Grad PLUS Loan began being phased out for new borrowers July 1, 2026. While existing Grad PLUS borrowers can continue under current terms, future graduate students will need to look for alternative ways to finance their education.
An Abe Graduate Loan offers a straightforward, no-fee option with competitive rates and borrower benefits to help cover the cost of a graduate degree when federal aid, scholarships, and grants fall short. Review the key differences between the two programs to see how Abe can help fill the gap.
### Interest Rates
### Fees
### Less than half-time enrollment eligibility
### On-time Payment Discount9
### Cosigner Release13
### In-School Default Protection4
### Abe Graduate Loan
Competitive fixed and variable rates.
No fees, ever. No application, origination, or late fees.
####
####
####
####
### Interest Rates
### Fees
### Less than half-time enrollment eligibility
### On-time Payment Discount9
### Cosigner Release13
### In-School Default Protection4
#### Federal Grad PLUS Loan
Fixed rate of 8.94% for loans disbursed July 1, 2025 – June 30, 2026.
Origination fee of 4.228% deducted from each disbursement.
####
####
####
####










### Already borrowed for undergrad?
### Here’s what to think about before borrowing more.
If you took out loans for your undergraduate degree, adding to that balance for grad school might feel like a big leap. That’s fair. There are a few key things to keep in mind as you plan your next step that can help you feel more confident about adding to your existing loan balance.
#### Look at the big picture.
Grad school is often an investment in higher earning potential. Run the numbers and see how your new degree could impact your long-term financial path, and whether the added debt makes sense for your goals.
#### Understand how your loans fit together.
Your grad loan won’t replace your undergrad loans, but it will stack alongside them. Knowing your total student debt picture (monthly payments, interest rates, timelines) can help you choose the right repayment plan now.
#### Consider applying with a cosigner.
Even if you borrowed solo before, applying with a creditworthy cosigner for a grad school loan could help you qualify for a better rate — saving money in the long run.
#### Keep flexibility in mind.
Grad programs often come with internships, residencies, or temporary lower income. Abe offers in-school repayment options and deferment,3 so you can adjust your plan without falling behind.
## Specialized loans for specialized degrees.
Abe offers tailored loan solutions for your specific career path, so you can focus on building your future instead of worrying about financing it.

### Law
**Learn More**

### MBA
**Learn More**

### Medical
**Learn More**

### Dental
**Learn More**

### Healthcare Professionals
**Learn More**
- [Borrower Benefits](#borrower-benefits)
- [Cosigner Information](#cosigner-information)
- [Repayment Options](#repayment-options)
- [Repayment Terms](#repayment-terms)
- [Payment Relief](#payment-relief)
### Borrower Benefits
### Reduce your rate by up to 0.50% by building a good payment history.
Abe allows you to reduce your rate by 0.25% by electing auto pay18, even while you are enrolled in school, and up to an additional 0.25% interest rate reduction for making on-time principal and interest payments9 during the repayment term.
### 2% Grad Reward8
Upon request after graduating, reduce your principal balance by 2% of your net disbursed loan amount.
### Early Cosigner Release13
Abe recognizes the shared commitment you and your cosigner made when taking out your student loan. That’s why, after just 12 months of on-time principal and interest payments, you can apply to release your cosigner – allowing you to take sole responsibility for the loan moving forward.
[Find My Rate](http://abe.psl.sparrowfi.com)
### Cosigner Information
### A cosigner significantly increases your approval chances.
### 3 out of 4 approved applicants have a cosigner.
You don’t have to have a cosigner to apply for an Abe loan. That said, there are several reasons why it’s a really good idea to have one.
### Applying with a creditworthy cosigner may result in a lower interest rate.
[Learn More About Cosigners](https://www.abestudentloans.com/cosigners/)
### Repayment Options3
IMMEDIATE REPAYMENT
Make full payments in school.
INTEREST ONLY
Pay only interest in school.
FLAT PAYMENT
Make flat partial payments in school.
FULLY DEFERRED
Full payments after you graduate.
### Make full principal and interest payments while you study.
- Start making principal and interest payments right away
- Making higher monthly payments while you are still in school saves you the most money overall
[Find My Rate](http://abe.psl.sparrowfi.com)

### Make only interest payments while in school.
- Interest only payments reduce the long-term cost of your loan
- This is a good option if you can't make full payments while in school but still want to make life easier after you graduate by making smaller monthly payments now
[Find My Rate](http://abe.psl.sparrowfi.com)

### Make $25 payments each month during school to reduce your accrued interest.
- Steadily chip away at your loan's interest by making low, flat monthly payments while you study
- This is a great option if you can't quite afford full interest payments just yet, but still want to start making a dent in the overall cost of your loan right away
[Find My Rate](http://abe.psl.sparrowfi.com)

### Wait to make payments until after you graduate and are earning money.
- Waiting until you graduate before you start making payments allows you to focus on your studies without worrying about loan payments
- Keep in mind interest will continue to accrue on your loan during this time, making this the most expensive option over all
[Find My Rate](http://abe.psl.sparrowfi.com)

### In-School Default Protection4 protects you from default.
If you elect to make interest only or flat payments while in-school but fall short, In-School Default Protection will save you from default by automatically switching you to a deferred payment program. Abe also features an extra year of in-school deferment20 – up to 60 months (5 years) in case it takes a little longer to get your degree.
### Repayment Terms
### Abe has five different loan terms:
#### 5, 7, 10, 15, or 20 years.3
The shorter the term, the more you save on interest payments. Longer terms mean lower monthly payments, but higher overall cost of the loan.
Use the configurator to see how adjusting the length of your loan changes the monthly payment, and then choose the shortest term with a payment amount you’re comfortable making.
[Find My Rate](http://abe.psl.sparrowfi.com)
### Payment Relief
### 6 months of grace and then 6 more.
Once you graduate, you have to look for a job. You may have to move. Buy a car. If you need 6 months before starting repayment, you got it.15 Then if you need 6 more months, that’s fine, too.16
### Past due balances.
Falling behind and accumulating a past-due school balance can happen, particularly during financial emergencies or unexpected circumstances. If this occurs, an Abe loan can be used to cover the outstanding balance within 18 months of the academic period end date.17
### Re-enrollment, medical internships, and residencies.
If you re-enroll in school, or enter a medical internship or residency, we offer deferment options.10
### Health and family first.
If you end up out of work due to illness or go on unpaid FMLA leave, Abe provides up to 12 months of medical forbearance.12
### A safety net just in case.
A lot can happen over the life of a loan. You may lose your job, suffer from a financial hardship,11 be impacted by a natural disaster,22 or be approved for a leave of absence from school.25 Abe is there for you with opportunities for payment relief.
### Extended payment relief.
If you have gone through a reduced payment program and still need relief to get back on your feet, you may be eligible for a term extension of 60 months (5 years), which will lower your monthly payments.21
## Why Borrowers Are Choosing Abe
The Abe student loan experience, told by the people who lived it.
### "Abe was able to get me a great rate on my loan.
The loan process was smooth and I am very happy I was able to work with them.”
Gavin, Verified Borrower

### "I've dealt with a few different loans, but Abe is on a different level.
The entire application process was incredibly smooth. I was able to see my rates with a soft credit pull, which gave me peace of mind right from the start. Customer service is amazing.”
Joe, Verified Borrower

### "Easy process,
fast disbursement.”
Paola, Verified Borrower

### "Abe really helped me when I needed it most.
I didn’t think I would be able to afford college, but I applied for a loan and the process was smooth and manageable.”
Anonymous, Verified Borrower

### "The loan experience was very easy.
I feel the rate was fair. It allowed Isabelle to attend the school of her choice.“
Sean, Verified Borrower

### "Very Helpful
First time navigating school loans for my daughter, and they were very helpful when it came to choosing the right loan for her.“
Jennette, Verified Borrower

## How Abe stacks up.\*
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
### Abe.
####
Up to 12 Months^
5, 7, 10, 15 or 20 Years
####
####
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
#### CollegeAve
####
6 Months
5, 8, 10 or 15 Years
####
####
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
#### Earnest
####
9 Months
5, 7, 10, 12 or 15 Years
####
####
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
#### Sallie Mae
####
6 Months
10 to 15 Years
####
####
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
#### SoFi
####
6 Months
5, 7, 10, 15 or 20 Years
####
####
\*Comparisons based on competitors’ websites (as of 7/27/26).
^6 months grace guaranteed + possible 6 months grace extension.
## Apply in minutes with 3 easy steps.
1
### Find your rate2
f
2
### Choose your repayment option and term3
3
### Finish your application and submit
[Find My Rate](http://abe.psl.sparrowfi.com)
Have questions before you take the next step? Check out our [FAQs](https://www.abestudentloans.com/resources/#faq) or [Contact Us](#contact).
## Abe Graduate Student Loan FAQs
### Who can apply for an Abe Graduate student loan?
If you’re pursuing a graduate or professional degree or certificate program at an eligible school, you can apply24 for an Abe Graduate student loan. You must also meet the following criteria:
- You’re at the legal age of majority, or at least 17 years of age at the time of application if applying with a cosigner who meets age of majority requirements in the cosigner’s state of residence
- You’re a U.S. citizen, permanent resident alien or an Eligible Non-Citizen (DACA recipient) applying with an eligible cosigner who is a U.S. citizen or permanent resident alien, or an international student applying with an eligible cosigner who is a U.S. citizen or permanent resident alien
### What can an Abe Graduate student loan be used to pay for?
An Abe Graduate student loan can be used to pay for up to 100% of the total cost of graduate school expenses,1 including:
- Tuition and fees
- Room and board (on or off campus)
- Books and supplies
- A laptop or other tech needed for school
- Transportation and travel
- Everyday living expenses while you’re enrolled
- Licensing exam fees and prep materials (if approved by your school)
### How much can I borrow?
An Abe Graduate student loan enables you to borrow from $1,000 up to your school’s certified cost of attendance,1 minus any other aid you’re receiving from funding such as federal loans, grants and scholarships.
### What information do I need to apply?
Applying for an Abe Graduate student loan is quick and easy, but having a few things ready can make it even faster:
- Your date of birth and Social Security number
- Mailing and email adress and phone number
- Your school name and grade level as well as expected graduation date
- The amount you’d like to borrow
- Employment and income info (for you and your cosigner, if you have one)23
- A valid ID (like a driver’s license or passport)
If you’re applying with a cosigner, they’ll need to provide similar information. Don’t worry, we’ll walk you through it step by step.
### What happens if I need help making payments later?
Life doesn’t always go as planned. Abe private student loans come with built-in flexibility like deferment and forbearance if things get tough after graduation and you need more time.
### Is there a penalty for paying off my loan early?
Nope. You can pay off your loan at any time with no prepayment penalties.
## Find the loan that fits your goals.
No matter where you are headed on your education journey, Abe can help you get there.
- [Undergraduate](https://www.abestudentloans.com/student-loans/undergraduate/)
- [Graduate](https://www.abestudentloans.com/student-loans/graduate/)
- [Law](https://www.abestudentloans.com/student-loans/graduate/law/)
- [MBA](https://www.abestudentloans.com/student-loans/graduate/mba/)
- [Medical](https://www.abestudentloans.com/student-loans/graduate/medical/)
- [Dental](https://www.abestudentloans.com/student-loans/graduate/dental/)
- [Healthcare Professionals](https://www.abestudentloans.com/student-loans/graduate/healthcare-professionals/)
---
### [Undergraduate](https://www.abestudentloans.com/student-loans/undergraduate/)
**Published:** May 27, 2025
**Author:** abelending
**Content:**
**Enter for a chance to win $1,500† in Abe’s Plain, Honest Scholarship Sweepstakes!**

Every Month Now Through December 31, 2026 we’re giving away $1,500† to undergraduate students and their families to help cover college costs.
NO PURCHASE NECESSARY. Click for Official Rules and complete details.
# Undergraduate
Student Loans
Up to 100% of college expenses covered including tuition, housing, books and more1
No application fees, processing fees, or late fees
Available to students enrolled full time or less than half time
Four repayment options, five loan terms3
Find your rate in minutes2 with no impact to your credit score
[Find My Rate](http://abe.psl.sparrowfi.com)
## Our rates are low.
But there’s more to it.
Opting for an Abe® fixed rate means the rate won’t change for the life of your loan.5 Remember, your actual rate will depend on your, or your cosigner’s, if applicable, credit. Applying with a creditworthy cosigner may result in a lower interest rate.
### Fixed Rates
### 2.08%
#### to 16.58% APR6,7
### Variable Rates
### 3.50%
#### to 16.18% APR6,7
*Lowest APRs (Annual Percentage Rates) include a 0.25% discount when auto pay is elected.18*
## Apply in minutes with 3 easy steps.
1
### Find your rate2
f
2
### Choose your repayment option and term3
3
### Finish your application and submit
[Find My Rate](http://abe.psl.sparrowfi.com)
Have questions before you take the next step? Check out our [FAQs](https://www.abestudentloans.com/resources/#faq) or [Contact Us](#contact).










- [Borrower Benefits](#borrower-benefits)
- [Cosigner Information](#cosigner-information)
- [Repayment Options](#repayment-options)
- [Repayment Terms](#repayment-terms)
- [Payment Relief](#payment-relief)
### Borrower Benefits
### Reduce your rate by up to 0.50% by building a good payment history.
Abe allows you to reduce your rate by 0.25% by electing auto pay18, even while you are enrolled in school, and up to an additional 0.25% interest rate reduction for making on-time principal and interest payments9 during the repayment term.
### 2% Grad Reward8
Upon request after graduating, reduce your principal balance by 2% of your net disbursed loan amount.
### Early Cosigner Release13
Abe recognizes the shared commitment you and your cosigner made when taking out your student loan. That’s why, after just 12 months of on-time principal and interest payments, you can apply to release your cosigner – allowing you to take sole responsibility for the loan moving forward.
[Find My Rate](http://abe.psl.sparrowfi.com)
### Cosigner Information
### A cosigner significantly increases your approval chances.
### 3 out of 4 approved applicants have a cosigner.
You don’t have to have a cosigner to apply for an Abe loan. That said, there are several reasons why it’s a really good idea to have one.
### Applying with a creditworthy cosigner may result in a lower interest rate.
[Learn More About Cosigners](https://www.abestudentloans.com/cosigners/)
### Repayment Options3
IMMEDIATE REPAYMENT
Make full payments in school.
INTEREST ONLY
Pay only interest in school.
FLAT PAYMENT
Make flat partial payments in school.
FULLY DEFERRED
Full payments after you graduate.
### Make full principal and interest payments while you study.
- Start making principal and interest payments right away
- Making higher monthly payments while you are still in school saves you the most money overall
[Find My Rate](http://abe.psl.sparrowfi.com)

### Make only interest payments while in school.
- Interest only payments reduce the long-term cost of your loan
- This is a good option if you can't make full payments while in school but still want to make life easier after you graduate by making smaller monthly payments now
[Find My Rate](http://abe.psl.sparrowfi.com)

### Make $25 payments each month during school to reduce your accrued interest.
- Steadily chip away at your loan's interest by making low, flat monthly payments while you study
- This is a great option if you can't quite afford full interest payments just yet, but still want to start making a dent in the overall cost of your loan right away
[Find My Rate](http://abe.psl.sparrowfi.com)

### Wait to make payments until after you graduate and are earning money.
- Waiting until you graduate before you start making payments allows you to focus on your studies without worrying about loan payments
- Keep in mind interest will continue to accrue on your loan during this time, making this the most expensive option over all
[Find My Rate](http://abe.psl.sparrowfi.com)

### In-School Default Protection4 protects you from default.
If you elect to make interest only or flat payments while in-school but fall short, In-School Default Protection will save you from default by automatically switching you to a deferred payment program. Abe also features an extra year of in-school deferment20 – up to 60 months (5 years) in case it takes a little longer to get your degree.
### Repayment Terms
### Abe has five different loan terms:
#### 5, 7, 10, 15, or 20 years.3
The shorter the term, the more you save on interest payments. Longer terms mean lower monthly payments, but higher overall cost of the loan.
Use the configurator to see how adjusting the length of your loan changes the monthly payment, and then choose the shortest term with a payment amount you’re comfortable making.
[Find My Rate](http://abe.psl.sparrowfi.com)
### Payment Relief
### 6 months of grace and then 6 more.
Once you graduate, you have to look for a job. You may have to move. Buy a car. If you need 6 months before starting repayment, you got it.15 Then if you need 6 more months, that’s fine, too.16
### Past due balances.
Falling behind and accumulating a past-due school balance can happen, particularly during financial emergencies or unexpected circumstances. If this occurs, an Abe loan can be used to cover the outstanding balance within 18 months of the academic period end date.17
### Re-enrollment, medical internships, and residencies.
If you re-enroll in school, or enter a medical internship or residency, we offer deferment options.10
### Health and family first.
If you end up out of work due to illness or go on unpaid FMLA leave, Abe provides up to 12 months of medical forbearance.12
### A safety net just in case.
A lot can happen over the life of a loan. You may lose your job, or suffer from a financial hardship,11 or be impacted by a natural disaster.22 Abe is there for you with opportunities for payment relief.
### Extended payment relief.
If you have gone through a reduced payment program and still need relief to get back on your feet, you may be eligible for a term extension of 60 months (5 years), which will lower your monthly payments.21
## Why Borrowers Are Choosing Abe
The Abe student loan experience, told by the people who lived it.
### "Abe was able to get me a great rate on my loan.
The loan process was smooth and I am very happy I was able to work with them.”
Gavin, Verified Borrower

### "I've dealt with a few different loans, but Abe is on a different level.
The entire application process was incredibly smooth. I was able to see my rates with a soft credit pull, which gave me peace of mind right from the start. Customer service is amazing.”
Joe, Verified Borrower

### "Easy process,
fast disbursement.”
Paola, Verified Borrower

### "Abe really helped me when I needed it most.
I didn’t think I would be able to afford college, but I applied for a loan and the process was smooth and manageable.”
Anonymous, Verified Borrower

### "The loan experience was very easy.
I feel the rate was fair. It allowed Isabelle to attend the school of her choice.“
Sean, Verified Borrower

### "Very Helpful
First time navigating school loans for my daughter, and they were very helpful when it came to choosing the right loan for her.“
Jennette, Verified Borrower

## How Abe stacks up.\*
### Fixed Rates5
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
### Abe.
2.08% to 16.58% APR6,7
####
Up to 12 Months^
5, 7, 10, 15 or 20 Years
####
####
### Fixed Rates5
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
#### Earnest
2.19% to 16.49% APR
####
9 Months
5, 7, 10, 12 or 15 Years
####
####
### Fixed Rates5
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
#### CollegeAve
2.19% to 17.99% APR
####
6 Months
5, 8, 10 or 15 Years
####
####
### Fixed Rates5
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
#### Sallie Mae
2.39% to 17.49% APR
####
6 Months
10 to 15 Years
####
####
### Fixed Rates5
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
#### SoFi
2.45% to 15.99% APR
####
6 Months
5, 7, 10, 15 or 20 Years
####
####
\*Comparisons based on competitors’ websites (as of 7/27/26).
^6 months grace guaranteed + possible 6 months grace extension.
## Apply in minutes with 3 easy steps.
1
### Find your rate2
f
2
### Choose your repayment option and term3
3
### Finish your application and submit
[Find My Rate](http://abe.psl.sparrowfi.com)
Have questions before you take the next step? Check out our [FAQs](https://www.abestudentloans.com/resources/#faq) or [Contact Us](#contact).

## Enter for a chance to win $1,500† for college expenses!
### Now through December 31, 2026, Abe is helping undergraduate students and their families cover college costs.
[Enter Now](https://www.abestudentloans.com/resources/scholarships/undergraduate-college-scholarship-sweepstakes/)
## Abe Undergraduate Student Loan FAQs
### Who can apply for an Abe Undergraduate student loan?
Undergraduate students enrolled in a degree-granting program at an eligible school can apply.24 You must also meet the following criteria:
- You’re at the legal age of majority, or at least 17 years of age at the time of application if applying with a cosigner who meets age of majority requirements in the cosigner’s state of residence
- You’re a U.S. citizen, permanent resident alien or an Eligible Non-Citizen (DACA recipient) applying with an eligible cosigner who is a U.S. citizen or permanent resident alien, or an international student applying with an eligible cosigner who is a U.S. citizen or permanent resident alien
### What can an Abe Undergraduate student loan be used to pay for?
An Abe Undergraduate student loan can be used to pay for up to 100% of the total cost of college expenses,1 including:
- Tuition and fees
- Room and board (on or off campus)
- Books and supplies
- A laptop or other tech needed for school
- Transportation and travel
- Everyday living expenses while you’re enrolled
### How much can I borrow?
An Abe Undergraduate student loan enables you to borrow from $1,000 up to your school’s certified cost of attendance,1 minus any other aid you’re receiving from funding such as federal loans, grants and scholarships.
### What information do I need to apply?
Applying for an Abe Undergraduate student loan is quick and easy, but having a few things ready can make it even faster:
- Your date of birth and Social Security number
- Mailing and email adress and phone number
- Your school name and grade level as well as expected graduation date
- The amount you’d like to borrow
- Employment and income info (for you and your cosigner, if you have one)23
- A valid ID (like a driver’s license or passport)
If you’re applying with a cosigner, they’ll need to provide similar information. Don’t worry, we’ll walk you through it step by step.
### What happens if I need help making payments later?
Life doesn’t always go as planned. Abe Undergraduate student loans come with built-in flexibility like deferment and forbearance if things get tough after graduation and you need more time.
### Is there a penalty for paying off my loan early?
Nope. You can pay off your loan at any time with no prepayment penalties.
## Find the loan that fits your goals.
No matter where you are headed on your education journey, Abe can help you get there.
- [Undergraduate](https://www.abestudentloans.com/student-loans/undergraduate/)
- [Graduate](https://www.abestudentloans.com/student-loans/graduate/)
- [Law](https://www.abestudentloans.com/student-loans/graduate/law/)
- [MBA](https://www.abestudentloans.com/student-loans/graduate/mba/)
- [Medical](https://www.abestudentloans.com/student-loans/graduate/medical/)
- [Dental](https://www.abestudentloans.com/student-loans/graduate/dental/)
- [Healthcare Professionals](https://www.abestudentloans.com/student-loans/graduate/healthcare-professionals/)
---
### [Student Loans](https://www.abestudentloans.com/student-loans/)
**Published:** May 27, 2025
**Author:** abelending
**Content:**
**Enter for a chance to win $1,500† in Abe’s Undergraduate Scholarship Sweepstakes!**
# Student Loans
Cover up to 100% of your college expenses1 with an Abe® private student loan designed with real life in mind. From enrollment through graduation and repayment to whatever life throws your way, Abe offers flexible terms, built-in support and options that fit your unique path to getting a degree.
Undergraduate Fixed Rates
2.08% to 16.58% APR6,7
Undergraduate Variable Rates
3.50% to 16.18% APR6,7
Graduate Fixed Rates
2.08% to 15.58% APR6,7
Graduate Variable Rates
3.50% to 15.21% APR6,7
*Lowest APRs (Annual Percentage Rates) include a 0.25% discount when auto pay is elected.18*
[Find My Rate](http://abe.psl.sparrowfi.com/)
## Loan benefits designed with real life in mind.
No application fees, processing fees, or late fees
Four repayment options, five loan terms3
Available to students enrolled full time, part-time, or less than half time
Up to 100% of college expenses covered including tuition, housing, books and more1
Rate discounts for auto pay18 and making on-time payments9
Reduce your principal balance by 2% upon request after graduation with our Grad Reward8










## Find the loan that fits your goals.
Whether you’re pursuing a graduate degree, certificate, or just a few more credits, Abe offers flexible private student loans for full-time and less than half-time students to help you fund your next step.

### Undergraduate
For undergraduate students enrolled in a bachelor’s or associate’s degree program.
**Learn More**

### Graduate
For graduate students enrolled in a degree or certificate program.
**Learn More**

### Law
For graduate students enrolled in a law degree program.
**Learn More**

### MBA
For graduate students enrolled in an MBA degree program.
**Learn More**

### Medical
For graduate students enrolled in a doctoral degree program: Doctor of Medicine (MD), Osteopathic Medicine (DO), Veterinary Medicine (DVM, VMD), or Podiatric Medicine (PM).
**Learn More**

### Dental
For graduate students enrolled in a dentistry degree program (Pediatric Dentistry, Periodontics, Oral Surgeon etc.).
**Learn More**

### Healthcare Professionals
For graduate students enrolled in a nursing, pharmacy, or allied health professional degree program (e.g., Dietitians, OT, Speech Pathologist, Audiologist, Dental Hygienist etc.).
**Learn More**
## How Abe stacks up.\*
### Fixed Rates5
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
### Abe.
2.08% to 16.58% APR6,7
####
Up to 12 Months^
5, 7, 10, 15 or 20 Years
####
####
### Fixed Rates5
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
#### Earnest
2.19% to 16.49% APR
####
9 Months
5, 7, 10, 12 or 15 Years
####
####
### Fixed Rates5
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
#### CollegeAve
2.19% to 17.99% APR
####
6 Months
5, 8, 10 or 15 Years
####
####
### Fixed Rates5
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
#### Sallie Mae
2.39% to 17.49% APR
####
6 Months
10 to 15 Years
####
####
### Fixed Rates5
### Zero Fees
### Grace Period15,16
### Repayment Terms3
### 2% Grad Reward8
### On-Time Payment Discount9
#### SoFi
2.45% to 15.99% APR
####
6 Months
5, 7, 10, 15 or 20 Years
####
####
\*Comparisons based on competitors’ websites (as of 7/27/26).
^6 months grace guaranteed + possible 6 months grace extension.
## Apply in minutes with 3 easy steps.
1
### Find your rate2
f
2
### Choose your repayment option and term3
3
### Finish your application and submit
[Find My Rate](http://abe.psl.sparrowfi.com)
Have questions before you take the next step? Check out our [FAQs](https://www.abestudentloans.com/resources/#faq) or [Contact Us](#contact).
---
### [Loan Details](https://www.abestudentloans.com/loan-details/)
**Published:** March 11, 2024
**Author:** abelending
**Content:**
**Enter for a chance to win $1,500† in Abe’s Undergraduate Scholarship Sweepstakes!**

# Loan Details
Undergraduate Fixed Rates
2.08% to 16.58% APR6,7
Undergraduate Variable Rates
3.50% to 16.18% APR6,7
Graduate Fixed Rates
2.08% to 15.58% APR6,7
Graduate Variable Rates
3.50% to 15.21% APR6,7
*Lowest APRs include a 0.25% discount when auto pay is elected.18*
## **The only rate that matters is yours.**
### Find your rate in minutes.[2](#f2)
There’s no obligation and it won’t impact your credit.
[Find My Rate](http://abe.psl.sparrowfi.com)
- [How Much Do You Need?](#how-much-do-you-need)
- [Preparing to Apply](#preparing-to-apply)
- [Eligibility](#eligibility)
- [Rate Discounts](#rate-discounts)
- [Qualifying Expenses](#expenses)
- [Options & Terms](#options)
- [Loan Amounts](#loan-amounts)
### How much do you need?
An Abe® student loan is a private student loan, also called a gap loan. Why? Because private student loans can fill the gap between all of your other college financing resources and the total cost of going to school.
To figure out how much you need, add up all your other college financing amounts from federal student and parent loans, scholarships, grants, school financial aid packages, and college savings plans. Subtract the total from your overall annual cost of tuition, room and board, supplies, and expenses — that’s how much you need to fill the gap.
### Preparing to Apply
With Abe, it’s all about preparing you with information. Here’s what you will need to have on hand before you start the application process:
1. Your (and cosigner’s if using) date of birth and SSN
2. Mailing, email addresses, and phone numbers
3. School name, grade level, and expected graduation date
4. Loan amount
5. Income of cosigner (or student if applying alone)23
If you get into the application and realize you’re missing information, simply save what you’ve done and come back to complete the form.
If you’re an international student or DACA recipient, you must apply with a cosigner who is either a U.S. citizen or a permanent resident alien.
### Eligibility
As long as you meet the following criteria, you are eligible to apply for an Abe loan:24
- Enrolled or enrolling in a degree-granting program at an eligible institution
- Reach legal age of majority in your state or be at least 17 years of age at the time of application
- Be a U.S. citizen, permanent resident alien, or an Eligible Non-Citizen (DACA recipient) applying with an eligible cosigner who is a U.S. citizen or permanent resident alien, or an international student applying with an eligible cosigner who is a U.S. citizen or permanent resident alien
- Remember, having a cosigner (parent, grandparent, aunt or uncle, guardian, or mentor) will improve your approval chances
### Rate Discounts
Abe offers two ways to earn rate discounts during the life of your loan.
### Auto Pay
Sign up for auto pay and automatically get a 0.25% discount on your rate.18
### Good Payment Behavior
We’ll reduce your rate by 0.05% for every 6 months of consecutive, on-time principal and interest payments — for a maximum reduction of 0.25%.[9](#f9) This helps you reduce the cost of your loan earlier, which means you can save more over the life of the loan. Other loan providers require you to wait longer until you’ve made more consecutive, on-time payments.
### Qualifying Expenses
You can use your Abe loan to cover up to 100% of college costs.1
Here is a list of qualifying expenses:
- Tuition and fees
- Room and board
- Books and supplies
- Transportation
- Personal expenses
### Options & Terms[3](#f3)
#### In-School Payments
- **Immediate:** Full payments lower the cost of the loan the most
- **Interest Only:** Interest only payments reduce the long-term cost
- **Flat:** Low, flat payments steadily chip away at your balance
#### Deferred
- **Full Deferment:** Wait until you graduate and are earning money to start repayment20
#### Five Different Loan Terms:
- 5, 7, 10, 15, or 20 years3
### Loan Amounts[1](#f1)
Abe lets you borrow as little as $1,000 or up to your school’s total certified cost of attendance, minus any other aid you’re receiving from funding such as federal loans, grants, and scholarships.
As long as your total amount of all student loans doesn’t exceed your program’s aggregate loan limit, you’re good. The limit is $300,000 for Undergraduate programs; $350,000 for Graduate, Graduate Certificate, Law, MBA, and Healthcare Professional programs; and $500,000 for Medical and Dental programs.
---
### [Abe Student Loan Insights](https://www.abestudentloans.com/blog/)
**Published:** November 20, 2025
**Author:** abelending
**Content:**
# Abe Student Loan Insights
#### Featured Article
#### Abe’s Plain, Honest Recap of the Big Beautiful Bill’s Impact on Federal Student Loans
July 30, 2025
[Learn More](https://www.abestudentloans.com/blog/abes-plain-honest-recap-of-the-big-beautiful-bills-impact-on-federal-student-loans/)
#### [Updated for 2026: Which Degrees Count as Professional for Federal Student Loans?](https://www.abestudentloans.com/blog/updated-for-2026-which-degrees-count-as-professional-for-federal-student-loans/)
Last updated: August 2026. This post reflects U.S. Department of Education guidance issued June 29, 2026 and updated July 10, 2026. The list described here is interim and can change while the case is pending. A federal court order on June 24, 2026 changed which...
[read more](https://www.abestudentloans.com/blog/updated-for-2026-which-degrees-count-as-professional-for-federal-student-loans/)
---
### [Abe Home ALT 2 - How Abe Compares](https://www.abestudentloans.com/how-abe-compares/)
**Published:** August 18, 2026
**Author:** abelending
**Content:**
**Enter for a chance to win $1,500† in Abe’s Undergraduate Scholarship Sweepstakes!**
# Plain, honest student loans.
- Available for Undergrad, Grad, and Grad Specialty programs
- Up to 100% of college expenses covered,1 with no fees… ever
- Find your rate in minutes[2](#f2) with no impact on your credit score
### Undergraduate Fixed Rates
#### 2.08% to 16.58% APR[6](#f6),[7](#f7)
### Graduate Fixed Rates
#### 2.08% to 15.58% APR[6](#f6),[7](#f7)
[Find My Rate](http://abe.psl.sparrowfi.com)
*Lowest Annual Percentage Rates include a 0.25% discount when auto pay is elected.18*
## Compare Abe® Features & Benefits\*
### Abe.
#### Sallie Mae
#### CollegeAve
### Zero Fees
####
####
####
### Grace Period15,16
Up to 12 Months^
6 Months
6 Months
### Past Due Balances17
18 Months
12 Months
12 Months
### On-Time Discount9
####
####
####
### Grad Reward8
####
####
####
### In-School Default Protection4
####
####
####
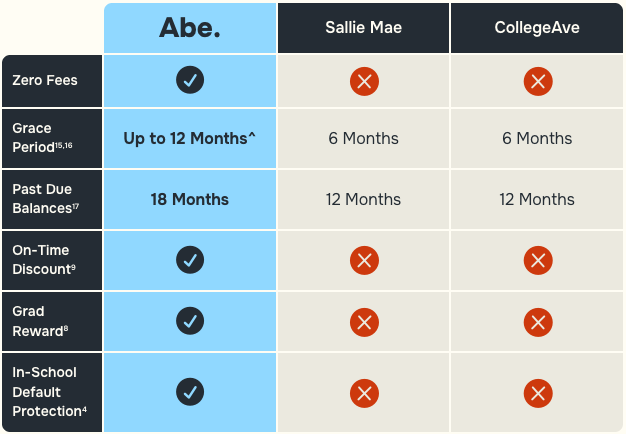
*\*Comparisons based on competitors’ websites (as of 7/27/26).*
*^6 months grace guaranteed + possible 6 months grace extension.*










### No Fees
No application fees, origination fees, late payment fees, forbearance fees, or fees to pay by debit card.
### 2% Grad Reward8
Upon request after graduating, reduce your principal balance by 2% of your net disbursed loan amount.
### Fast-Track Your Rate Reduction
For every six months of on-time principal and interest payments, Abe® lowers your rate by 0.05% — for a total reduction of up to 0.25%.[9](#f9) Unlike other providers that require you to make years of payments first,\* Abe lets you start to lower your rate (and build a good credit history) much sooner.
g
### 5, 7, 10, 15, or 20 Years3
The term, or duration, impacts both the cost of a loan and your monthly payment amount. The longer the loan, the more interest you’ll pay but the lower your monthly cost will be. Abe has five terms — giving you more options for weighing the length/cost of your loan against a monthly payment you’re comfortable making.
### 6 Payment Relief Options
Abe is there for you with six different payment relief options that let you defer payments according to your education goals and timeline. For example, you may enroll in a medical internship or residency10 or it may take longer for you to get on your financial feet after you graduate. You can also defer payments if you lose your job11 or suffer a serious illness.12
### Early Cosigner Release13
Abe recognizes the shared commitment you and your cosigner make when taking out your student loan. That’s why, after just 12 months of on-time principal and interest payments, you can apply to release your cosigner – allowing you to take sole responsibility for the loan moving forward.
### Stress Less, Save More Time With the Returning Borrower Advantage14
[Reapply Now](http://abe.psl.sparrowfi.com)
When you come back for another Abe student loan, you not only have a higher chance of approval — you likely won’t need to resubmit income documentation again. Less paperwork, less waiting. Just a straightforward path to the money you need.
\*Comparisons based on competitors’ websites as of 7/24/26.
## Find the loan that fits your goals.
No matter where you are headed on your education journey, Abe can help you get there.

### Undergraduate
For undergraduate students enrolled in a bachelor’s or associate’s degree program.
**Learn More**

### Graduate
For graduate students enrolled in a degree or certificate program.
**Learn More**

### Law
For graduate students enrolled in a law degree program.
**Learn More**

### MBA
For graduate students enrolled in an MBA degree program.
**Learn More**

### Medical
For graduate students enrolled in a doctoral degree program: Doctor of Medicine (MD), Osteopathic Medicine (DO), Veterinary Medicine (DVM, VMD), or Podiatric Medicine (PM).
**Learn More**

### Dental
For graduate students enrolled in a dentistry degree program (Pediatric Dentistry, Periodontics, Oral Surgeon etc.).
**Learn More**

### Healthcare Professionals
For graduate students enrolled in a nursing, pharmacy, or allied health professional degree program (e.g., Dietitians, OT, Speech Pathologist, Audiologist, Dental Hygienist etc.).
**Learn More**
## Why Borrowers Are Choosing Abe
The Abe student loan experience, told by the people who lived it.
### "Abe was able to get me a great rate on my loan.
The loan process was smooth and I am very happy I was able to work with them.”
Gavin, Verified Borrower

### "I've dealt with a few different loans, but Abe is on a different level.
The entire application process was incredibly smooth. I was able to see my rates with a soft credit pull, which gave me peace of mind right from the start. Customer service is amazing.”
Joe, Verified Borrower

### "Easy process,
fast disbursement.”
Paola, Verified Borrower

### "Abe really helped me when I needed it most.
I didn’t think I would be able to afford college, but I applied for a loan and the process was smooth and manageable.”
Anonymous, Verified Borrower

### "The loan experience was very easy.
I feel the rate was fair. It allowed Isabelle to attend the school of her choice.“
Sean, Verified Borrower

### "Very Helpful
First time navigating school loans for my daughter, and they were very helpful when it came to choosing the right loan for her.“
Jennette, Verified Borrower

## How Abe stacks up.\*
### Zero Fees
### Grace Period15,16
### Repayment Options3
### Repayment Terms3
### Past Due Balances17
### On-Time Discount9
### Graduate Loans
### Graduate Certificate Loans
### Grad Reward8
### In-School Default Protection4
### Abe.
####
Up to 12 Months^
4
5, 7, 10, 15, & 20 Years
18 Months
####
####
####
####
####
### Zero Fees
### Grace Period15,16
### Repayment Options3
### Repayment Terms3
### Past Due Balances17
### On-Time Discount9
### Graduate Loans
### Graduate Certificate Loans
### Grad Reward8
### In-School Default Protection4
#### Sallie Mae
####
6 Months
3
10 to 15 Years
12 Months
####
####
####
####
####
### Zero Fees
### Grace Period15,16
### Repayment Options3
### Repayment Terms3
### Past Due Balances17
### On-Time Discount9
### Graduate Loans
### Graduate Certificate Loans
### Grad Reward8
### In-School Default Protection4
#### SoFi
####
6 Months
4
5, 7, 10, 15 & 20 Years
12 Months
####
####
####
####
####
### Zero Fees
### Grace Period15,16
### Repayment Options3
### Repayment Terms3
### Past Due Balances17
### On-Time Discount9
### Graduate Loans
### Graduate Certificate Loans
### Grad Reward8
### In-School Default Protection4
#### CollegeAve
####
6 Months
4
5, 8, 10, & 15 Years
12 Months
####
####
####
####
####
### Zero Fees
### Grace Period15,16
### Repayment Options3
### Repayment Terms3
### Past Due Balances17
### On-Time Discount9
### Graduate Loans
### Graduate Certificate Loans
### Grad Reward8
### In-School Default Protection4
#### Earnest
####
9 Months
4
5, 7, 10, 12, & 15 Years
12 Months
####
####
####
####
####
\*Comparisons based on competitors’ websites (as of 7/27/26).
^6 months grace guaranteed + possible 6 months grace extension.
- [Rate Discounts](#rate-discounts)
- [Student Loans](#degree-programs)
- [International](#international)
- [Options & Terms](#options-terms)
- [Payment Relief](#payment-relief)
Rate Discounts
Rate Discounts
## Lowering your rate. &
### Reduce your rate by up to 0.50% by building a good payment history.
Abe allows you to reduce your rate by 0.25% by electing auto pay18, even while you are enrolled in school, and up to an additional 0.25% interest rate reduction for making on-time principal and interest payments9 during the repayment term.
[Find My Rate](http://abe.psl.sparrowfi.com)
Student Loans
Student Loans
## [Student loans custom-fit to your degree. &](/student-loans)
### [Undergraduate Student Loans $](https://www.abestudentloans.com/student-loans/undergraduate)
An Abe student loan can be used to earn an associate, B.A., or B.S. degree at approved private and public universities and colleges. The aggregate loan limit1 for undergraduate students is $300,000.
### Post-Bachelor Graduate Certificates
Post-bachelor Graduate Certificate students can use an Abe loan to cover the costs associated with specialized certificates in their field and start their careers at a higher level. The aggregate loan limit1 for Graduate Certificate students is $350,000.
### [Graduate Student Loans $]()
Whether you're earning a master's, doctoral, or professional degree, Abe's graduate student loans offer the same benefits as our undergraduate loans.
Advanced degrees often require more funding. Abe's aggregate loan limit1 is $350,000 for Graduate, Law, MBA, and Healthcare Professional programs, and $500,000 for Medical and Dental programs.
### Less Than Half-Time Students
An Abe student loan can help students who just need a few more credits to finish their degree, including summer and Jan Plan courses.
International
International
## We welcome the world.19
### U.S. Citizens
### Permanent Residents
### DACA Recipients with a U.S. Cosigner
### International Students with a U.S. Cosigner
Options & Terms
Options & Terms
## More repayment options, more power to the individual.
Determining the right Abe loan for you means figuring out your ideal total loan cost vs. monthly payment amount.
Whether you can start repaying while in school or if you need to defer until after graduation, the rule of thumb is the shorter the loan term, the less interest you’ll pay and the lower the total cost of your loan.
Abe has five different loan terms: 5, 7, 10, 15, or 20 years.[3](#f3) Use the configurator in our online application to see how adjusting the length of your loan changes the monthly payment, and then choose the shortest term with a payment amount you’re comfortable making.
[Find My Rate](http://abe.psl.sparrowfi.com)
### In-School Payments[3](#f3)
- Making principal and interest payments lowers the cost of the loan the most
- Interest only payments reduce the long-term cost
- Low, flat payments steadily chip away at your balance
### Deferred Payments
- Wait until you graduate to start repayment20
### Five Different Loan Terms:
- 5, 7, 10, 15, or 20 years[3](#f3)
### In-School Default Protection4 saves you from default.
If you elect to make interest only or flat payments while in-school but fall short, In-School Default Protection will save you from default by automatically switching you to a deferred payment program. Abe also features an extra year of in-school deferment20 – up to 60 months (5 years) in case it takes a little longer to get your degree.
Payment Relief
Payment Relief
## Life happens. That's okay.
### Most students don't worry about borrowing money. They worry about paying it back.
### What if you need more time before starting repayment? What if life throws you a curveball?
### 6 months of grace and then 6 more.
Once you graduate, you have to look for a job. You may have to move. Buy a car. If you need 6 months before starting repayment, you got it.15 Then if you need 6 more months, that’s fine, too.16
### Health and family first.
If you end up out of work due to illness or go on unpaid FMLA leave, Abe provides up to 12 months of medical forbearance.12
### Re-enrollment, medical internships, and residencies.
If you re-enroll in school, or enter a medical internship or residency, we offer deferment options.10
### Extended payment relief.
If you have gone through a reduced payment program and still need relief to get back on your feet, you may be eligible for a term extension of 60 months (5 years), which will lower your monthly payments.21
### A safety net just in case.
A lot can happen over the life of a loan. You may lose your job, or suffer from a financial hardship,11 or be impacted by a natural disaster.22 Abe is there for you with opportunities for payment relief.
### Past-due balances.
Falling behind and accumulating a past-due school balance can happen, particularly during financial emergencies or unexpected circumstances. If this occurs, an Abe loan can be used to cover the outstanding balance within 18 months of the academic period end date.17
## Enter for a chance to win $1,500† for undergraduate college expenses!
### Every month through December 31, 2026, Abe is helping undergraduate students and their families cover college costs.
[Enter Now](https://www.abestudentloans.com/resources/scholarships/undergraduate-college-scholarship-sweepstakes/)
## A Plain, Honest Guide to Private Student Loans
Abe believes that if you give people the honest, straightforward information they need to make good decisions, they will. That’s why we created the Plain, Honest Guide to Private Student Loans and invite you to download it here.
[Download Our Guide](/resources/#student-loan-guide)

---
### [Abe Home ALT 1 - Cover College Costs](https://www.abestudentloans.com/cover-college-costs/)
**Published:** August 18, 2026
**Author:** abelending
**Content:**
**Enter for a chance to win $1,500† in Abe’s Undergraduate Scholarship Sweepstakes!**
# Plain, honest student loans.
- Find your rate in minutes[2](#f2) with no impact on your credit score
- Four repayment options, five loan terms[3](#f3)
- [In-School Default Protection](#options-terms)[4 ](#f4)saves you from default if you fall short while making payments in-school[](#f4)
### Undergraduate Fixed Rates
#### 2.08% to 16.58% APR[6](#f6),[7](#f7)
### Graduate Fixed Rates
#### 2.08% to 15.58% APR[6](#f6),[7](#f7)
[Find My Rate](http://abe.psl.sparrowfi.com)
*Lowest Annual Percentage Rates include a 0.25% discount when auto pay is elected.18*
## Up to 100% of college expenses covered,1 with no fees… ever.











### No Fees
No application fees, origination fees, late payment fees, forbearance fees, or fees to pay by debit card.
### 2% Grad Reward8
Upon request after graduating, reduce your principal balance by 2% of your net disbursed loan amount.
### Fast-Track Your Rate Reduction
For every six months of on-time principal and interest payments, Abe® lowers your rate by 0.05% — for a total reduction of up to 0.25%.[9](#f9) Unlike other providers that require you to make years of payments first,\* Abe lets you start to lower your rate (and build a good credit history) much sooner.
g
### 5, 7, 10, 15, or 20 Years3
The term, or duration, impacts both the cost of a loan and your monthly payment amount. The longer the loan, the more interest you’ll pay but the lower your monthly cost will be. Abe has five terms — giving you more options for weighing the length/cost of your loan against a monthly payment you’re comfortable making.
### 6 Payment Relief Options
Abe is there for you with six different payment relief options that let you defer payments according to your education goals and timeline. For example, you may enroll in a medical internship or residency10 or it may take longer for you to get on your financial feet after you graduate. You can also defer payments if you lose your job11 or suffer a serious illness.12
### Early Cosigner Release13
Abe recognizes the shared commitment you and your cosigner make when taking out your student loan. That’s why, after just 12 months of on-time principal and interest payments, you can apply to release your cosigner – allowing you to take sole responsibility for the loan moving forward.
### Stress Less, Save More Time With the Returning Borrower Advantage14
[Reapply Now](http://abe.psl.sparrowfi.com)
When you come back for another Abe student loan, you not only have a higher chance of approval — you likely won’t need to resubmit income documentation again. Less paperwork, less waiting. Just a straightforward path to the money you need.
\*Comparisons based on competitors’ websites as of 7/24/26.
## Find the loan that fits your goals.
No matter where you are headed on your education journey, Abe can help you get there.

### Undergraduate
For undergraduate students enrolled in a bachelor’s or associate’s degree program.
**Learn More**

### Graduate
For graduate students enrolled in a degree or certificate program.
**Learn More**

### Law
For graduate students enrolled in a law degree program.
**Learn More**

### MBA
For graduate students enrolled in an MBA degree program.
**Learn More**

### Medical
For graduate students enrolled in a doctoral degree program: Doctor of Medicine (MD), Osteopathic Medicine (DO), Veterinary Medicine (DVM, VMD), or Podiatric Medicine (PM).
**Learn More**

### Dental
For graduate students enrolled in a dentistry degree program (Pediatric Dentistry, Periodontics, Oral Surgeon etc.).
**Learn More**

### Healthcare Professionals
For graduate students enrolled in a nursing, pharmacy, or allied health professional degree program (e.g., Dietitians, OT, Speech Pathologist, Audiologist, Dental Hygienist etc.).
**Learn More**
## Why Borrowers Are Choosing Abe
The Abe student loan experience, told by the people who lived it.
### "Abe was able to get me a great rate on my loan.
The loan process was smooth and I am very happy I was able to work with them.”
Gavin, Verified Borrower

### "I've dealt with a few different loans, but Abe is on a different level.
The entire application process was incredibly smooth. I was able to see my rates with a soft credit pull, which gave me peace of mind right from the start. Customer service is amazing.”
Joe, Verified Borrower

### "Easy process,
fast disbursement.”
Paola, Verified Borrower

### "Abe really helped me when I needed it most.
I didn’t think I would be able to afford college, but I applied for a loan and the process was smooth and manageable.”
Anonymous, Verified Borrower

### "The loan experience was very easy.
I feel the rate was fair. It allowed Isabelle to attend the school of her choice.“
Sean, Verified Borrower

### "Very Helpful
First time navigating school loans for my daughter, and they were very helpful when it came to choosing the right loan for her.“
Jennette, Verified Borrower

## How Abe stacks up.\*
### Zero Fees
### Grace Period15,16
### Repayment Options3
### Repayment Terms3
### Past Due Balances17
### On-Time Discount9
### Graduate Loans
### Graduate Certificate Loans
### Grad Reward8
### In-School Default Protection4
### Abe.
####
Up to 12 Months^
4
5, 7, 10, 15, & 20 Years
18 Months
####
####
####
####
####
### Zero Fees
### Grace Period15,16
### Repayment Options3
### Repayment Terms3
### Past Due Balances17
### On-Time Discount9
### Graduate Loans
### Graduate Certificate Loans
### Grad Reward8
### In-School Default Protection4
#### Sallie Mae
####
6 Months
3
10 to 15 Years
12 Months
####
####
####
####
####
### Zero Fees
### Grace Period15,16
### Repayment Options3
### Repayment Terms3
### Past Due Balances17
### On-Time Discount9
### Graduate Loans
### Graduate Certificate Loans
### Grad Reward8
### In-School Default Protection4
#### SoFi
####
6 Months
4
5, 7, 10, 15 & 20 Years
12 Months
####
####
####
####
####
### Zero Fees
### Grace Period15,16
### Repayment Options3
### Repayment Terms3
### Past Due Balances17
### On-Time Discount9
### Graduate Loans
### Graduate Certificate Loans
### Grad Reward8
### In-School Default Protection4
#### CollegeAve
####
6 Months
4
5, 8, 10, & 15 Years
12 Months
####
####
####
####
####
### Zero Fees
### Grace Period15,16
### Repayment Options3
### Repayment Terms3
### Past Due Balances17
### On-Time Discount9
### Graduate Loans
### Graduate Certificate Loans
### Grad Reward8
### In-School Default Protection4
#### Earnest
####
9 Months
4
5, 7, 10, 12, & 15 Years
12 Months
####
####
####
####
####
\*Comparisons based on competitors’ websites (as of 7/27/26).
^6 months grace guaranteed + possible 6 months grace extension.
- [Rate Discounts](#rate-discounts)
- [Student Loans](#degree-programs)
- [International](#international)
- [Options & Terms](#options-terms)
- [Payment Relief](#payment-relief)
Rate Discounts
Rate Discounts
## Lowering your rate. &
### Reduce your rate by up to 0.50% by building a good payment history.
Abe allows you to reduce your rate by 0.25% by electing auto pay18, even while you are enrolled in school, and up to an additional 0.25% interest rate reduction for making on-time principal and interest payments9 during the repayment term.
[Find My Rate](http://abe.psl.sparrowfi.com)
Student Loans
Student Loans
## [Student loans custom-fit to your degree. &](/student-loans)
### [Undergraduate Student Loans $](https://www.abestudentloans.com/student-loans/undergraduate)
An Abe student loan can be used to earn an associate, B.A., or B.S. degree at approved private and public universities and colleges. The aggregate loan limit1 for undergraduate students is $300,000.
### Post-Bachelor Graduate Certificates
Post-bachelor Graduate Certificate students can use an Abe loan to cover the costs associated with specialized certificates in their field and start their careers at a higher level. The aggregate loan limit1 for Graduate Certificate students is $350,000.
### [Graduate Student Loans $]()
Whether you're earning a master's, doctoral, or professional degree, Abe's graduate student loans offer the same benefits as our undergraduate loans.
Advanced degrees often require more funding. Abe's aggregate loan limit1 is $350,000 for Graduate, Law, MBA, and Healthcare Professional programs, and $500,000 for Medical and Dental programs.
### Less Than Half-Time Students
An Abe student loan can help students who just need a few more credits to finish their degree, including summer and Jan Plan courses.
International
International
## We welcome the world.19
### U.S. Citizens
### Permanent Residents
### DACA Recipients with a U.S. Cosigner
### International Students with a U.S. Cosigner
Options & Terms
Options & Terms
## More repayment options, more power to the individual.
Determining the right Abe loan for you means figuring out your ideal total loan cost vs. monthly payment amount.
Whether you can start repaying while in school or if you need to defer until after graduation, the rule of thumb is the shorter the loan term, the less interest you’ll pay and the lower the total cost of your loan.
Abe has five different loan terms: 5, 7, 10, 15, or 20 years.[3](#f3) Use the configurator in our online application to see how adjusting the length of your loan changes the monthly payment, and then choose the shortest term with a payment amount you’re comfortable making.
[Find My Rate](http://abe.psl.sparrowfi.com)
### In-School Payments[3](#f3)
- Making principal and interest payments lowers the cost of the loan the most
- Interest only payments reduce the long-term cost
- Low, flat payments steadily chip away at your balance
### Deferred Payments
- Wait until you graduate to start repayment20
### Five Different Loan Terms:
- 5, 7, 10, 15, or 20 years[3](#f3)
### In-School Default Protection4 saves you from default.
If you elect to make interest only or flat payments while in-school but fall short, In-School Default Protection will save you from default by automatically switching you to a deferred payment program. Abe also features an extra year of in-school deferment20 – up to 60 months (5 years) in case it takes a little longer to get your degree.
Payment Relief
Payment Relief
## Life happens. That's okay.
### Most students don't worry about borrowing money. They worry about paying it back.
### What if you need more time before starting repayment? What if life throws you a curveball?
### 6 months of grace and then 6 more.
Once you graduate, you have to look for a job. You may have to move. Buy a car. If you need 6 months before starting repayment, you got it.15 Then if you need 6 more months, that’s fine, too.16
### Health and family first.
If you end up out of work due to illness or go on unpaid FMLA leave, Abe provides up to 12 months of medical forbearance.12
### Re-enrollment, medical internships, and residencies.
If you re-enroll in school, or enter a medical internship or residency, we offer deferment options.10
### Extended payment relief.
If you have gone through a reduced payment program and still need relief to get back on your feet, you may be eligible for a term extension of 60 months (5 years), which will lower your monthly payments.21
### A safety net just in case.
A lot can happen over the life of a loan. You may lose your job, or suffer from a financial hardship,11 or be impacted by a natural disaster.22 Abe is there for you with opportunities for payment relief.
### Past-due balances.
Falling behind and accumulating a past-due school balance can happen, particularly during financial emergencies or unexpected circumstances. If this occurs, an Abe loan can be used to cover the outstanding balance within 18 months of the academic period end date.17
## Enter for a chance to win $1,500† for undergraduate college expenses!
### Every month through December 31, 2026, Abe is helping undergraduate students and their families cover college costs.
[Enter Now](https://www.abestudentloans.com/resources/scholarships/undergraduate-college-scholarship-sweepstakes/)
## A Plain, Honest Guide to Private Student Loans
Abe believes that if you give people the honest, straightforward information they need to make good decisions, they will. That’s why we created the Plain, Honest Guide to Private Student Loans and invite you to download it here.
[Download Our Guide](/resources/#student-loan-guide)

---
### [Student Loan Professor](https://www.abestudentloans.com/student-loan-professor/)
**Published:** April 19, 2026
**Author:** abelending
**Content:**
**Enter for a chance to win $1,500† in Abe’s Undergraduate Scholarship Sweepstakes!**
# Plain, honest student loans.
- Available for Undergrad, Grad, and Grad Specialty programs
- Up to 100% of college expenses covered[1](#f1)
- No application fees, processing fees, or late fees
- Find your rate in minutes[2](#f2) with no impact on your credit score
- Four repayment options, five loan terms[3](#f3)
- [In-School Default Protection](#options-terms)[4 ](#f4)saves you from default if you fall short while making payments in-school
[Find My Rate](http://abe.psl.sparrowfi.com)
## Our rates are low.
But there’s more to it.
Opting for a fixed rate means the rate won’t change for the life of your loan.[5](#f5) Remember, your actual rate will depend on your, or your cosigner’s, if applicable, credit. Applying with a creditworthy cosigner may result in a lower interest rate.
Undergraduate Fixed Rates\*
Abe.
2.08% – 16.58% APR6,7
Earnest
2.19% – 16.49% APR
College Ave
2.19% – 17.99% APR
Sallie Mae
2.39% – 17.49% APR
SoFi
2.45% – 15.99% APR
*\*Comparisons based on competitors’ websites (as of 7/27/26).
Lowest Annual Percentage Rates include a 0.25% discount when auto pay is elected.18*










### No Fees
No application fees, origination fees, late payment fees, forbearance fees, or fees to pay by debit card.
### 2% Grad Reward8
Upon request after graduating, reduce your principal balance by 2% of your net disbursed loan amount.
### Fast-Track Your Rate Reduction
For every six months of on-time principal and interest payments, Abe® lowers your rate by 0.05% — for a total reduction of up to 0.25%.[9](#f9) Unlike other providers that require you to make years of payments first,\* Abe lets you start to lower your rate (and build a good credit history) much sooner.
g
### 5, 7, 10, 15, or 20 Years3
The term, or duration, impacts both the cost of a loan and your monthly payment amount. The longer the loan, the more interest you’ll pay but the lower your monthly cost will be. Abe has five terms — giving you more options for weighing the length/cost of your loan against a monthly payment you’re comfortable making.
### 6 Payment Relief Options
Abe is there for you with six different payment relief options that let you defer payments according to your education goals and timeline. For example, you may enroll in a medical internship or residency10 or it may take longer for you to get on your financial feet after you graduate. You can also defer payments if you lose your job11 or suffer a serious illness.12
### Early Cosigner Release13
Abe recognizes the shared commitment you and your cosigner make when taking out your student loan. That’s why, after just 12 months of on-time principal and interest payments, you can apply to release your cosigner – allowing you to take sole responsibility for the loan moving forward.
### Stress Less, Save More Time With the Returning Borrower Advantage14
[Reapply Now](http://abe.psl.sparrowfi.com)
When you come back for another Abe student loan, you not only have a higher chance of approval — you likely won’t need to resubmit income documentation again. Less paperwork, less waiting. Just a straightforward path to the money you need.
\*Comparisons based on competitors’ websites as of 7/27/26.
## Find the loan that fits your goals.
No matter where you are headed on your education journey, Abe can help you get there.

### Undergraduate
For undergraduate students enrolled in a bachelor’s or associate’s degree program.
**Learn More**

### Graduate
For graduate students enrolled in a degree or certificate program.
**Learn More**

### Law
For graduate students enrolled in a law degree program.
**Learn More**

### MBA
For graduate students enrolled in an MBA degree program.
**Learn More**

### Medical
For graduate students enrolled in a doctoral degree program: Doctor of Medicine (MD), Osteopathic Medicine (DO), Veterinary Medicine (DVM, VMD), or Podiatric Medicine (PM).
**Learn More**

### Dental
For graduate students enrolled in a dentistry degree program (Pediatric Dentistry, Periodontics, Oral Surgeon etc.).
**Learn More**

### Healthcare Professionals
For graduate students enrolled in a nursing, pharmacy, or allied health professional degree program (e.g., Dietitians, OT, Speech Pathologist, Audiologist, Dental Hygienist etc.).
**Learn More**
## Why Borrowers Are Choosing Abe
The Abe student loan experience, told by the people who lived it.
### "Abe was able to get me a great rate on my loan.
The loan process was smooth and I am very happy I was able to work with them.”
Gavin, Verified Borrower

### "I've dealt with a few different loans, but Abe is on a different level.
The entire application process was incredibly smooth. I was able to see my rates with a soft credit pull, which gave me peace of mind right from the start. Customer service is amazing.”
Joe, Verified Borrower

### "Easy process,
fast disbursement.”
Paola, Verified Borrower

### "Abe really helped me when I needed it most.
I didn’t think I would be able to afford college, but I applied for a loan and the process was smooth and manageable.”
Anonymous, Verified Borrower

### "The loan experience was very easy.
I feel the rate was fair. It allowed Isabelle to attend the school of her choice.“
Sean, Verified Borrower

### "Very Helpful
First time navigating school loans for my daughter, and they were very helpful when it came to choosing the right loan for her.“
Jennette, Verified Borrower

## How Abe stacks up.\*
### Zero Fees
### Grace Period15,16
### Repayment Options3
### Repayment Terms3
### Past Due Balances17
### On-Time Discount9
### Graduate Loans
### Graduate Certificate Loans
### Grad Reward8
### In-School Default Protection4
### Abe.
####
Up to 12 Months^
4
5, 7, 10, 15, & 20 Years
18 Months
####
####
####
####
####
### Zero Fees
### Grace Period15,16
### Repayment Options3
### Repayment Terms3
### Past Due Balances17
### On-Time Discount9
### Graduate Loans
### Graduate Certificate Loans
### Grad Reward8
### In-School Default Protection4
#### Sallie Mae
####
6 Months
3
10 to 15 Years
12 Months
####
####
####
####
####
### Zero Fees
### Grace Period15,16
### Repayment Options3
### Repayment Terms3
### Past Due Balances17
### On-Time Discount9
### Graduate Loans
### Graduate Certificate Loans
### Grad Reward8
### In-School Default Protection4
#### SoFi
####
6 Months
4
5, 7, 10, 15 & 20 Years
12 Months
####
####
####
####
####
### Zero Fees
### Grace Period15,16
### Repayment Options3
### Repayment Terms3
### Past Due Balances17
### On-Time Discount9
### Graduate Loans
### Graduate Certificate Loans
### Grad Reward8
### In-School Default Protection4
#### CollegeAve
####
6 Months
4
5, 8, 10, & 15 Years
12 Months
####
####
####
####
####
### Zero Fees
### Grace Period15,16
### Repayment Options3
### Repayment Terms3
### Past Due Balances17
### On-Time Discount9
### Graduate Loans
### Graduate Certificate Loans
### Grad Reward8
### In-School Default Protection4
#### Earnest
####
9 Months
4
5, 7, 10, 12, & 15 Years
12 Months
####
####
####
####
####
\*Comparisons based on competitors’ websites (as of 7/27/26).
^6 months grace guaranteed + possible 6 months grace extension.
- [Rate Discounts](#rate-discounts)
- [Student Loans](#degree-programs)
- [International](#international)
- [Options & Terms](#options-terms)
- [Payment Relief](#payment-relief)
Rate Discounts
Rate Discounts
## Lowering your rate. &
### Reduce your rate by up to 0.50% by building a good payment history.
Abe allows you to reduce your rate by 0.25% by electing auto pay18, even while you are enrolled in school, and up to an additional 0.25% interest rate reduction for making on-time principal and interest payments9 during the repayment term.
[Find My Rate](http://abe.psl.sparrowfi.com)
Student Loans
Student Loans
## [Student loans custom-fit to your degree. &](/student-loans)
### [Undergraduate Student Loans $](https://www.abestudentloans.com/student-loans/undergraduate)
An Abe student loan can be used to earn an associate, B.A., or B.S. degree at approved private and public universities and colleges. The aggregate loan limit1 for undergraduate students is $300,000.
### Post-Bachelor Graduate Certificates
Post-bachelor Graduate Certificate students can use an Abe loan to cover the costs associated with specialized certificates in their field and start their careers at a higher level. The aggregate loan limit1 for Graduate Certificate students is $350,000.
### [Graduate Student Loans $]()
Whether you're earning a master's, doctoral, or professional degree, Abe's graduate student loans offer the same benefits as our undergraduate loans.
Advanced degrees often require more funding. Abe's aggregate loan limit1 is $350,000 for Graduate, Law, MBA, and Healthcare Professional programs, and $500,000 for Medical and Dental programs.
### Less Than Half-Time Students
An Abe student loan can help students who just need a few more credits to finish their degree, including summer and Jan Plan courses.
International
International
## We welcome the world.19
### U.S. Citizens
### Permanent Residents
### DACA Recipients with a U.S. Cosigner
### International Students with a U.S. Cosigner
Options & Terms
Options & Terms
## More repayment options, more power to the individual.
Determining the right Abe loan for you means figuring out your ideal total loan cost vs. monthly payment amount.
Whether you can start repaying while in school or if you need to defer until after graduation, the rule of thumb is the shorter the loan term, the less interest you’ll pay and the lower the total cost of your loan.
Abe has five different loan terms: 5, 7, 10, 15, or 20 years.[3](#f3) Use the configurator in our online application to see how adjusting the length of your loan changes the monthly payment, and then choose the shortest term with a payment amount you’re comfortable making.
[Find My Rate](http://abe.psl.sparrowfi.com)
### In-School Payments[3](#f3)
- Making principal and interest payments lowers the cost of the loan the most
- Interest only payments reduce the long-term cost
- Low, flat payments steadily chip away at your balance
### Deferred Payments
- Wait until you graduate to start repayment20
### Five Different Loan Terms:
- 5, 7, 10, 15, or 20 years[3](#f3)
### In-School Default Protection4 saves you from default.
If you elect to make interest only or flat payments while in-school but fall short, In-School Default Protection will save you from default by automatically switching you to a deferred payment program. Abe also features an extra year of in-school deferment20 – up to 60 months (5 years) in case it takes a little longer to get your degree.
Payment Relief
Payment Relief
## Life happens. That's okay.
### Most students don't worry about borrowing money. They worry about paying it back.
### What if you need more time before starting repayment? What if life throws you a curveball?
### 6 months of grace and then 6 more.
Once you graduate, you have to look for a job. You may have to move. Buy a car. If you need 6 months before starting repayment, you got it.15 Then if you need 6 more months, that’s fine, too.16
### Health and family first.
If you end up out of work due to illness or go on unpaid FMLA leave, Abe provides up to 12 months of medical forbearance.12
### Re-enrollment, medical internships, and residencies.
If you re-enroll in school, or enter a medical internship or residency, we offer deferment options.10
### Extended payment relief.
If you have gone through a reduced payment program and still need relief to get back on your feet, you may be eligible for a term extension of 60 months (5 years), which will lower your monthly payments.21
### A safety net just in case.
A lot can happen over the life of a loan. You may lose your job, or suffer from a financial hardship,11 or be impacted by a natural disaster.22 Abe is there for you with opportunities for payment relief.
### Past-due balances.
Falling behind and accumulating a past-due school balance can happen, particularly during financial emergencies or unexpected circumstances. If this occurs, an Abe loan can be used to cover the outstanding balance within 18 months of the academic period end date.17
## Enter for a chance to win $1,500† for undergraduate college expenses!
### Every month through December 31, 2026, Abe is helping undergraduate students and their families cover college costs.
[Enter Now](https://www.abestudentloans.com/resources/scholarships/undergraduate-college-scholarship-sweepstakes/)
## A Plain, Honest Guide to Private Student Loans
Abe believes that if you give people the honest, straightforward information they need to make good decisions, they will. That’s why we created the Plain, Honest Guide to Private Student Loans and invite you to download it here.
[Download Our Guide](/resources/#student-loan-guide)

---
### [College Finance](https://www.abestudentloans.com/college-finance/)
**Published:** May 30, 2024
**Author:** abelending
**Content:**
**Enter for a chance to win $1,500† in Abe’s Undergraduate Scholarship Sweepstakes!**
# Plain, honest student loans.
- Available for Undergrad, Grad, and Grad Specialty programs
- Up to 100% of college expenses covered[1](#f1)
- No application fees, processing fees, or late fees
- Find your rate in minutes[2](#f2) with no impact on your credit score
- Four repayment options, five loan terms[3](#f3)
- [In-School Default Protection](#options-terms)[4 ](#f4)saves you from default if you fall short while making payments in-school
[Find My Rate](http://abe.psl.sparrowfi.com)
## Our rates are low.
But there’s more to it.
Opting for a fixed rate means the rate won’t change for the life of your loan.[5](#f5) Remember, your actual rate will depend on your, or your cosigner’s, if applicable, credit. Applying with a creditworthy cosigner may result in a lower interest rate.
Undergraduate Fixed Rates\*
Abe.
2.08% – 16.58% APR6,7
Earnest
2.19% – 16.49% APR
College Ave
2.19% – 17.99% APR
Sallie Mae
2.39% – 17.49% APR
SoFi
2.45% – 15.99% APR
*\*Comparisons based on competitors’ websites (as of 7/27/26).
Lowest Annual Percentage Rates include a 0.25% discount when auto pay is elected.18*










### No Fees
No application fees, origination fees, late payment fees, forbearance fees, or fees to pay by debit card.
### 2% Grad Reward[8](#f8)
Upon request after graduating, reduce your principal balance by 2% of your net disbursed loan amount.
### Fast-Track Your Rate Reduction
For every six months of on-time principal and interest payments, Abe® lowers your rate by 0.05% — for a total reduction of up to 0.25%.9 Unlike other providers that require you to make years of payments first,\* Abe lets you start to lower your rate (and build a good credit history) much sooner.
g
### 5, 7, 10, 15, or 20 Years[3](#f3)
The term, or duration, impacts both the cost of a loan and your monthly payment amount. The longer the loan, the more interest you’ll pay but the lower your monthly cost will be. Abe has five terms — giving you more options for weighing the length/cost of your loan against a monthly payment you’re comfortable making.
### 6 Payment Relief Options
Abe is there for you with six different payment relief options that let you defer payments according to your education goals and timeline. For example, you may enroll in a medical internship or residency[10](#f10) or it may take longer for you to get on your financial feet after you graduate. You can also defer payments if you lose your job[13](#f13) or suffer a serious illness.[14](#f14)
### Early Cosigner Release[15](#f15)
Abe recognizes the shared commitment you and your cosigner make when taking out your student loan. That’s why, after just 12 months of on-time principal and interest payments, you can apply to release your cosigner – allowing you to take sole responsibility for the loan moving forward.
### Stress Less, Save More Time With the Returning Borrower Advantage14
[Reapply Now](http://abe.psl.sparrowfi.com)
When you come back for another Abe student loan, you not only have a higher chance of approval — you likely won’t need to resubmit income documentation again. Less paperwork, less waiting. Just a straightforward path to the money you need.
\*Comparisons based on competitors’ websites as of 7/27/26.
## Find the loan that fits your goals.
No matter where you are headed on your education journey, Abe can help you get there.

### Undergraduate
For undergraduate students enrolled in a bachelor’s or associate’s degree program.
**Learn More**

### Graduate
For graduate students enrolled in a degree or certificate program.
**Learn More**

### Law
For graduate students enrolled in a law degree program.
**Learn More**

### MBA
For graduate students enrolled in an MBA degree program.
**Learn More**

### Medical
For graduate students enrolled in a doctoral degree program: Doctor of Medicine (MD), Osteopathic Medicine (DO), Veterinary Medicine (DVM, VMD), or Podiatric Medicine (PM).
**Learn More**

### Dental
For graduate students enrolled in a dentistry degree program (Pediatric Dentistry, Periodontics, Oral Surgeon etc.).
**Learn More**

### Healthcare Professionals
For graduate students enrolled in a nursing, pharmacy, or allied health professional degree program (e.g., Dietitians, OT, Speech Pathologist, Audiologist, Dental Hygienist etc.).
**Learn More**
## Why Borrowers Are Choosing Abe
The Abe student loan experience, told by the people who lived it.
### "Abe was able to get me a great rate on my loan.
The loan process was smooth and I am very happy I was able to work with them.”
Gavin, Verified Borrower

### "I've dealt with a few different loans, but Abe is on a different level.
The entire application process was incredibly smooth. I was able to see my rates with a soft credit pull, which gave me peace of mind right from the start. Customer service is amazing.”
Joe, Verified Borrower

### "Easy process,
fast disbursement.”
Paola, Verified Borrower

### "Abe really helped me when I needed it most.
I didn’t think I would be able to afford college, but I applied for a loan and the process was smooth and manageable.”
Anonymous, Verified Borrower

### "The loan experience was very easy.
I feel the rate was fair. It allowed Isabelle to attend the school of her choice.“
Sean, Verified Borrower

### "Very Helpful
First time navigating school loans for my daughter, and they were very helpful when it came to choosing the right loan for her.“
Jennette, Verified Borrower

## How Abe stacks up.\*
### Zero Fees
### Grace Period11,12
### Repayment Options3
### Repayment Terms3
### Past Due Balances16
### On-Time Discount9
### Graduate Loans
### Graduate Certificate Loans
### Grad Reward8
### In-School Default Protection4
### Abe.
####
Up to 12 Months^
4
5, 7, 10, 15, & 20 Years
18 Months
####
####
####
####
####
### Zero Fees
### Grace Period11,12
### Repayment Options3
### Repayment Terms3
### Past Due Balances16
### On-Time Discount9
### Graduate Loans
### Graduate Certificate Loans
### Grad Reward8
### In-School Default Protection4
#### Sallie Mae
####
6 Months
3
10 to 15 Years
12 Months
####
####
####
####
####
### Zero Fees
### Grace Period11,12
### Repayment Options3
### Repayment Terms3
### Past Due Balances16
### On-Time Discount9
### Graduate Loans
### Graduate Certificate Loans
### Grad Reward8
### In-School Default Protection4
#### SoFi
####
6 Months
4
5, 7, 10, 15 & 20 Years
12 Months
####
####
####
####
####
### Zero Fees
### Grace Period11,12
### Repayment Options3
### Repayment Terms3
### Past Due Balances16
### On-Time Discount9
### Graduate Loans
### Graduate Certificate Loans
### Grad Reward8
### In-School Default Protection4
#### CollegeAve
####
6 Months
4
5, 8, 10, & 15 Years
12 Months
####
####
####
####
####
### Zero Fees
### Grace Period11,12
### Repayment Options3
### Repayment Terms3
### Past Due Balances16
### On-Time Discount9
### Graduate Loans
### Graduate Certificate Loans
### Grad Reward8
### In-School Default Protection4
#### Earnest
####
9 Months
4
5, 7, 10, 12, & 15 Years
12 Months
####
####
####
####
####
\*Comparisons based on competitors’ websites (as of 7/27/26).
^6 months grace guaranteed + possible 6 months grace extension.
- [Rate Discounts](#rate-discounts)
- [Student Loans](#degree-programs)
- [International](#international)
- [Options & Terms](#options-terms)
- [Payment Relief](#payment-relief)
Rate Discounts
Rate Discounts
## Lowering your rate. &
### Reduce your rate by up to 0.50% by building a good payment history.
Abe allows you to reduce your rate by 0.25% by electing auto pay18, even while you are enrolled in school, and up to an additional 0.25% interest rate reduction for making on-time principal and interest payments9 during the repayment term.
[Find My Rate](http://abe.psl.sparrowfi.com)
Student Loans
Student Loans
## [Student loans custom-fit to your degree. &](/student-loans)
### [Undergraduate Student Loans $](https://www.abestudentloans.com/student-loans/undergraduate)
An Abe student loan can be used to earn an associate, B.A., or B.S. degree at approved private and public universities and colleges. The aggregate loan limit1 for undergraduate students is $300,000.
### Post-Bachelor Graduate Certificates
Post-bachelor Graduate Certificate students can use an Abe loan to cover the costs associated with specialized certificates in their field and start their careers at a higher level. The aggregate loan limit1 for Graduate Certificate students is $350,000.
### [Graduate Student Loans $]()
Whether you're earning a master's, doctoral, or professional degree, Abe's graduate student loans offer the same benefits as our undergraduate loans.
Advanced degrees often require more funding. Abe's aggregate loan limit1 is $350,000 for Graduate, Law, MBA, and Healthcare Professional programs, and $500,000 for Medical and Dental programs.
### Less Than Half-Time Students
An Abe student loan can help students who just need a few more credits to finish their degree, including summer and Jan Plan courses.
International
International
## We welcome the world.19
### U.S. Citizens
### Permanent Residents
### DACA Recipients with a U.S. Cosigner
### International Students with a U.S. Cosigner
Options & Terms
Options & Terms
## More repayment options, more power to the individual.
Determining the right Abe loan for you means figuring out your ideal total loan cost vs. monthly payment amount.
Whether you can start repaying while in school or if you need to defer until after graduation, the rule of thumb is the shorter the loan term, the less interest you’ll pay and the lower the total cost of your loan.
Abe has five different loan terms: 5, 7, 10, 15, or 20 years.[3](#f3) Use the configurator in our online application to see how adjusting the length of your loan changes the monthly payment, and then choose the shortest term with a payment amount you’re comfortable making.
[Find My Rate](http://abe.psl.sparrowfi.com)
### In-School Payments[3](#f3)
- Making principal and interest payments lowers the cost of the loan the most
- Interest only payments reduce the long-term cost
- Low, flat payments steadily chip away at your balance
### Deferred Payments
- Wait until you graduate to start repayment20
### Five Different Loan Terms:
- 5, 7, 10, 15, or 20 years[3](#f3)
### In-School Default Protection4 saves you from default.
If you elect to make interest only or flat payments while in-school but fall short, In-School Default Protection will save you from default by automatically switching you to a deferred payment program. Abe also features an extra year of in-school deferment20 – up to 60 months (5 years) in case it takes a little longer to get your degree.
Payment Relief
Payment Relief
## Life happens. That's okay.
### Most students don't worry about borrowing money. They worry about paying it back.
### What if you need more time before starting repayment? What if life throws you a curveball?
### 6 months of grace and then 6 more.
Once you graduate, you have to look for a job. You may have to move. Buy a car. If you need 6 months before starting repayment, you got it.15 Then if you need 6 more months, that’s fine, too.16
### Health and family first.
If you end up out of work due to illness or go on unpaid FMLA leave, Abe provides up to 12 months of medical forbearance.12
### Re-enrollment, medical internships, and residencies.
If you re-enroll in school, or enter a medical internship or residency, we offer deferment options.10
### Extended payment relief.
If you have gone through a reduced payment program and still need relief to get back on your feet, you may be eligible for a term extension of 60 months (5 years), which will lower your monthly payments.21
### A safety net just in case.
A lot can happen over the life of a loan. You may lose your job, or suffer from a financial hardship,11 or be impacted by a natural disaster.22 Abe is there for you with opportunities for payment relief.
### Past-due balances.
Falling behind and accumulating a past-due school balance can happen, particularly during financial emergencies or unexpected circumstances. If this occurs, an Abe loan can be used to cover the outstanding balance within 18 months of the academic period end date.17
## Enter for a chance to win $1,500† for undergraduate college expenses!
### Every month through December 31, 2026, Abe is helping undergraduate students and their families cover college costs.
[Enter Now](https://www.abestudentloans.com/resources/scholarships/undergraduate-college-scholarship-sweepstakes/)
---
### [Resources](https://www.abestudentloans.com/resources/)
**Published:** March 11, 2024
**Author:** abelending
**Content:**
**Enter for a chance to win $1,500† in Abe’s Undergraduate Scholarship Sweepstakes!**

# Resources

## Student Loan Insights
Plain, honest insights to help you make smarter choices about paying for college.
&
&

## Sweepstakes
View current scholarship and promotional opportunities and check to see who’s won past sweepstakes.

## Press Releases
Keep up with Abe’s latest products, updates, and announcements.
&
&

## News & Reviews
Get a clear view of Abe through news features and unbiased reviews.
## Student Loan Glossary
A plain, honest dictionary of college financing terminology.
&
&
## Student Loan Calculator
Estimate monthly payments and compare different options and terms before you commit.
## Student Guides & Worksheets
Free printable tools to help you plan, borrow, and manage the cost of college.
&
## Frequently Asked Questions
### Am I eligible for a private student loan?
You are eligible if you meet the following criteria:24
- Undergraduate or graduate student enrolled at an eligible, 4-year institution in a degree-granting or graduate certificate program
- You’re at the legal age of majority, or at least 17 years of age at the time of application if applying with a cosigner who meets age of majority requirements in the cosigner’s state of residence
- You’re a U.S. citizen, permanent resident alien or an Eligible Non-Citizen (DACA recipient) applying with an eligible cosigner who is a U.S. citizen or permanent resident alien, or an international student applying with an eligible cosigner who is a U.S. citizen or permanent resident alien
### Do I need a cosigner for a private student loan?
Having a cosigner increases your approval chances. Plus, a cosigner with good credit and employment histories will typically get a lower interest rate.
### Who can be a cosigner on a private student loan?
A cosigner can be a parent, grandparent, aunt or uncle, guardian, or mentor. Anyone with good credit who believes in your dream of going to college and wants to help you achieve it.24
### What's the difference between a federal student loan and a private student loan?
A federal student loan is made by the federal government and is based on need. A private student loan is made by a private entity that uses a borrower’s credit history to determine loan terms.
### How much can I borrow with a private student loan?
With Abe, you can borrow[1](#f1):
**$1,000** minimum loan amount
**$300,000** aggregate student loan debt (total amount of student debt allowable) for Undergraduate programs
**$350,000** aggregate student loan debt for Graduate, Graduate Certificate, Law, MBA and Healthcare Professional programs
**$500,000** aggregate student loan debt for Medical and Dental programs
### What can I use a private student loan to pay for?
You can use it to pay for school-certified expenses including tuition, books and supplies, room and board, transportation, and personal expenses while you’re in school.1
### Can international students get private student loans?
Yes, international students can apply for an Abe private student loan with a cosigner who is a U.S. citizen or permanent resident alien and has a good credit history.19
### Do I need a credit history to get a private student loan?
Most students don’t have the credit history needed for qualifying for a private student loan. That’s why we recommend a cosigner.
### Can I use a private student loan to cover past due balances?
Yes, Abe loan applications for past due balances are accepted for up to the earlier of eighteen calendar months following the academic period for which the student was enrolled or eighteen months after graduating.17
### When do you have to start repaying a private student loan?
It depends on what works best for you. Some students like to get a head start by beginning repayment while in school while others defer making payments until after graduation.20
### What is an Application and Solicitation Disclosure (ASD)?
During the application process, private student loan providers are required by law to prepare and deliver to borrowers three disclosure documents. 1. An Application and Solicitation Disclosure, 2. An Approval Disclosure, and 3. A Final Disclosure.
The ASD contains current interest rate ranges, loan cost examples, federal loan alternatives, and other general information. When an eligible student and cosigner apply online for the Abe student loan, the ASD will be delivered electronically. Completion of an application is not required to view an ASD with current interest rates; however, all applicants, including prospective cosigners, must acknowledge that they have reviewed this disclosure before continuing the application process.
## A Plain, Honest Guide to Private Student Loans
When people have the information they need to make a good decision, they do.
On the other hand, sometimes there is so much information, students end up being confused. (And let’s face it, getting a loan can seem like a complicated process.) We created *A Plain, Honest Guide to Private Student Loans* as a straightforward resource that uses plain, everyday language to explain how private student lending works.
Simply fill out the form and we will send the Guide directly to your email inbox.
---
### [Student Guides & Worksheets](https://www.abestudentloans.com/resources/student-guides-worksheets/)
**Published:** August 24, 2026
**Author:** abelending
**Content:**
[Resources](/resources) > Student Guides & Worksheets

# Student Guides & Worksheets
Paying for college gets a lot less stressful when you can see the numbers. These free, printable guides and worksheets from Abe® help students and families plan, borrow, and manage the cost of college.
## Student Budgeting Worksheet
Most students don’t overspend on purpose. They overspend because nobody ever showed them the full list. Tuition and rent are easy to remember. The quiet budget killers are the $250 textbook, the course fee nobody mentioned until it hit the bill, and the takeout that replaces every meal during finals week.
This worksheet lays out every category on a single page: school costs, fixed expenses, variable spending, subscriptions, and income. Fill it in once and you get a real number for what’s left at the end of the month. Page two adds six budgeting tactics that work for college students, including how to review subscriptions each semester and why budgeting for wants keeps you from quitting the budget entirely.
[Download the Free PDF](https://www.abestudentloans.com/abe_student_budget_flyer_ugradsweeps_080326/)


## Understanding Credit: A College Student’s Guide to Credit Scores
A credit score is a three-digit number, usually between 300 and 850, that lenders use to estimate how likely you are to repay what you borrow. Higher scores generally mean better approval odds and lower interest rates. Five things build that number: your payment history, how much you owe, how long you’ve had credit, new applications, and the mix of account types you have open. Payment history and debt owed account for nearly two thirds of the score, which is good news, because those are the two you control most directly.
Credit matters more for college families than it used to. Federal loans often don’t cover the full cost of attendance, and recent changes to federal borrowing limits mean more families are covering that gap on their own. Private student loans can help fill it, and private lenders look at credit to decide who qualifies and at what rate. That makes your score, or your cosigner’s, one of the few parts of paying for college you can actually improve before you apply.
This guide covers what goes into a score, how to build one from scratch with a student credit card, how to protect the one you have with auto pay and low utilization, and how to dispute errors.
[Download the Free PDF](https://www.abestudentloans.com/abe_understandingcredit_ugradsweeps_060526-2/)
## Understanding Cosigning: What a Cosigner Does and When You Need One
A cosigner is someone with established credit and steady income who agrees to share responsibility for a loan with the student. Most college students need one, because recent high school grads usually haven’t had time to build the credit history and income private lenders look for. You don’t need a cosigner to apply for an Abe loan, but having one can improve your chances of approval, and it can get you a better rate even if you’d qualify on your own.
The part that deserves a real conversation is what cosigning means for the other person. The loan shows up on both credit reports, and payment history moves both scores in the same direction, good or bad. This guide explains who can cosign, from parents and grandparents to an aunt, uncle, or mentor, what the risks look like on both sides, and how Early Cosigner Release works. It also covers the habits that protect everyone: pay on time every time, and tell your cosigner before you miss a payment, not after.
[Download the Free PDF](https://www.abestudentloans.com/abe_cosigningloans_flyer_ugradsweeps_082326-2/)

## Ready to take the next step?
Prequalify in minutes. No credit score impact.2 Zero fees. See your actual rate today.
Tip: applying with a creditworthy cosigner may improve your approval odds and lower your interest rate.
[Find My Rate](http://abe.psl.sparrowfi.com)
---
### [Scholarships & Sweepstakes](https://www.abestudentloans.com/resources/scholarships/)
**Published:** November 20, 2025
**Author:** abelending
**Content:**

# Scholarships & Sweepstakes
Abe® provides ongoing scholarship opportunities to help students and parents manage the real costs of college. Check back regularly to see what’s happening now and who’s won before.

## Enter for a chance to win $1,500† for undergraduate college expenses!
### Now through December 31, 2026, Abe is helping undergraduate students and their families cover college costs.
[Enter Now](https://www.abestudentloans.com/resources/scholarships/undergraduate-college-scholarship-sweepstakes/)

## The entry period for Abe’s Graduate Scholarship Sweepstakes is now closed.
### Check to see who won the $5,000 grand prize!
[See the Winner](https://www.abestudentloans.com/resources/scholarships/graduate-college-scholarship-sweepstakes/)

### **Meet the Home for the Holidays Scholarship Sweepstakes Winners**
#### 6 winners each took home a share of $9,000 in scholarships to bring a little more joy home for the holiday season.
The Home for the Holidays Scholarship Sweepstakes wrapped up with six winners each receiving a $1,500 scholarship, just in time to make the season a little brighter. Thanks to everyone who joined in and helped us share the holiday spirit!
[See the Winners](https://www.abestudentloans.com/resources/scholarships/scholarship-holiday2025/)

### **Celebrating the Abe Birthday Scholarship Sweepstakes Winners**
#### 16 Winners. $20,000 in Scholarships.
One Big Congratulations.
The Abe Birthday Scholarship Sweepstakes has come to a close after 15 weeks. 15 lucky students were awarded $1,000 each and one grand prize winner $5,000, for a total of $20,000 in scholarships. Thank you to everyone who entered and helped make this sweepstakes a success!
[See the Winners](https://www.abestudentloans.com/resources/scholarships/birthday-scholarship/)
---
### [Abe Graduate Scholarship Sweepstakes](https://www.abestudentloans.com/resources/scholarships/graduate-college-scholarship-sweepstakes/)
**Published:** April 15, 2026
**Author:** abelending
**Content:**
# The entry period for Abe’s Graduate Scholarship Sweepstakes is now closed.
Thank you to every graduate student who entered. Submissions closed at 11:59:59 PM ET on July 31, 2026.

## Abe’s Graduate Scholarship Sweepstakes
### $5,000 Grand Prize Winner

#### **Allison M.**
J.D. Candidate at Baylor University School of Law, Class of 2029
*“I am so incredibly grateful to have won Abe’s Graduate Student Scholarship Sweepstakes! I begin my first year of law school this fall, so this prize will help provide books, course materials, and other essential study resources needed for my legal education. Thank you to Abe and Monogram for their generosity and support of students pursuing higher education!”*
### **Find the loan that fits your goals.**
No matter where you are headed on your education journey, Abe can help you get there.

#### Undergraduate
For undergraduate students enrolled in a bachelor’s or associate’s degree program.
**Learn More**

#### Graduate
For graduate students enrolled in a degree or certificate program.
**Learn More**

#### Law
For graduate students enrolled in a Law degree program.
**Learn More**

#### MBA
For graduate students enrolled in an MBA degree program.
**Learn More**

#### Medical
For graduate student enrolled in a doctoral degree program: Doctor of Medicine (MD), Osteopathic Medicine (DO), Veterinary Medicine (DVM, VMD), or Podiatric Medicine (PM).
**Learn More**

#### Dental
For graduate students enrolled in a dentistry degree program (Pediatric Dentistry, Periodontics, Oral Surgeon etc.).
**Learn More**

#### Healthcare Professionals
For graduate students enrolled in a nursing, pharmacy, or allied health professional (e.g., Dietitians, OT, Speech Pathologist, Audiologist, Dental Hygienist etc.) degree program.
**Learn More**
---
### [Abe's Plain, Honest Scholarship Sweepstakes](https://www.abestudentloans.com/resources/scholarships/undergraduate-college-scholarship-sweepstakes/)
**Published:** March 15, 2026
**Author:** abelending
**Content:**

## Abe® is helping undergraduate students and their families cover college costs.
- Every month now through December 31, 2026, we’re giving away $1,500.†
- Winners will be selected on or around the 7th day of each month for the previous month’s entry period, and will be notified by email and/or by phone using the contact information provided through the entry form.
- An Abe student loan is not required to enter or win the sweepstakes.
Here’s what you can expect when you borrow with Abe:
Up to 100% college expenses covered1
No Fees… Ever
Low Rates
Flexible repayment options3 put you in control
Longer repayment grace period than other loans15,16
2% Grad Reward8
# **Abe’s Undergraduate Scholarship Sweepstakes**
# **Enter for a chance to win $1,500† for college expenses!**
\* Required field
### **Meet the Winners**
One winner. Every month. Now through December 31, 2026. Next month’s winner could be you!
**Deni M.**
Senior, Georgia Southern Univeristy
April 2026
**Gabrielle S.**
Sophomore, Western Michigan University
May 2026
**Alexis P.**
Sophomore, Abraham Baldwin Agricultural College
June 2026
**Kimberly M.**
Incoming Freshman, The University of Texas at Austin
July 2026
### **We asked. Thousands of students answered.**
Every entry answers one optional question: what’s one thing you wish someone had told you about paying for college? Your honest responses continue to help us shape a better student loan solution for our borrowers. Here are a few answers that stuck with us.
**“**I wish someone explained the ‘hidden costs’ beyond tuition. All the little things like gas, supplies, meals, and books add up fast.**“**
**“**The price a college shows is not always the price you actually pay. Some expensive schools give a lot of financial aid, while some cheaper schools may not. It’s important to compare the real cost after scholarships, grants, and loans, and to make sure you can afford all four years, not just the first year.**“**
**“**Apply for scholarships immediately. The faster you get scholarship money, the less stressed you’ll be about paying off tuition, housing, and other expenses.**“**
**“**Start putting money aside early. Anything helps when it comes to college, even just a couple hundred extra dollars.**“**
**“**You don’t have to accept the full loan amount offered in your financial aid package. Many students assume they’re supposed to borrow everything they’re offered, but borrowing only what you truly need can save you thousands of dollars in interest over time.**“**
**“**FAFSA isn’t a one-time thing. You have to redo it every year, and your aid can change. Subsidized loans don’t accrue interest while you’re still in school, but unsubsidized loans do.**“**
**“**I wish someone told me it’s okay to ask for help paying for college. A lot of us carry the stress quietly while still trying to chase our dreams.**“**
**“**I wish someone had told me how important budgeting would become. Being able to manage my money, plan for future expenses, and make financial decisions has been a key part of my entire college experience.**“**
**“**There are far more affordable ways to earn a degree than taking on student loan debt. As an adult learner, I’ve learned how important it is to research transfer credits, financial aid, scholarships, and alternative learning programs before committing to expensive courses.**“**
**“**Financial aid offers often bundle free grants with student loans. It’s easy to accept an offer because the total aid package looks massive, only to realize that most of it is debt you have to pay back.**“**
Student quotes are drawn from responses submitted through Abe’s Plain, Honest Scholarship Sweepstakes and may be lightly edited for spelling, length, or clarity.
### **Find the loan that fits your goals.**
No matter where you are headed on your education journey, Abe can help you get there.

#### Undergraduate
For undergraduate students enrolled in a bachelor’s or associate’s degree program.
**Learn More**

#### Graduate
For graduate students enrolled in a degree or certificate program.
**Learn More**

#### Law
For graduate students enrolled in a Law degree program.
**Learn More**

#### MBA
For graduate students enrolled in an MBA degree program.
**Learn More**

#### Medical
For graduate student enrolled in a doctoral degree program: Doctor of Medicine (MD), Osteopathic Medicine (DO), Veterinary Medicine (DVM, VMD), or Podiatric Medicine (PM).
**Learn More**

#### Dental
For graduate students enrolled in a dentistry degree program (Pediatric Dentistry, Periodontics, Oral Surgeon etc.).
**Learn More**

#### Healthcare Professionals
For graduate students enrolled in a nursing, pharmacy, or allied health professional (e.g., Dietitians, OT, Speech Pathologist, Audiologist, Dental Hygienist etc.) degree program.
**Learn More**
---
### [About Abe Student Loans](https://www.abestudentloans.com/about-abe-student-loans/)
**Published:** August 4, 2026
**Author:** abelending
**Content:**
# About Abe Student Loans
Abe® is a private student loan that helps close the gap left after federal options, scholarships, grants, and other aid alternatives are exhausted — with plain, honest terms designed to create a more supportive borrower experience that better meets the needs of today’s college students. Abe is originated by Monogram LLC and funded by DR Bank, Member FDIC.
## Abe’s Mission
Abe is built on a simple belief: when people get honest, straightforward information, they make good decisions. We’re here to make private student loans transparent and fair with plain terms, no surprise fees, and real support at every step. Abe helps students invest in their education with clarity and confidence.
## What Kinds of Loans Does Abe Offer?
Not every education journey looks the same. Abe loans are designed to meet borrowers where they are: undergraduate, graduate, and graduate specialty programs like Law, MBA, Medical, and Dental with fixed and variable rates for students enrolled full-time, part-time, or half-time. Wherever you are in your education journey, Abe meets you there.
### Undergrad Loans
For students earning a bachelor’s or associate’s degree at an eligible school. An Abe undergraduate student loan can start as low as $1,000 and cover up to 100% of your school-certified college costs,1 with no fees, flexible repayment options,3 and rate discounts that reward good habits like auto pay18 and on-time payments.9
[Learn More About Abe Undergraduate Student Loans](https://www.abestudentloans.com/student-loans/undergraduate/)
### Grad Loans
For students pursuing a master’s, doctorate, or professional degree at an eligible school. An Abe graduate loan can cover up to 100% of graduate school costs,1 with higher loan limits for advanced degrees1 and specialized options for Law, MBA, Medical, Dental, and Healthcare Professionals.
[Learn More About Abe Graduate Student Loans](https://www.abestudentloans.com/student-loans/graduate/)
### Loans for Certificate Programs
For students enrolled in a qualified graduate certificate program at an eligible school. An Abe student loan can be used to pay for up to the full cost of certificate coursework,1 so you can focus on building specialized skills and a competitive edge for your career path.
### International Student Loans
For international students attending an eligible school. International students can apply for an Abe student loan with a cosigner who is a U.S. citizen or permanent resident,19 and get the same rates, no fees, and flexible repayment options3 offered to U.S. applicants.
### Half or Less Than Half-Time Students
For students enrolled half-time or less at an eligible school. Federal student loans typically require at least half-time enrollment, but an Abe student loan can help cover up to 100% of your college costs1 even if you are only taking a class or two, whether you are finishing your degree, returning to school, or studying at your own pace.
## What Makes Abe Different?
### No Fees
- No late fees
- No application fees
- No processing fees
### Rate Discounts
- Auto pay discount18
- Rate reductions for on-time payments9
### Flexible Repayment Options3
- 5 loan terms
- Deferred payments20
- In-school payments20
- In-School Default Protection4
### Payment Relief
- Up to 12-month grace period15,16
- Re-enrollment deferment10
- Medical forbearance12
- Payment relief for financial hardship11 and in case of natural disaster22
- Extended payment relief21
### Other Loan Features
- 2% Grad reward8
- Cosigner release13
- 18-month past-due balance coverage17
- Returning Borrower Advantage14
[Learn More About Our Loans](https://www.abestudentloans.com/loan-details/)
## Why Choose Abe?
### Backed by proven expertise
Abe was created by Monogram, the leader in data-driven private student lending, in partnership with DR Bank, Member FDIC. The Monogram team has managed more than $30 billion in private student loan assets over 30+ years.
### Rates among the lowest in the market
Abe offers student loan rates that rank among the most competitive you’ll find.
### Terms and benefits built for real life
From rate discounts9,18 and a 2% Grad Reward13 to six payment relief options and In-School Default Protection.4 Abe is designed for the way life actually happens.
### Nationally Recognized
Abe has been recognized and reviewed by leading personal finance and news outlets, including:
- CollegeFinance
- Buy Side from Wall Street Journal
- Fox Money
- CNN Underscored
- The College Investor
- Credible
- Money
- Forbes
- Fortune
- NerdWallet
- Bankrate
### Trusted by Students
### "Abe was able to get me a great rate on my loan.
The loan process was smooth and I am very happy I was able to work with them.”
Gavin, Verified Borrower
### "I've dealt with a few different loans, but Abe is on a different level.
The entire application process was incredibly smooth. I was able to see my rates with a soft credit pull, which gave me peace of mind right from the start. Customer service is amazing.”
Joe, Verified Borrower

### "Easy process,
fast disbursement.”
Paola, Verified Borrower

### "Abe really helped me when I needed it most.
I didn’t think I would be able to afford college, but I applied for a loan and the process was smooth and manageable.”
Anonymous, Verified Borrower

### "The loan experience was very easy.
I feel the rate was fair. It allowed Isabelle to attend the school of her choice.“
Sean, Verified Borrower

### "Very Helpful
First time navigating school loans for my daughter, and they were very helpful when it came to choosing the right loan for her.“
Jennette, Verified Borrower

## FAQs
### What is Abe?
Abe is a private student loan built to help students and families cover the cost of college after federal loans, scholarships, grants, and savings fall short. Abe keeps things plain and honest with clear terms, no fees, and a borrowing experience built around what today’s students actually need. Abe is a product of Monogram LLC and is funded by DR Bank, Member FDIC.
### Who can take out an Abe student loan?
Abe student loans are available to students enrolled, or about to enroll, in a degree-granting program at an eligible school. To apply, you’ll need to be at least the legal age of majority in your state, or at least 17 if you’re applying with a cosigner who meets the age requirement. You can be a U.S. citizen, permanent resident, or Eligible Non-Citizen (DACA recipient) – and if you are a DACA recipient or international student, you’ll need to apply with a cosigner who is a U.S. citizen or permanent resident. A dollar or more of annual income is required from the student on a solo application, or from the cosigner on a cosigned one. Though not required to apply, adding a creditworthy cosigner can increase your chance of approval and help you qualify for a lower rate. View the full eligibility requirements on our [Loan Details](https://www.abestudentloans.com/loan-details/) page.
### Who is Monogram?
Monogram is the company behind Abe. For more than 30 years, the Monogram team has been a leader in data-driven private student lending, managing over $30 billion in private student loan assets. That track record is what makes Abe possible. Decades of knowing how student loans work, put toward building a better, more supportive way to borrow.
### What is DR Bank’s role in the process?
DR Bank is the lender behind Abe student loans. As a Member FDIC bank, DR Bank funds every Abe loan, and all applications are approved based on the bank’s underwriting guidelines. Monogram creates and manages the Abe product experience, but the funds themselves come from DR Bank. They work together to bring you Abe, though Monogram is not an affiliate of DR Bank.
### Is Abe a legitimate student loan?
Yes, Abe is a legitimate private student loan. Abe loans are made by DR Bank, a Member FDIC lender, and are originated by Monogram LLC (NMLS #2542102), a company whose team has more than 30 years of experience and over $30 billion in private student loan assets under management. Abe has also been reviewed and recognized by trusted names in personal finance, including Buy Side from The Wall Street Journal, Forbes, NerdWallet, Bankrate, and CNN Underscored. Every loan is subject to approval under the lender’s underwriting guidelines, with clear terms and no hidden fees.
---
### [Cosigners](https://www.abestudentloans.com/cosigners/)
**Published:** March 19, 2024
**Author:** abelending
**Content:**
**Enter for a chance to win $1,500† in Abe’s Undergraduate Scholarship Sweepstakes!**

# Cosigner Information
## You don’t have to have a cosigner to apply for an Abe® loan.
That said, there are several reasons why it’s a really good idea to have one.
[Find My Rate](http://abe.psl.sparrowfi.com)
## A cosigner significantly increases your approval chances.
Abe loans are made based on credit. Yet very few students have used credit enough to have a credit history and a good credit score, which can make it difficult to get approved. Having a cosigner with healthy credit on your loan will make approval much more likely. A cosigner can be a parent, grandparent, aunt or uncle, guardian, or any responsible adult who believes in your dream of going to college.
## A cosigner with a good credit history may get a better rate.
Lenders use credit history, represented by what’s called a FICO score, as one factor for calculating the rate on the loan. A cosigner with a good FICO score may help you get a lower rate.
## Cosigner income is also a factor.
Responsible lenders do everything possible to make sure borrowers can afford to repay a loan. Since a cosigner is also responsible for the loan, his or her income improves your chances of approval.
## Who can be my cosigner?
While most cosigners are typically the student’s parents or grandparents, just about any guardian, mentor, or extended family member (think aunt or uncle) can be a cosigner on an Abe loan.24
## Early Cosigner Release13
Most students have little or no credit history and therefore apply with a cosigner. Once you’re financially able to handle your loan on your own, the cosigner can be released upon request. With Abe, this can happen after making only 12 months of principal and interest payments.
Some private student loan providers make you wait until you’re halfway through repayment (i.e., on a 10-year loan, the cosigner can’t be released for five years) while others make you wait at least two years.
---
### [Home 2026 | Rate Treatement A/B Test](https://www.abestudentloans.com/2026-rates/)
**Published:** July 27, 2026
**Author:** abelending
**Content:**
**Enter for a chance to win $1,500† in Abe’s Undergraduate Scholarship Sweepstakes!**
# Plain, honest student loans.
- Available for Undergrad, Grad, and Grad Specialty programs
- Up to 100% of college expenses covered[1](#f1)
- No application fees, processing fees, or late fees
- Find your rate in minutes[2](#f2) with no impact on your credit score
- Four repayment options, five loan terms[3](#f3)
- [In-School Default Protection](#options-terms)[4 ](#f4)saves you from default if you fall short while making payments in-school
[Find My Rate](http://abe.psl.sparrowfi.com)
## Our rates are low.
But there’s more to it.
Opting for a fixed rate means the rate won’t change for the life of your loan.[5](#f5) Remember, your actual rate will depend on your, or your cosigner’s, if applicable, credit. Applying with a creditworthy cosigner may result in a lower interest rate.
Undergraduate Fixed Rates\*
Abe.
2.08% – 16.58% APR6,7
Earnest
2.19% – 16.49% APR
College Ave
2.19% – 17.99% APR
Sallie Mae
2.39% – 17.49% APR
SoFi
2.45% – 15.99% APR
*\*Comparisons based on competitors’ websites (as of 7/27/26).
Lowest Annual Percentage Rates include a 0.25% discount when auto pay is elected.18*


### No Fees
No application fees, origination fees, late payment fees, forbearance fees, or fees to pay by debit card.
### 2% Grad Reward8
Upon request after graduating, reduce your principal balance by 2% of your net disbursed loan amount.
### Fast-Track Your Rate Reduction
For every six months of on-time principal and interest payments, Abe® lowers your rate by 0.05% — for a total reduction of up to 0.25%.[9](#f9) Unlike other providers that require you to make years of payments first,\* Abe lets you start to lower your rate (and build a good credit history) much sooner.
g
### 5, 7, 10, 15, or 20 Years3
The term, or duration, impacts both the cost of a loan and your monthly payment amount. The longer the loan, the more interest you’ll pay but the lower your monthly cost will be. Abe has five terms — giving you more options for weighing the length/cost of your loan against a monthly payment you’re comfortable making.
### 6 Payment Relief Options
Abe is there for you with six different payment relief options that let you defer payments according to your education goals and timeline. For example, you may enroll in a medical internship or residency10 or it may take longer for you to get on your financial feet after you graduate. You can also defer payments if you lose your job11 or suffer a serious illness.12
### Early Cosigner Release13
Abe recognizes the shared commitment you and your cosigner make when taking out your student loan. That’s why, after just 12 months of on-time principal and interest payments, you can apply to release your cosigner – allowing you to take sole responsibility for the loan moving forward.
### Stress Less, Save More Time With the Returning Borrower Advantage14
[Reapply Now](http://abe.psl.sparrowfi.com)
When you come back for another Abe student loan, you not only have a higher chance of approval — you likely won’t need to resubmit income documentation again. Less paperwork, less waiting. Just a straightforward path to the money you need.
\*Comparisons based on competitors’ websites as of 7/27/26.
## Find the loan that fits your goals.
No matter where you are headed on your education journey, Abe can help you get there.

### Undergraduate
For undergraduate students enrolled in a bachelor’s or associate’s degree program.
**Learn More**

### Graduate
For graduate students enrolled in a degree or certificate program.
**Learn More**

### Law
For graduate students enrolled in a law degree program.
**Learn More**

### MBA
For graduate students enrolled in an MBA degree program.
**Learn More**

### Medical
For graduate students enrolled in a doctoral degree program: Doctor of Medicine (MD), Osteopathic Medicine (DO), Veterinary Medicine (DVM, VMD), or Podiatric Medicine (PM).
**Learn More**

### Dental
For graduate students enrolled in a dentistry degree program (Pediatric Dentistry, Periodontics, Oral Surgeon etc.).
**Learn More**

### Healthcare Professionals
For graduate students enrolled in a nursing, pharmacy, or allied health professional degree program (e.g., Dietitians, OT, Speech Pathologist, Audiologist, Dental Hygienist etc.).
**Learn More**
## Why Borrowers Are Choosing Abe
The Abe student loan experience, told by the people who lived it.
### "Abe was able to get me a great rate on my loan.
The loan process was smooth and I am very happy I was able to work with them.”
Gavin, Verified Borrower

### "I've dealt with a few different loans, but Abe is on a different level.
The entire application process was incredibly smooth. I was able to see my rates with a soft credit pull, which gave me peace of mind right from the start. Customer service is amazing.”
Joe, Verified Borrower

### "Easy process,
fast disbursement.”
Paola, Verified Borrower

### "Abe really helped me when I needed it most.
I didn’t think I would be able to afford college, but I applied for a loan and the process was smooth and manageable.”
Anonymous, Verified Borrower

### "The loan experience was very easy.
I feel the rate was fair. It allowed Isabelle to attend the school of her choice.“
Sean, Verified Borrower

### "Very Helpful
First time navigating school loans for my daughter, and they were very helpful when it came to choosing the right loan for her.“
Jennette, Verified Borrower

## How Abe stacks up.\*
### Zero Fees
### Grace Period15,16
### Repayment Options3
### Repayment Terms3
### Past Due Balances17
### On-Time Discount9
### Graduate Loans
### Graduate Certificate Loans
### Grad Reward8
### In-School Default Protection4
### Abe.
####
Up to 12 Months^
4
5, 7, 10, 15, & 20 Years
18 Months
####
####
####
####
####
### Zero Fees
### Grace Period15,16
### Repayment Options3
### Repayment Terms3
### Past Due Balances17
### On-Time Discount9
### Graduate Loans
### Graduate Certificate Loans
### Grad Reward8
### In-School Default Protection4
#### Sallie Mae
####
6 Months
3
10 to 15 Years
12 Months
####
####
####
####
####
### Zero Fees
### Grace Period15,16
### Repayment Options3
### Repayment Terms3
### Past Due Balances17
### On-Time Discount9
### Graduate Loans
### Graduate Certificate Loans
### Grad Reward8
### In-School Default Protection4
#### SoFi
####
6 Months
4
5, 7, 10, 15 & 20 Years
12 Months
####
####
####
####
####
### Zero Fees
### Grace Period15,16
### Repayment Options3
### Repayment Terms3
### Past Due Balances17
### On-Time Discount9
### Graduate Loans
### Graduate Certificate Loans
### Grad Reward8
### In-School Default Protection4
#### CollegeAve
####
6 Months
4
5, 8, 10, & 15 Years
12 Months
####
####
####
####
####
### Zero Fees
### Grace Period15,16
### Repayment Options3
### Repayment Terms3
### Past Due Balances17
### On-Time Discount9
### Graduate Loans
### Graduate Certificate Loans
### Grad Reward8
### In-School Default Protection4
#### Earnest
####
9 Months
4
5, 7, 10, 12, & 15 Years
12 Months
####
####
####
####
####
\*Comparisons based on competitors’ websites (as of 7/27/26).
^6 months grace guaranteed + possible 6 months grace extension.
- [Rate Discounts](#rate-discounts)
- [Student Loans](#degree-programs)
- [International](#international)
- [Options & Terms](#options-terms)
- [Payment Relief](#payment-relief)
Rate Discounts
Rate Discounts
## Lowering your rate. &
### Reduce your rate by up to 0.50% by building a good payment history.
Abe allows you to reduce your rate by 0.25% by electing auto pay18, even while you are enrolled in school, and up to an additional 0.25% interest rate reduction for making on-time principal and interest payments9 during the repayment term.
[Find My Rate](http://abe.psl.sparrowfi.com)
Student Loans
Student Loans
## [Student loans custom-fit to your degree. &](/student-loans)
### [Undergraduate Student Loans $](https://www.abestudentloans.com/student-loans/undergraduate)
An Abe student loan can be used to earn an associate, B.A., or B.S. degree at approved private and public universities and colleges. The aggregate loan limit1 for undergraduate students is $300,000.
### Post-Bachelor Graduate Certificates
Post-bachelor Graduate Certificate students can use an Abe loan to cover the costs associated with specialized certificates in their field and start their careers at a higher level. The aggregate loan limit1 for Graduate Certificate students is $350,000.
### [Graduate Student Loans $]()
Whether you're earning a master's, doctoral, or professional degree, Abe's graduate student loans offer the same benefits as our undergraduate loans.
Advanced degrees often require more funding. Abe's aggregate loan limit1 is $350,000 for Graduate, Law, MBA, and Healthcare Professional programs, and $500,000 for Medical and Dental programs.
### Less Than Half-Time Students
An Abe student loan can help students who just need a few more credits to finish their degree, including summer and Jan Plan courses.
International
International
## We welcome the world.19
### U.S. Citizens
### Permanent Residents
### DACA Recipients with a U.S. Cosigner
### International Students with a U.S. Cosigner
Options & Terms
Options & Terms
## More repayment options, more power to the individual.
Determining the right Abe loan for you means figuring out your ideal total loan cost vs. monthly payment amount.
Whether you can start repaying while in school or if you need to defer until after graduation, the rule of thumb is the shorter the loan term, the less interest you’ll pay and the lower the total cost of your loan.
Abe has five different loan terms: 5, 7, 10, 15, or 20 years.[3](#f3) Use the configurator in our online application to see how adjusting the length of your loan changes the monthly payment, and then choose the shortest term with a payment amount you’re comfortable making.
[Find My Rate](http://abe.psl.sparrowfi.com)
### In-School Payments[3](#f3)
- Making principal and interest payments lowers the cost of the loan the most
- Interest only payments reduce the long-term cost
- Low, flat payments steadily chip away at your balance
### Deferred Payments
- Wait until you graduate to start repayment20
### Five Different Loan Terms:
- 5, 7, 10, 15, or 20 years[3](#f3)
### In-School Default Protection4 saves you from default.
If you elect to make interest only or flat payments while in-school but fall short, In-School Default Protection will save you from default by automatically switching you to a deferred payment program. Abe also features an extra year of in-school deferment20 – up to 60 months (5 years) in case it takes a little longer to get your degree.
Payment Relief
Payment Relief
## Life happens. That's okay.
### Most students don't worry about borrowing money. They worry about paying it back.
### What if you need more time before starting repayment? What if life throws you a curveball?
### 6 months of grace and then 6 more.
Once you graduate, you have to look for a job. You may have to move. Buy a car. If you need 6 months before starting repayment, you got it.15 Then if you need 6 more months, that’s fine, too.16
### Health and family first.
If you end up out of work due to illness or go on unpaid FMLA leave, Abe provides up to 12 months of medical forbearance.12
### Re-enrollment, medical internships, and residencies.
If you re-enroll in school, or enter a medical internship or residency, we offer deferment options.10
### Extended payment relief.
If you have gone through a reduced payment program and still need relief to get back on your feet, you may be eligible for a term extension of 60 months (5 years), which will lower your monthly payments.21
### A safety net just in case.
A lot can happen over the life of a loan. You may lose your job, or suffer from a financial hardship,11 or be impacted by a natural disaster.22 Abe is there for you with opportunities for payment relief.
### Past-due balances.
Falling behind and accumulating a past-due school balance can happen, particularly during financial emergencies or unexpected circumstances. If this occurs, an Abe loan can be used to cover the outstanding balance within 18 months of the academic period end date.17
## Enter for a chance to win $1,500† for undergraduate college expenses!
### Every month through December 31, 2026, Abe is helping undergraduate students and their families cover college costs.
[Enter Now](https://www.abestudentloans.com/resources/scholarships/undergraduate-college-scholarship-sweepstakes/)
## A Plain, Honest Guide to Private Student Loans
Abe believes that if you give people the honest, straightforward information they need to make good decisions, they will. That’s why we created the Plain, Honest Guide to Private Student Loans and invite you to download it here.
[Download Our Guide](/resources/#student-loan-guide)

---
### [Cookie Policy](https://www.abestudentloans.com/cookie-policy/)
**Published:** June 23, 2026
**Author:** abelending
**Content:**
This page provides comprehensive information about how we use cookies on our website to enhance your browsing experience, improve website performance, and deliver personalized content. Cookies are small text files that are stored on your device when you visit our site. They help us understand how visitors interact with our website, allowing us to offer a smoother and more efficient user experience. In the table below, you will find detailed information about each type of cookie we use, their purpose, and how long they remain on your device. We are committed to respecting your privacy and providing transparency about the data we collect through cookies. For more information on how we handle your personal data, please see our Privacy Policy.
## Essential
Essential cookies enable basic functions and are necessary for the proper function of the website.
NameDescriptionDurationwpconsent\_preferencesThis cookie is used to store the user's cookie consent preferences.30 days### Google Tag Manager
Google Tag Manager simplifies the management of marketing tags on your website without code changes.
NameDescriptionDurationcookiePreferencesRegisters cookie preferences of a user2 yearstdRegisters statistical data on users' behaviour on the website. Used for internal analytics by the website operator.session### Login
These cookies are used for managing login functionality on this website.
NameDescriptionDurationwordpress\_test\_cookieUsed to determine if cookies are enabled.Sessionwordpress\_logged\_inUsed to store logged-in users.Persistentwordpress\_secUsed to track the user across multiple sessions.15 days## Statistics
Statistics cookies collect information anonymously. This information helps us understand how visitors use our website.
### Google Analytics
Google Analytics is a powerful tool that tracks and analyzes website traffic for informed marketing decisions.
[Learn more](https://policies.google.com/privacy)
NameDescriptionDuration\_gatUsed to monitor number of Google Analytics server requests when using Google Tag Manager1 minute\_\_utmxUsed to determine whether a user is included in an A / B or Multivariate test.18 months\_gaID used to identify users2 years\_galiUsed by Google Analytics to determine which links on a page are being clicked30 seconds\_ga\_ID used to identify users2 years\_gidID used to identify users for 24 hours after last activity24 hours\_\_utmaID used to identify users and sessions2 years after last activity\_\_utmtUsed to monitor number of Google Analytics server requests10 minutes\_\_utmbUsed to distinguish new sessions and visits. This cookie is set when the GA.js javascript library is loaded and there is no existing \_\_utmb cookie. The cookie is updated every time data is sent to the Google Analytics server.30 minutes after last activity\_\_utmcUsed only with old Urchin versions of Google Analytics and not with GA.js. Was used to distinguish between new sessions and visits at the end of a session.End of session (browser)\_\_utmzContains information about the traffic source or campaign that directed user to the website. The cookie is set when the GA.js javascript is loaded and updated when data is sent to the Google Anaytics server6 months after last activity\_\_utmvContains custom information set by the web developer via the \_setCustomVar method in Google Analytics. This cookie is updated every time new data is sent to the Google Analytics server.2 years after last activity\_gac\_Contains information related to marketing campaigns of the user. These are shared with Google AdWords / Google Ads when the Google Ads and Google Analytics accounts are linked together.90 days### Microsoft Clarity
Clarity is a web analytics service that tracks and reports website traffic.
[Learn more](https://clarity.microsoft.com/privacy)
NameDescriptionDuration\_clskConnects multiple page views by a user into a single Clarity session recording.12 months\_clckPersists the Clarity User ID and preferences, unique to that site is attributed to the same user ID.12 monthsANONCHKIndicates whether MUID is transferred to ANID, a cookie used for advertising. Clarity doesn't use ANID and so this is always set to 0.SessionCLIDIdentifies the first-time Clarity saw this user on any site using Clarity.12 months
---
### [Student Loan & College Financing Glossary](https://www.abestudentloans.com/resources/student-loan-college-financing-glossary/)
**Published:** May 26, 2026
**Author:** abelending
**Content:**
[Resources](/resources) > Student Loan & College Financing Glossary
# Student Loan & College Financing Glossary

Tip: Use the section headings below to jump to the topics you’re interested in: applying for aid, federal loans, private loans, how interest works, repayment, or refinancing.
## A plain, honest dictionary of college financing terminology.
Borrowing for college comes with its own vocabulary, and the wrong assumption about a single term can cost real money. This glossary covers the terms students and families encounter most often when navigating financial aid, federal loans, and private student loans, defined simply, with the practical implications you actually need to know.
Tip: Use the section headings below to jump to the topics you’re interested in: applying for aid, federal loans, private loans, how interest works, repayment, or refinancing.
- [Applying For Financial Aid](#applying-for-financial-aid)
- [Federal Student Loans](#federal-student-loans)
- [Private Student Loans](#private-student-loans)
- [How Interest Works](#how-interest-works)
- [Repayment Options & Terms](#repayment-options-and-terms)
- [Refinancing & Consolidation](#refinancing-and-consolidation)
- [Other Helpful Terms](#other-helpful-terms)
## Applying for Financial Aid
### FAFSA (Free Application for Federal Student Aid)
The free online form students must complete every year to apply for federal financial aid, including grants, work-study, and federal student loans. Most colleges and many states also use FAFSA data to award their own aid. Available at [studentaid.gov](https://studentaid.gov/) starting October 1 each year for the following academic year.
### FSA ID
The username and password used to sign the FAFSA electronically and access federal student aid systems at studentaid.gov. Each student and each parent contributor needs their own FSA ID. Create it at least a few days before starting the FAFSA, as it can take time to verify.
### SAI (Student Aid Index)
A number, calculated from the FAFSA, that schools use to determine how much financial aid you’re eligible for. The SAI replaced the older Expected Family Contribution (EFC) starting with the 2024–25 award year. While it can be confusing, the SAI is not a bill. It’s a number your school subtracts from the total Cost of Attendance to build your aid package.
### Expected Family Contribution (EFC)
The pre-2024–25 award year measure that estimated how much a family would be expected to contribute toward college costs. It has now been replaced by the Student Aid Index (SAI), but you’ll still see EFC referenced in older articles, scholarship applications, and some school worksheets. It is the same general concept as the SAI, just calculated differently.
### FAFSA Submission Summary
The summary document students receive after submitting the FAFSA, showing the information reported and the calculated Student Aid Index. This replaced the older Student Aid Report (SAR) starting with the 2024–25 award year. Make sure to review it for errors before your school finalizes your aid offer.
### CSS Profile
A separate, more detailed financial aid application used by roughly 200+ private colleges to award their institutional (school-funded) aid. Administered by the College Board and, unlike the FAFSA, it usually has a fee.
### Cost of Attendance (COA)
The school’s total estimated annual cost of attending — This includes tuition and fees, room and board, books, supplies, transportation, and personal expenses. COA is the ceiling on how much financial aid (including loans) you can receive in a year.
### Tuition
What a school charges for instruction itself, separate from room, board, books, fees, and other costs. Tuition is often the single largest line item in Cost of Attendance.
### Financial Need
The difference between a school’s Cost of Attendance and your Student Aid Index (COA – SAI = Financial Need). It determines eligibility for need-based aid such as Pell Grants and Direct Subsidized Loans.
### Unmet Need (Or, “The Gap”)
The portion of Cost of Attendance that remains after subtracting all grants, scholarships, work-study, and federal student loans you’ve received. Unmet need is typically the gap that families end up covering through savings, current income, or private student loans.
### Financial Aid
The catch-all term for any funding that helps cover college costs, including grants, scholarships, work-study, and student loans. Sources include federal, state, school (institutional), and private loans.
### Financial Aid Package
The total combination of grants, scholarships, work-study, and school loans a school offers you for a given academic year, detailed in your award letter. Different schools can package the same student very differently, which is why side-by side comparison matters, as they vary by school.
### Award Letter (Financial Aid Offer)
The document a school sends after you’re admitted that lists grants, scholarships, work-study, and loans being offered. Make sure to do a side-by-side comparison, as they vary by school.
### Academic Year
One complete school year at the same institution, generally August through May. If a student transfers mid-year, the two halves are usually treated as two separate academic years for aid purposes.
### Award Year
The academic year a particular financial aid package applies to. For example, the 2026–27 award year covers aid disbursed for fall 2026 through summer 2027.
### Need-Based Aid
Financial aid awarded based on demonstrated financial need (calculated from the FAFSA and, for some schools, the CSS Profile). Includes Pell Grants, Direct Subsidized Loans, and most institutional need-based grants.
### Merit-Based Aid
Financial aid awarded based on academic, athletic, artistic, or other achievements. This is not based on a student’s financial need. Most institutional scholarships and many private scholarships are merit-based.
### Title IV
The section of the Higher Education Act that authorizes federal student aid programs (Pell Grants, Direct Loans, work-study, etc.). A school must be Title IV–eligible (accredited and approved by the Department of Education) for its students to receive federal aid.
### Verification
A process where the school asks you to confirm information reported on your FAFSA. Roughly 1 in 4 FAFSAs are selected. You may need to provide tax transcripts, W-2s, or other documents.
## Federal Student Loans
### Direct Loan
The umbrella term for federal student loans made through the William D. Ford Federal Direct Loan Program, including Direct Subsidized, Direct Unsubsidized, Direct PLUS, and Direct Consolidation Loans. Most federal student loans today are Direct Loans.
### Direct Subsidized Loan
A need-based federal loan for undergraduate students. The U.S. Department of Education pays the interest while you’re enrolled at least half-time, during the 6-month grace period, and during deferment.
### Direct Unsubsidized Loan
A federal loan available to undergraduate, graduate, and professional students regardless of financial need. Interest accrues from the day the loan is disbursed — including while you’re in school.
### Direct PLUS Loan
A federal loan for graduate/professional students (Grad PLUS) or for parents of dependent undergraduates (Parent PLUS). Requires a credit check and typically carries a higher interest rate and origination fee than other Direct Loans.
### Grad PLUS Loan
The common name for a Direct PLUS Loan taken out by a graduate or professional student. **Important note:** under current federal law, no new Grad PLUS loans will be issued to new borrowers after July 1, 2026. Borrowers who took out a Grad PLUS loan before that date can generally continue borrowing under existing terms through the 2028–29 academic year.
### Parent PLUS Loan
A specific type of Direct PLUS Loan taken out by a parent (not the student) to help pay for an undergraduate child’s education. The parent is legally responsible for repayment, not the student.
### Subsidized vs. Unsubsidized
The key difference is who pays the interest while you’re in school. On subsidized loans, the government pays it; on unsubsidized loans, the borrower owes that interest, which can capitalize and grow the balance.
### Annual Loan Limit / Aggregate Loan Limit
The maximum amount you can borrow in federal Direct Loans each year (annual limit) and over your entire academic career (aggregate limit). Limits depend on your year in school, dependency status, and loan type.
### Undergraduate Student
A student enrolled in a course of study leading to an associate or bachelor’s degree, typically lasting two to four years. Federal loan limits, eligibility for subsidized loans, and PLUS borrowing rules all depend in part on undergraduate vs. graduate status.
### Graduate or Professional Student
A student pursuing education beyond a bachelor’s degree. This includes master’s, doctoral, law (JD), medical (MD/DO), dental, veterinary, and similar programs. Eligibility for Grad PLUS, higher annual unsubsidized loan limits, and certain repayment plans depend on this classification.
### Enrollment Status
How much coursework you are enrolled in. This can include full-time, three-quarter-time, half-time, less than half-time, withdrawn, or graduated. Your enrollment status determines eligibility for most federal aid and triggers the grace period when status drops below half-time. Definitions of “full-time” vary slightly by school.
### Origination Fee
A fee deducted from the loan amount before it’s disbursed to your school. Federal Direct Loans have a small origination fee; many private student loans do not, but make sure to read the fine print.
### Master Promissory Note (MPN)
The legal contract you sign promising to repay your federal student loans, plus any interest and fees. Usually signed once and used for multiple loans over several years.
### Entrance Counseling / Exit Counseling
Required online sessions for federal loan borrowers. Entrance counseling (before your first loan) explains your rights and obligations. Exit counseling (when you graduate, leave school, or drop below half-time) prepares you for repayment.
### Grace Period
The set period after you graduate, leave school, or drop below half-time enrollment before you must begin making payments. Federal Direct Loans typically have a 6-month grace period.
### Deferment
A temporary postponement of loan payments. On Direct Subsidized Loans (and some others), interest does not accrue during deferment. On unsubsidized and PLUS loans, it does.
### In-School Deferment
An automatic deferment for federal loans while you’re enrolled at least half-time. Interest still accrues on unsubsidized and PLUS loans during this period and will capitalize when the deferment ends, so paying the interest as it accrues can save real money.
### Forbearance
A temporary pause or reduction in payments, generally granted at the lender’s discretion. Interest accrues on all loan types during forbearance, which can significantly increase the balance.
### Income-Driven Repayment (IDR)
Federal repayment plans that set your monthly payment based on your income and family size rather than the loan balance. Common plans include SAVE, PAYE, IBR, and ICR (availability and rules can change — always check studentaid.gov).
### Standard Repayment Plan
The default federal repayment plan: fixed monthly payments over 10 years. Usually results in the lowest total interest paid.
### Graduated Repayment Plan
A federal repayment plan where payments start lower and increase every two years over a 10-year term. Designed for borrowers who expect their income to grow significantly over time.
### Public Service Loan Forgiveness (PSLF)
A federal program that forgives the remaining balance on Direct Loans after 120 qualifying monthly payments while working full-time for an eligible government or nonprofit employer.
### Loan Servicer
The company that handles billing, payments, and customer service for your federal loan. Your servicer is not the same as your lender; the U.S. Department of Education contracts with several servicers.
### Default
Failure to make payments according to the terms of your loan. For most federal loans, default occurs after about 270 days of nonpayment. Consequences include damaged credit, wage garnishment, tax refund offsets, and loss of eligibility for additional federal aid.
### Delinquency
The status of being late on a payment. Delinquency starts the day after you miss a payment and can be reported to credit bureaus after 90 days.
## Private Student Loans
### Private Student Loan
An education loan from a bank, credit union, online lender, or state agency — not the federal government. Terms, rates, and protections vary by lender and depend heavily on the borrower’s (or cosigner’s) credit.
### Borrower
The person who takes out the loan and is legally responsible for repaying it. On a cosigned loan, the student is the primary borrower and the cosigner is also legally liable.
### Lender
The financial institution that originates and funds the loan. Distinct from the loan servicer, which handles billing and customer service after the loan is disbursed.
### Cosigner
A creditworthy adult — often a parent or relative — who signs the loan with the student and is equally legally responsible for repayment. Most undergraduate students need a [cosigner](/cosigners) to qualify for a private loan or to get a competitive rate.
### Cosigner Release
A feature offered by some private lenders that lets the primary borrower remove the cosigner from the loan after meeting certain requirements (typically a number of consecutive on-time payments and a credit check).
### Creditworthiness
A lender’s assessment of how likely you are to repay debt, based on credit score, credit history, income, and debt-to-income ratio. The stronger your profile (or your cosigner’s), the better your interest rate.
### Underwriting
The process a lender uses to evaluate a loan application and decide whether to approve it, at what rate, and on what terms. Underwriting looks at credit, income, debt-to-income, school, and program of study.
### Credit Score
A three-digit number (commonly FICO, ranging 300–850) summarizing your credit risk. Most private student loan lenders look for scores in the high 600s or above for approval, with the best rates reserved for scores in the 700s and up.
### FICO Score
The most widely used credit scoring model, developed by the Fair Isaac Corporation. Scores range from 300 to 850. Most private student lenders rely on a FICO score (or the similar VantageScore) when underwriting your application.
### Credit Report
A detailed record of your credit history — payment history, current debts, credit utilization, length of credit history, and public records — compiled by the three major credit bureaus (Experian, Equifax, TransUnion). Lenders pull credit reports as part of underwriting.
### Debt-to-Income Ratio (DTI)
The percentage of your monthly gross income that goes toward debt payments. Lenders use DTI alongside credit score to assess whether you can take on a new loan and still cover existing obligations.
### Eligibility
The set of requirements a borrower must meet to qualify for a particular loan. This typically includes U.S. residency or citizenship, enrollment at an eligible school, minimum age, and credit or cosigner requirements. Eligibility rules vary by lender.
### Self-Certification Form
A form private student loan applicants must complete and return to the lender confirming the loan amount requested does not exceed Cost of Attendance minus other aid received. Required by federal regulation for every private student loan.
### School Certification
The process by which your school’s financial aid office verifies your enrollment, Cost of Attendance, and other aid received, and confirms the requested loan amount to the lender before funds can be disbursed.
### Prequalification (Soft Pull)
A check that shows estimated rates and terms of a loan without affecting your credit score. This check is useful for shopping multiple private lenders. A hard pull happens when you formally apply, and can lower your score by a few points.
### APR (Annual Percentage Rate)
The yearly cost of a loan expressed as a percentage, including interest and certain fees. APR is typically the most accurate way to compare loans because it captures more than just the interest rate.
### Interest Rate
The percentage of the loan balance charged as the cost of borrowing, not including fees. Compare interest rates and APRs side by side when shopping.
## How Interest Works
### Interest
The cost of borrowing money, calculated as a percentage of the unpaid loan principal and charged to the borrower over the life of the loan. Interest is what makes the total you pay back larger than the amount you originally borrowed.
### Principal
The original amount borrowed, plus any unpaid interest that has been added through capitalization. Most monthly payments cover both principal and interest. As the loan ages, more of each payment goes toward principal (see Amortization).
### Fixed Interest Rate
An interest rate that stays the same for the entire life of the loan. Your monthly payment of principal and interest won’t change due to market conditions. All federal student loans currently have fixed rates.
### Variable Interest Rate
An interest rate that can rise or fall over time, usually tied to a benchmark index like SOFR plus a fixed margin. Variable rates often start lower than fixed rates but can increase, raising your payment. Most lenders cap variable rates, but the cap is typically high.
### SOFR (Secured Overnight Financing Rate)
The benchmark index most private lenders now use for variable-rate student loans (replacing the LIBOR, or London Interbank Offered Rate). Your variable rate equals SOFR plus a margin set by the lender based on your credit profile.
### Margin
The fixed percentage a private lender adds to the index (like SOFR) to determine your variable rate. The margin is set when you take the loan and doesn’t change; the index does.
### Rate Cap
The highest the interest rate on a variable-rate loan can go. Federal Stafford-style loans have low caps; private variable rates often cap at 18–25%.
### Simple Interest
Interest calculated only on the outstanding principal. Federal student loans and most private student loans use simple daily interest — not compound interest.
### Daily Interest Accrual
Interest that adds to your balance every day, calculated as: (Principal × Interest Rate) ÷ 365. Making payments more often or earlier in the month can reduce total interest paid.
### Amortization
The process of paying off a loan through scheduled payments that cover both interest and principal. Early in the term, most of each payment covers interest; later, most of it covers principal. An amortization schedule shows this breakdown for every month of the loan.
### Capitalization
When unpaid interest is added to your principal balance — meaning you start paying interest on the interest. Capitalization commonly happens at the end of the grace period, after deferment or forbearance, or when you leave an income-driven plan. Avoiding capitalization (by paying interest as it accrues) is one of the biggest money-savers in student loans.
### Capitalized Interest
Accrued interest that has been moved into the principal balance. Once capitalized, that interest itself begins accruing interest, which permanently increases the cost of the loan — even if no new dollars are borrowed.
### Accrued Interest
Interest that has built up on your loan but hasn’t yet been paid or capitalized.
### Adjusted Gross Income (AGI)
Your gross income minus specific federal tax deductions, reported on your tax return. AGI matters for student loans because it’s used to determine eligibility for income-driven repayment plans and the student loan interest deduction.
### Discretionary Income
The income remaining after taxes and certain necessary expenses. Federal income-driven repayment plans use discretionary income to calculate your monthly payment — typically defined as AGI minus 150% to 225% of the federal poverty guideline, depending on the plan.
### Student Loan Interest Deduction
A federal tax deduction that lets eligible borrowers deduct up to $2,500 in student loan interest paid during the tax year (subject to income limits). Available for both federal and private student loans. You don’t have to itemize to claim it.
## Repayment Options & Terms
### In-School Payment / Immediate Repayment
A repayment option (mostly on private loans) where the borrower makes full principal-and-interest payments while still in school. Usually has the lowest total cost.
### Interest-Only Payment
A repayment option (mostly on private loans) where the borrower pays just the monthly interest while in school, keeping the principal from growing. This results in lower payments than full repayment, but lower total cost than fully deferring.
### Fixed (Flat) In-School Payment
A small fixed monthly payment (often around $25) made while in school. Common with private lenders. This payment reduces but doesn’t eliminate interest accumulation.
### Deferred Repayment
A repayment option where no payments are required while in school and during a grace period. Interest still accrues on most loans (and capitalizes later), so total cost is the highest of the four options.
### Loan Term
The length of time you have to repay a loan. Federal Direct Loans are typically 10 years on the standard plan; private loan terms commonly range from 5 to 20 years. Longer terms equal lower monthly payments but more total interest.
### Repayment Period
The total length of time over which you’ll make scheduled payments on a loan. Sometimes used interchangeably with Loan Term, though strictly speaking, the repayment period excludes any in-school or grace period that comes before it.
### Loan Period
The portion of the academic year a specific loan is intended to cover. This is often a single semester or a full academic year. Loan period determines when and how loan funds are disbursed.
### Auto Pay Discount
A small interest-rate reduction (commonly 0.25%) many lenders offer when you set up automatic monthly payments from a bank account.
### Auto Pay (ACH)
Automatic monthly loan payments pulled from your bank account via the Automated Clearing House (ACH) electronic transfer system. Most private lenders offer a small autopay discount (commonly 0.25%) for enrolling. Beyond the savings, it also reduces the risk of missing a payment.
### Prepayment Penalty
A fee for paying off a loan early. Federal student loans and reputable private student loans do not charge prepayment penalties — you can always pay extra without being penalized.
### Current Amount Due
The minimum payment that must be made by the next due date — not the total loan balance. Statements typically show both, and it’s worth knowing the difference.
### Disbursement
The actual delivery of loan funds, usually sent directly to your school in one or more installments per academic year.
## Refinancing & Consolidation
### Student Loan Refinancing
Taking out a new private loan to pay off one or more existing student loans, ideally at a lower interest rate or better terms. You can refinance private and federal student loans together. Just note that refinancing federal loans into a private loan permanently gives up federal benefits like income-driven repayment, PSLF, and federal forbearance options.
### Direct Consolidation Loan
A federal program that combines multiple federal loans into a single new federal loan with one monthly payment. The new rate is the weighted average of your existing rates (rounded up to the nearest one-eighth of a percent), so consolidation does not lower your rate, but it can simplify payments and unlock certain repayment plans or PSLF eligibility.
### Refinance vs. Consolidate
Consolidate (federal) keeps your loans federal and combines them at a weighted-average rate. Refinance (private) replaces your loans with a brand-new private loan at a market rate based on your credit. The two are not interchangeable.
## Other Helpful Terms
### Dependency Status
A FAFSA classification of whether you’re considered a dependent or independent student. Dependent students must report parent income on the FAFSA; independent students do not. Most undergraduates under 24 are considered dependent unless they meet specific criteria (married, veteran, have dependents, etc.).
### Pell Grant
A need-based federal grant for undergraduate students with exceptional financial need. Grants do not have to be repaid.
### Grant
Financial aid that doesn’t have to be repaid, usually awarded based on financial need. The Pell Grant is the largest federal grant program, but; states and schools also offer their own grants.
### Scholarship
Financial aid that doesn’t have to be repaid, generally awarded based on merit (academic, athletic, artistic) — though some [scholarships](/blog/scholarships/top-14-places-to-find-college-scholarships/) factor in need or other criteria. Available from schools, governments, nonprofits, employers, and private organizations.
### Work-Study
A federal program that provides part-time jobs to students with financial need to help pay education expenses. Earnings are paid like a regular paycheck.
### Stafford Loan
The older common name for federal Direct Subsidized and Unsubsidized Loans. Today’s program is officially the William D. Ford Federal Direct Loan Program, but you’ll still see the term Stafford in many places.
### NSLDS (National Student Loan Data System)
The U.S. Department of Education’s central database of federal student aid. Log in at studentaid.gov to see all your federal loans, balances, and servicers in one place.
### Truth in Lending Act (TILA) Disclosures
Required disclosures private lenders must give you at three points (application, approval, and just before disbursement) showing the loan’s APR, fees, total cost, and payment schedule. You have a 3-day right-to-cancel window after the final disclosure.
### Discharge
The cancellation of your obligation to repay a loan in specific situations, such as total and permanent disability, death of the borrower, or school closure. Different from forgiveness, which is typically tied to time-in-repayment programs.
### Forgiveness
Cancellation of a remaining loan balance, usually after meeting program requirements — for example, PSLF (10 years public service) or income-driven repayment forgiveness (after 20–25 years).
## About This Glossary
This glossary is provided by Abe® (abestudentloans.com) for educational purposes only and is not financial, legal, or tax advice. Federal loan rules and program details, including IDR plan availability, PSLF requirements, and loan limits, can change. For current information, visit studentaid.gov or speak with your school’s financial aid office.
---
### [Student Loan Calculator](https://www.abestudentloans.com/resources/student-loan-calculator/)
**Published:** February 16, 2026
**Author:** abelending
**Content:**
[Resources](/resources) > Student Loan Calculator

# Student Loan Calculator
Borrowing for college is one of the biggest financial decisions you’ll make, and the smartest borrowers are the ones who run the numbers before they sign, not after. The Student Loan Calculator lets you do exactly that.
See how loan amount, interest rate, repayment term, and in-school payment choices shape both your monthly payment and the total you’ll pay over the life of the loan. Test different scenarios, understand your options, and walk into the borrowing process knowing what to expect.
[How to Use This Calculator](/resources/student-loan-calculator/#how-to-use-calculator)
Abe Student Loan Calculator
Calculator results are estimates for educational purposes only. Actual loan terms, including interest rate, monthly payment, and repayment schedule, may vary based on credit evaluation and loan approval. This calculator assumes fixed interest rates and simple interest during in-school periods. Abe private student loans are subject to credit approval. Please review loan terms carefully before borrowing.
## Ready to take the next step?
Prequalify in minutes. No credit score impact.2 Zero fees. See your actual rate today.
Tip: applying with a creditworthy cosigner may improve your approval odds and lower your interest rate.
[Find My Rate](http://abe.psl.sparrowfi.com)
## How to Use This Student Loan Calculator
1
### Enter your loan details
Start with the amount you need to borrow and the interest rate. If you're not sure about rates, start by comparing common numbers like 4%, 8%, and 12% to better understand the potential range of costs.
f
2
### Choose your repayment term
Select how long you want to take to repay: 5, 7, 10, 15, or 20 years. Shorter terms mean higher monthly payments but less interest paid overall.
3
### Select an in-school payment option
This is where things get interesting. You can defer all payments, pay just the interest, pay a partial amount, or start full payments while still in school.
4
### Compare scenarios
Not sure which option is right? Save different configurations and compare them side-by-side. Export as a PDF to review later or share with family.
## What the Calculator Shows You
### Monthly Payment While in School
What you’ll pay each month before graduation, based on the payment option you select. For deferred loans, this is $0.
### Monthly Payment After Graduation
Your payment once repayment begins. This is the number that will show up on your budget for years, so make sure it’s manageable.
### Total Interest
The true cost of borrowing. This is the difference between what you borrow and what you’ll actually pay back. It’s often larger than people expect.
### Total Cost
The full amount you’ll pay over the life of the loan, including principal and interest. This is the number that matters most.
## How In-School Payments Impact Total Loan Cost
Most calculators don’t show this, but what you pay while in school has a significant impact on your total loan cost.
#### Fully Deferred
No payments during school. Interest accrues and gets added to your principal at the end of your grace period (capitalization). This is the most expensive option long-term, but it preserves cash while you’re a student.
#### Interest-Only
Pay just the monthly interest while in school. Your balance stays the same, and nothing capitalizes. A good middle ground if you can afford $50-$200/month.
#### Partial Interest
Minimum monthly payments of $25 or $50 per month reduces the amount that capitalizes, lowering your total cost.
#### Immediate Repayment
Start full payments right away. Your balance goes down while you’re in school, and you’ll have a shorter repayment period after graduation. Best if you have income from work or family support.
## Understanding Your Results
### If your monthly payment feels too high:
Try extending the repayment term. This lowers the monthly payment but increases total interest. Or consider borrowing less if possible.
### If your total interest seems alarming:
It often is. A $30,000 loan at 7.5% over 10 years costs about $12,700 in interest. Over 15 years, that jumps to $19,600. This is why shorter terms and in-school payments matter.
### If you're comparing Abe to other loans:
Every loan is different, and may include different terms, features and benefits. Make sure you understand what’s included in each estimate so you’re comparing similar scenarios.
## Frequently Asked Questions
### What interest rate should I use?
Private student loan rates typically range from 4% – 17% depending on your creditworthiness. Trying 4%, 8% and 12% give you a range of estimates to start.
### Does this calculator include fees?
No, because Abe® doesn’t charge origination fees, application fees, late fees, or prepayment penalties. If you’re comparing to loans that do charge fees, factor those in separately.
### What happens if I can't make student loan payments after graduation?
Abe offers deferment and forbearance options for financial hardship,11 job loss,11 natural disasters,22 and medical situations.12 Abe also offers reduced payment programs and term extensions.21 But these are last resorts, not features to plan around.
### Should I choose fixed or variable rate?
This calculator models fixed rates. Fixed rates stay the same for the life of your loan, making budgeting predictable.5 Variable rates start lower but can increase over time based on market conditions. For longer repayment terms, fixed is generally safer.
### How accurate is this calculator?
The math is accurate for the inputs you provide. Your actual loan terms, including rate and monthly payment, will be confirmed when you apply. Calculations are estimates based on the assumptions shown.
## Take the next step and find your personalized rate.
Prequalify in minutes. No credit score impact.2 Zero fees. See your actual rate today.
Tip: applying with a creditworthy cosigner may improve your approval odds and lower your interest rate.
[Find My Rate](http://abe.psl.sparrowfi.com)
---
### [News & Reviews](https://www.abestudentloans.com/news-reviews/)
**Published:** November 20, 2025
**Author:** abelending
**Content:**

# News & Reviews
For all media inquiries email [\[email protected\]](/cdn-cgi/l/email-protection#620603150c4c100b0c05070e220b0c01070c1607100e114c010d0f)
## [The College Investor – New Graduate School Loan Limits Start July 1: What Students Need to Know](https://www.abestudentloans.com/news/the-college-investor-new-graduate-school-loan-limits-start-july-1-what-students-need-to-know/)
Jun 19, 2026 | [News](https://www.abestudentloans.com/category/news/)
[read more](https://www.abestudentloans.com/news/the-college-investor-new-graduate-school-loan-limits-start-july-1-what-students-need-to-know/)
---
### [Undergraduate Sweepstakes 2026 Official Rules](https://www.abestudentloans.com/resources/scholarships/undergraduate-college-scholarship-sweepstakes/official-rules/)
**Published:** March 18, 2026
**Author:** abelending
**Content:**
# **THE ABE PLAIN, HONEST SCHOLARSHIP SWEEPSTAKES
OFFICIAL RULES**
**NO PURCHASE NECESSARY TO ENTER OR WIN. MAKING A PURCHASE WILL NOT IMPROVE YOUR CHANCES OF WINNING.**
**ALL DISPUTES WILL BE RESOLVED SOLELY BY BINDING ARBITRATION AND ENTRANTS WAIVE THE ABILITY TO BRING CLAIMS IN A CLASS ACTION FORMAT.**
**SWEEPSTAKES ENTRY PERIOD:** **The Abe Plain, Honest Scholarship Sweepstakes** (the “Sweepstakes”) begins at 12:00:00 AM Eastern Time (“ET”) on Wednesday, April 1, 2026 and ends at 11:59:59 PM ET on Thursday, December 31, 2026 (the “Sweepstakes Period”). Within the Sweepstakes Period, there are nine (9) monthly Entry Periods (each, an “Entry Period”) and nine (9) corresponding Random Drawings (each, a “Drawing”) as defined in the “Entry Periods & Drawings Schedule” below. Entries must be received during an Entry Period to be eligible for that Entry Period’s drawing and prize. Non-winning entries for an Entry Period will not roll over to subsequent Entry Periods. Sponsor’s computer is the official timekeeping device for this Sweepstakes.
**ENTRY PERIOD & DRAWINGS SCHEDULE**
**Entry Period #****ENTRY PERIODS**
**All eligible entries must be received between:**
**Drawing Date:**
On or about:
**\# of Prizes per Entry Period****Entry Period Start:**
**12:00:00 AM ET on:**
**Entry Period End:**
**11:59:59 PM ET on:**
1 04/01/26 04/30/26 05/07/26 1 2 05/01/26 05/31/26 06/08/26 1 3 06/01/26 06/30/26 07/07/26 1 4 07/01/26 07/31/26 08/07/26 1 5 08/01/26 08/31/26 09/08/26 1 6 09/01/26 09/30/26 10/07/26 1 7 10/01/26 10/31/26 11/09/26 1 8 11/01/26 11/30/26 12/07/26 1 9 12/01/26 12/31/26 01/07/27 1
**ELIGIBILITY:** The Sweepstakes is open to legal residents of the 50 United States, including the District of Columbia who are age 18 or older at the time of entry and who are either currently a student enrolled in an undergraduate program at an Eligible Institution or are the parent of a student enrolled in an undergraduate program at an Eligible Institution, as defined herein. An “Eligible Institution” must be: (i) based in the United States; (ii) Title IV eligible according to data from the U.S. Department of Education; and (iii) categorized as a public or private school that offers a bachelor’s degree program or higher according to the U.S. Department of Education, excluding for-profit schools (proprietary schools). Void in Puerto Rico, Guam, the U.S. Virgin Islands, outside the U.S., and wherever else prohibited by law. Employees of Monogram LLC (the “Sponsor”), US Sweepstakes & Fulfillment Company (the “Sweepstakes Administrator”) and their respective subsidiaries, affiliates, advertising and promotion agencies, and the immediate family members (spouses, parents, children, and siblings and their spouses) of, and/or those living in the same household of each, are not eligible to enter. Sweepstakes is subject to all applicable federal, state and local laws and regulations.
**HOW TO ENTER:** **During the Sweepstakes Period, visit** **and** follow all entry instructions to complete the entry form and submit to receive one (1) entry into the Sweepstakes (the “Entry”). Online entrants are subject to all notices posted online including but not limited to the Sponsor’s Privacy Policy, which can be found at .
**Limit: One (1) Entry per person per Entry Period regardless of whether entrant has more than one email address.** All entries become the property of the Sponsor and will not be acknowledged or returned.
**PRIZES/APPROXIMATE RETAIL VALUE (“ARV”)/ODDS**:
**Grand Prizes:** There are nine (9) Grand Prizes available to be won, one (1) for each Entry Period. Each Grand Prize consists of $1,500 awarded in the form of a check **The ARV of Grand Prize: $1,500 each.**
**The total ARV of all prizes available to be won: $13,500.**
Odds of winning will depend upon the total number of eligible entries received for each Entry Period.
There is a limit of one (1) Grand Prize per household.
**RANDOM DRAWING:** Random drawings will be conducted by the Sweepstakes Administrator, an independent representative of the Sponsor, whose decisions are final.
The potential Grand Prize winners will be selected in a series of random drawings from among all eligible entries received within the corresponding Entry Period on or about the corresponding Random Drawing Date indicated in the Entry Period & Drawings Schedule in the “Sweepstakes Entry Periods” section of these Official Rules.
**WINNER NOTIFICATION & VERIFICATION: Potential winners will be notified via email and/or phone, and will be required to sign and return, within seven (7) days of notification, an Affidavit of Eligibility, a Liability Waiver and where allowable, a Publicity Release (collectively, “the Releases”).** Noncompliance will result in disqualification and an alternate winner may be selected. **The prize package will be awarded within approximately 45 days after the winner is verified.**
If a winner is otherwise eligible under these Official Rules but is nevertheless deemed a minor in their state of primary residence, the prize will be awarded in the name of winner’s parent or legal guardian who will be required to execute and return the Releases on minor’s behalf, as applicable.
If a prize notification or prize is returned as undeliverable, or if winner is found to be ineligible or not in compliance with these Official Rules, that winner will be disqualified, and the prize may be awarded to an alternate winner in a separate random drawing. If Sponsor is unable to determine and verify a potential winner after repeated alternate drawings or if Sponsor fails to receive a sufficient number of entries to correspond to the number of prizes available to be awarded, Sponsor reserves the right to not award such prize(s).
**PRIZE CONDITIONS:** Prizes are not redeemable for cash, assignable, transferable and may not be substituted except at Sponsor’s sole discretion. Sponsor reserves the right to substitute a prize of equal or greater value at its discretion. Any other incidental expenses on prize not specified herein are the winner’s sole responsibility.
Winner is responsible for all federal, state, local and income taxes associated with winning prize.
Except where prohibited by law, entry and acceptance of prize constitute permission to use winner’s name, prize won, hometown, likeness, video recordings, photographs, and statements for purposes of advertising, promotion and publicity (including online posting) in any and all media now or hereafter known throughout the world in perpetuity, without additional compensation, notification or permission.
**GENERAL:** Although subsequent attempts to enter may be received, only the first complete entry received from a particular entrant will be eligible; subsequent attempts by the same person to enter, including entries submitted with an alternate email address, will be disqualified.
Participating entrants agree to these Official Rules and the decisions of the Sponsor and the Sweepstakes Administrator, and release the Sponsor, the Sweepstakes Administrator and their affiliated companies, and all other businesses involved in this Sweepstakes, as well as the employees, officers, directors and agents of each (the “Released Parties”), from all claims and liability relating to their participation in the Sweepstakes, and the acceptance and use/misuse of the prize offered. Participating entrants assume all liability for and Released Parties shall be held harmless against any liability for any injury, losses or damages of any kind to persons, including personal injury or death, or injury to property caused or claimed to be caused in whole or in part, directly or indirectly, by participation in this Sweepstakes, acceptance, possession, or use/misuse of the prize, or any claims based on publicity rights, defamation or invasion of privacy, or merchandise delivery. Sponsor is not responsible for any typographical or other error in the printing of the offer, administration of the Sweepstakes or in the announcement of the prize.
In the event of a dispute over the identity of an entrant, entry will be deemed submitted by the “Authorized Account Holder” of the e-mail address submitted at time of entry. Authorized Account Holder means the natural person who is assigned to an e-mail address by an Internet access provider, online service provider, or other organization that is responsible for assigning e-mail addresses for the domain associated with the submitted e-mail address. Sponsor may ask any entrant or potential winner to provide Sponsor with proof, to Sponsor’s satisfaction, that such party is the authorized account holder of the email address associated with the entry. Entry materials/data that have been tampered with or altered, or mass entries or entries generated by a script, macro or use of automated devices are void. The Released Parties are not responsible for: (i) lost, late, misdirected, damaged or illegible entries; or (ii) error, omission, interruption, deletion, defect, delay in operations or transmission, theft or destruction or unauthorized access to or alterations of entry materials, or for technical, network, telephone equipment, electronic, computer, hardware or software malfunctions of any kind, or inaccurate transmission of or failure to receive entry information by Sponsor on account of technical problems or traffic congestion on the Internet or at any web site or any combination thereof; or (iii) any injury or damage to entrant’s or any other person’s computer related to or resulting from participating in the Sweepstakes. By participating in the Sweepstakes, entrant (i) agrees to be bound by these official rules, including all eligibility requirements, and (ii) agrees to be bound by the decisions of Sponsor and the Sweepstakes Administrator, which are final and binding in all matters relating to the Sweepstakes. Failure to comply with these official rules may result in disqualification from the Sweepstakes.
Sponsor reserves the right to cancel, suspend and/or modify the Sweepstakes, or any part of it, if any fraud, technical failures or any factor beyond Sponsor’s reasonable control impairs the integrity or proper functioning of the Sweepstakes, as determined by Sponsor. If, for any reason, the Sweepstakes cannot be run as planned, Sponsor may disqualify any suspect entries or individuals from the Sweepstakes and any sweepstakes it sponsors and (a) suspend the Sweepstakes and modify the Sweepstakes to address the impairment, then resume the Sweepstakes in a manner that best conforms to the spirit of these Official Rules; and/or (b) award the prize at random from among the eligible, non-suspect entries received up to the time of the impairment.
THE RELEASED PARTIES ARE NOT RESPONSIBLE IF THIS SWEEPSTAKES CANNOT BE ADMINISTERED OR CONDUCTED OR ANY PRIZE CANNOT BE AWARDED DUE TO CANCELLATIONS, DELAYS, OR INTERRUPTIONS RESULTING OR ARISING FROM ACTS OF GOD, WAR, OR TERRORISM, CIVIL UNREST, STRIKES, SUPPLY SHORTAGES, NATURAL DISASTERS, WEATHER, EPIDEMICS, COMPLIANCE WITH ANY LAW OR ORDER OF A GOVERNMENTAL AUTHORITY, OR ANY OTHER SIMILAR ACT, EVENT, OR OCCURRENCE BEYOND THE REASONABLE CONTROL OF THE SPONSOR. BY PARTICIPATING IN THIS SWEEPSTAKES, PARTICIPANT AGREES THAT THE RELEASED PARTIES WILL NOT BE RESPONSIBLE OR LIABLE FOR ANY INJURIES, DAMAGES, OR LOSSES OF ANY KIND, INCLUDING DIRECT, INDIRECT, INCIDENTAL, CONSEQUENTIAL, OR PUNITIVE DAMAGES TO PERSONS, INCLUDING DEATH, OR TO PROPERTY ARISING OUT OF ACCESS TO AND USE OF ANY WEBSITE ASSOCIATED WITH THIS SWEEPSTAKES OR THE DOWNLOADING FROM AND/OR PRINTING MATERIAL DOWNLOADED FROM SUCH SITE, AS APPLICABLE. FURTHER, SPONSOR SHALL NOT BE RESPONSIBLE FOR ANY CANCELLATIONS, DELAYS, DIVERSIONS, CHANGES IN SERVICE OR ACCOMMODATIONS OR SUBSTITUTIONS, OR FOR ANY ACTS OR OMISSIONS BY ANY THIRD PARTIES BEYOND ITS REASONABLE CONTROL, INCLUDING AIR CARRIER(S) AND OTHER TRANSPORTATION COMPANIES; LODGING, RESTAURANT OR OTHER HOSPITALITY PROVIDERS; ENTERTAINMENT PROVIDERS, VENUES OR ARTISTS; OR OTHER THIRD PARTY PROVIDERS SUPPLYING ANY SERVICES OR COMPONENTS OF THE PRIZE(S) TO WINNERS AND/OR THEIR GUESTS, OR FOR ANY RESULTING INJURIES, INCLUDING MONEY DAMAGES, COSTS AND EXPENSES, PROPERTY DAMAGES, PERSONAL INJURIES OR DEATH RESULTING THEREFROM.
**LEGAL WARNING:** ANY ATTEMPT BY AN INDIVIDUAL, WHETHER OR NOT AN ENTRANT, TO DAMAGE, DESTROY, TAMPER OR VANDALIZE THIS WEB SITE OR INTERFERE WITH THE OPERATION OF THE SWEEPSTAKES, IS A VIOLATION OF CRIMINAL AND CIVIL LAWS AND SPONSOR RESERVES THE RIGHT TO SEEK DAMAGES AND DILIGENTLY PURSUE ALL REMEDIES AGAINST ANY SUCH INDIVIDUAL TO THE FULLEST EXTENT PERMITTED BY LAW.
**GOVERNING LAW AND LIMITATION OF LIABILITY:** All issues and questions concerning the construction, validity, interpretation and enforceability of these Official Rules or the rights and obligations of entrants, Sponsor or the Released Parties in connection with the Sweepstakes will be governed by and construed in accordance with the internal laws of the Commonwealth of Massachusetts, without giving effect to any choice of law or conflict of law rules or provisions that would cause the application of any other laws.
BY ENTERING THE SWEEPSTAKES, ENTRANT AGREES THAT TO THE EXTENT PERMITTED BY APPLICABLE LAW: (A) ANY AND ALL DISPUTES, CLAIMS AND CAUSES OF ACTION ARISING OUT OF OR CONNECTED WITH THE SWEEPSTAKES, OR ANY PRIZE AWARDED, WILL BE RESOLVED INDIVIDUALLY, WITHOUT RESORT TO ANY FORM OF CLASS ACTION; (B) ANY AND ALL CLAIMS, JUDGMENTS AND AWARDS WILL BE LIMITED TO ACTUAL THIRD-PARTY, OUT-OF-POCKET COSTS INCURRED (IF ANY) NOT TO EXCEED TEN DOLLARS ($10.00), BUT IN NO EVENT WILL ATTORNEYS’ FEES BE AWARDED OR RECOVERABLE; (C) UNDER NO CIRCUMSTANCES WILL ANY ENTRANT BE PERMITTED TO OBTAIN ANY AWARD FOR, AND ENTRANT HEREBY KNOWINGLY AND EXPRESSLY WAIVES ALL RIGHTS TO SEEK, PUNITIVE, INCIDENTAL, CONSEQUENTIAL OR SPECIAL DAMAGES, LOST PROFITS AND/OR ANY OTHER DAMAGES, OTHER THAN ACTUAL OUT OF POCKET EXPENSES NOT TO EXCEED TEN DOLLARS ($10.00), AND/OR ANY RIGHTS TO HAVE DAMAGES MULTIPLIED OR OTHERWISE INCREASED; AND (D) ENTRANTS’ REMEDIES ARE LIMITED TO A CLAIM FOR MONEY DAMAGES (IF ANY) AND ENTRANT IRREVOCABLY WAIVES ANY RIGHT TO SEEK INJUNCTIVE OR EQUITABLE RELIEF. SOME JURISDICTIONS DO NOT ALLOW THE LIMITATIONS OR EXCLUSION OF LIABILITY, SO THE ABOVE MAY NOT APPLY TO YOU.
**DISPUTES****:** The parties hereto each agree to finally settle all disputes only through arbitration; provided, however, the Released Parties shall be entitled to seek injunctive or equitable relief in the state and federal courts in Suffolk County, MA and any other court with jurisdiction over the parties. In arbitration, there is no judge or jury and review is limited. The arbitrator’s decision and award is final and binding, with limited exceptions, and judgment on the award may be entered in any court with jurisdiction. The parties agree that, except as set forth above, any claim, suit, action or proceeding arising out of or relating to this Sweepstakes shall be resolved solely by binding arbitration before a sole arbitrator under the Consumer Arbitration Rules of the American Arbitration Association (“AAA”) or any successor to AAA. If an in-person hearing is required, then it will take place in Boston, MA. The federal or state law that applies to these Official Rules will also apply during the arbitration. Disputes will be arbitrated only on an individual basis and will not be consolidated with any other proceedings that involve any claims or controversy of another party, including any class actions; provided, however, if for any reason any court or arbitrator holds that this restriction is unconscionable or unenforceable, then the agreement to arbitrate doesn’t apply and the dispute must be brought in a court of competent jurisdiction in Boston, MA.
**PRIVACY:** As a condition of entering the Sweepstakes, each entrant gives consent for Sponsor to obtain and deliver their name, address and other information to third parties, including Sweepstakes Administrator, for the purpose of administering this Sweepstakes and to comply with applicable laws, regulations and rules, including, without limitation, the storing of your personal information for purposes of complying with state record retention requirements. Any information entrant provides to Sponsor may be used to communicate with entrant in relation to this Sweepstakes or on a Sweepstakes winner’s list. Personal information collected from entrants are subject to the Sponsor’s Privacy Policy, which can be found at .
**WINNER CONFIRMATION REQUEST: For a written confirmation of the winner (available after 01/07/27), send a stamped, self-addressed envelope (no later than 02/08/27), to:** **The Monogram Abe Plain, Honest Scholarship Sweepstakes** Winner Confirmation Request, PO Box 654, Social Circle, GA 30025-0654.
**SPONSOR:** Monogram LLC, 200 Clarendon Street, 20th Floor, Boston, MA 02116.
**SWEEPSTAKES ADMINISTRATOR: US Sweepstakes & Fulfillment Company, 1630 30th St., STE A593, Boulder, CO 80301. 1-800-620-6044**
**Void outside the US, in Puerto Rico, Guam, the U.S. Virgin Islands and wherever else prohibited by law.**
---
### [Press Releases](https://www.abestudentloans.com/press-releases/)
**Published:** November 20, 2025
**Author:** abelending
**Content:**
# Press Releases
For all press inquiries email [\[email protected\]](/cdn-cgi/l/email-protection#325653455c1c405b5c55575e725b5c51575c4657405e411c515d5f)
## [Keeping Graduate Students’ Goals on Course: Abe Announces New Programs and Policies](https://www.abestudentloans.com/press-release/keeping-graduate-students-goals-on-course-abe-announces-new-programs-and-policies/)
May 13, 2026
BOSTON—May 9, 2026—AbeSM, which takes a transparent, built-for-real-life approach to private student lending, announces new policies and programs to help keep graduate students and their families on a steady path toward achieving their goals. The changes apply to...
[read more](https://www.abestudentloans.com/press-release/keeping-graduate-students-goals-on-course-abe-announces-new-programs-and-policies/)
---
### [Scholarship Sweepstakes](https://www.abestudentloans.com/resources/scholarships/birthday-scholarship/)
**Published:** May 27, 2025
**Author:** abelending
**Content:**
# Thank You & Congratulations
**to all of the Abe Birthday Scholarship Sweepstakes winners!**
Over 15 weeks, AbeSM awarded a total of $20,000 in scholarships to 16 deserving students through the Abe Scholarship Sweepstakes. We’re proud to have helped support students on their college journey, and grateful to everyone who entered along the way.

## Abe Birthday Scholarship Sweepstakes Winners
Congratulations to the winners below!
### $5,000 Grand Prize Winner
#### **Nat P.**
Junior, Jacksonville University
### $1K Weekly Winners
#### Anas R.
Senior, San Jose State University
Week 3
“I’m currently studying Mechanical Engineering at San Jose State, and this money is going to be a big help paying off my tuition next semester!”
#### Gianni G.
Junior, Florida State University
Week 5
“The money will be a tremendous help in covering the cost of my books for the upcoming fall semester. My goal is to become a physical therapist, and this support brings me one step closer to achieving that dream.”
#### Brianna E.
Sophomore, California State University Northridge
Week 9
“Thank you to Abe’s Scholarships for this opportunity! With the money given to me I will put it towards any college expenses, like buying books and school needs. I am currently studying to major in Business Marketing.”
**Kambria B.**
Freshman, Phoenix College
Week 1
**Dahje W.**
Junior, Savannah State Univeristy
Week 2
**Anas R.**
Senior, San Jose State University
Week 3
**Seohyun K.**
Junior, Auburn Univeristy
Week 4
**Gianni G.**
Junior, Florida State University
Week 5
**Cynthia R.**
Sophomore, Liberty University
Week 6
**Isabella T.**
Sophomore, Hillsborough Community College
Week 7
**D’Zariya M.**
Junior, Western Illionois University
Week 8
**Brianna E.**
Sophomore, California State University Northridge
Week 9
**Mackenzie K.**
Sophomore, California State University Northridge
Week 10
**Emma Z.**
Sophomore, Whitworth University
Week 11
**Onyinyechi O.**
Sophomore, University of Texas at Arlington
Week 12
Habeebah L.
Junior, Brigham Young University Idaho
Week 13
Rhiannon B.
Sophomore, Union University
Week 14
Grace R.
Freshman, Western Governors University
Week 15
### **Find the loan that fits your goals.**
No matter where you are headed on your education journey, Abe can help you get there.

#### Undergraduate
For undergraduate students enrolled in a bachelor’s or associate’s degree program.
**Learn More**

#### Graduate
For graduate students enrolled in a degree or certificate program.
**Learn More**

#### Law
For graduate students enrolled in a Law degree program.
**Learn More**

#### MBA
For graduate students enrolled in an MBA degree program.
**Learn More**

#### Medical
For graduate student enrolled in a doctoral degree program: Doctor of Medicine (MD), Osteopathic Medicine (DO), Veterinary Medicine (DVM, VMD), or Podiatric Medicine (PM).
**Learn More**

#### Dental
For graduate students enrolled in a dentistry degree program (Pediatric Dentistry, Periodontics, Oral Surgeon etc.).
**Learn More**

#### Healthcare Professionals
For graduate students enrolled in a nursing, pharmacy, or allied health professional (e.g., Dietitians, OT, Speech Pathologist, Audiologist, Dental Hygienist etc.) degree program.
**Learn More**
---
### [Become a Partner](https://www.abestudentloans.com/partnership-program/)
**Published:** February 3, 2026
**Author:** abelending
**Content:**
# Partner with Abe.
## Help your members, customers, and students access plain, honest student loans. No complicated terms. No hidden fees. Just straightforward financing for college.
[Get Started](/cdn-cgi/l/email-protection#6d1d0c1f1903081f1e05041d1e2d0c0f081e19180908031901020c031e430e0200)
## What makes partnering with Abe different?
Your customers get market-leading rates, flexible options and terms, and robust product features that are designed with real life in mind. No confusing terms. No customer service nightmares. No surprises. Just straightforward student loans.
#### Dependable Service
From application to repayment, we handle every step with care so your customers get dependable service and your reputation stays protected.
### Turnkey Program
We handle underwriting, disbursement, customer service and overall loan management. You focus on what you do best — serving your community.
#### Earn Referral Fees
Get paid when loans are funded, without the burden of overseeing loan servicing or compliance management.
#### Marketing Support
Access co-branded content, email campaigns, banner ads, and marketing resources tailored to your audience.
### Competitive Rates
Consistently among the lowest in the industry, with straightforward qualification criteria and no promotional gimmicks.
#### Real People, Real Support
When your customers have questions, they get straight answers from real humans. No phone tree nightmares. No passing the buck. Just reliable support.
[Partner with Abe](/cdn-cgi/l/email-protection#4e3e2f3c3a202b3c3d26273e3d0e2f2c2b3d3a3b2a2b203a22212f203d602d2123)
## A complete suite of student loan products.
From traditional four-year degrees to graduate programs and post-bachelor graduate certificates, Abe’s comprehensive product suite means one partnership serves your entire community’s educational financing needs.


### Undergraduate Loans
For students pursuing associate or bachelor’s degrees, with flexible repayment options designed to fit real life.
- Four repayment options including full deferment
- More repayment terms than most competitors
- Summer and winter-term course coverage
### Post-Bachelor Graduate Certificates
For career-focused certificate programs—a growing option that too many lenders ignore.
- Flexible options for students balancing work and education
- Same transparent terms as traditional degree programs
### Graduate Loans
For Dental, Healthcare Professionals, Law, MBA, and Medical degree programs, designed with the unique needs of graduate students in mind.
- Additional deferment for internships and residencies
- Higher loan limits for advanced degrees
- Extended payment relief for borrowers that need more runway to launch their careers
## Ready to offer something better?
Whether you’re a financial institution, association, school, or advisor, partnering with Abe means you can offer your community a student loan experience that puts your customers first.
[Partner with Abe](/cdn-cgi/l/email-protection#a6d6c7d4d2c8c3d4d5cecfd6d5e6c7c4c3d5d2d3c2c3c8d2cac9c7c8d588c5c9cb)
---
### [Home for the Holidays Scholarship Sweepstakes](https://www.abestudentloans.com/resources/scholarships/scholarship-holiday2025/)
**Published:** November 1, 2025
**Author:** abelending
**Content:**
# Thank You & Congratulations
**to all of this season’s Home for the Holidays Scholarship Sweepstakes winners!**
AbeSM celebrated the season of giving by awarding a total of $9,000 in scholarships to 6 lucky students and parents. Each winner received a $1,500 scholarship to help bring a little more joy home for the holidays. We’re proud to have supported students and families as they work toward their education goals, and we appreciate everyone who took part in the sweepstakes.

## Abe Home for the Holidays
Scholarship Sweepstakes Winners
Congratulations to the winners below!

**Patrick A.**
Senior, University of Evansville
“I am studying mechanical engineering and will graduate this May. I intend to use the money for tuition.”

**Sarah M.**
Parent of Senior, Marquette
“Proud mom of a college kid who will use the $ for books.”

**Caleb C.**
Freshman, Vermont State University
“I will be using this money towards my college tuition expenses at Vermont State University, to continue my learning in the Mechanical Engineering program.”
**Abria W.**
Junior, University of Kentucky
“I will be using the money for my tuition and books. My major is Food Biosciences. I plan on being a food engineer after I graduate.“
**Kristina T.**
Senior, Chapman University
**Latitia C.**
Junior, CUNY John Jay College
Additional Award Recipient
### **Find the loan that fits your goals.**
No matter where you are headed on your education journey, Abe can help you get there.

#### Undergraduate
For undergraduate students enrolled in a bachelor’s or associate’s degree program.
**Learn More**

#### Graduate
For graduate students enrolled in a degree or certificate program.
**Learn More**

#### Law
For graduate students enrolled in a Law degree program.
**Learn More**

#### MBA
For graduate students enrolled in an MBA degree program.
**Learn More**

#### Medical
For graduate student enrolled in a doctoral degree program: Doctor of Medicine (MD), Osteopathic Medicine (DO), Veterinary Medicine (DVM, VMD), or Podiatric Medicine (PM).
**Learn More**

#### Dental
For graduate students enrolled in a dentistry degree program (Pediatric Dentistry, Periodontics, Oral Surgeon etc.).
**Learn More**

#### Healthcare Professionals
For graduate students enrolled in a nursing, pharmacy, or allied health professional (e.g., Dietitians, OT, Speech Pathologist, Audiologist, Dental Hygienist etc.) degree program.
**Learn More**
---
### [Degree Programs](https://www.abestudentloans.com/degrees/)
**Published:** March 10, 2024
**Author:** abelending
**Content:**

# Degree Programs
### Students’ priorities and goals have changed a lot in recent years, and America’s higher education system has evolved with them. Today, there are more pathways to completing a degree and starting that dream career than ever before. AbeSM is all for it.
[Get Your Rate](https://apply.abestudentloans.com/CWA/Apply?link_id=ABEPSL1&referrer_link=ORGANIC)
- [Undergraduate](#undergrad)
- [Graduate](#grad)
- [Certificate](#certificate)
- [Less Than Half-Time](#ltht)
## Undergraduate
Abe loans can be used to earn a Bachelor of Arts (B.A.) or Bachelor of Science (B.S.) at approved private and public degree-granting universities and colleges. You can check to see if your school is on the approved list during the application process.
## Graduate
Abe covers virtually all types of graduate degrees including:
### Doctoral (Ph.D.)
### Law Degree (J.D.)
### Doctor of Medicine (M.D.)
### Doctor of Dental Surgery (D.D.S.)
### Doctor of Veterinary Medicine (DVM)
### Master of Science in Nursing (MSN)
### Master of Public Health (MPH)
### Master of Accounting (MAcc)
### Master of Architecture (M.Arch)
Advanced degrees often require more funding. Abe’s increased aggregate loan limit[1](#f1) of $350,000 ensures you’re able to get the money you need to pay for your JD, MD, DVM, MBA or DDS degree. This is the maximum total amount of all your student loans combined, including both Private and Federal loans.
Don’t see the graduate degree you’re looking for? [Contact us.](#contact)
## Certificate Programs
More and more, students are graduating from college and going on to earn graduate certificates to gain specialized skills within their chosen field. The programs are a relatively fast and inexpensive way to gain a competitive edge in the job market and sometimes may even lead to an increase in pay. Abe is one of the few providers that lets you use your loan to pay for qualified, graduate certificate courses when you are enrolled at an approved school.
## Less Than Half-Time Enrollment
Perhaps you need to go to school part-time. Or maybe you’re just one or two credits away from your degree and need to take courses over the summer or during winter break. No problem. An Abe loan can help you get over the finish line.
---
### [Gap State](https://www.abestudentloans.com/gap-state/)
**Published:** June 18, 2024
**Author:** abelending
**Content:**
# Thank you for choosing Abe.
We really appreciate it.
### Your address is in a state where we are not yet able to lend.
The good news is we should be able to lend in your state any day now.
**Let’s stay in touch so we can let you know when to reapply.[1](#f1) We’ll also keep you in the loop on Abe’s rates and additional program benefits.**
In the meantime, the Abe [Student Loan Guide](#slg) offers honest, objective information on private student loans.
And don’t forget to enter the [Paying for College Sweepstakes](#slg)[2](#f1) for a chance to win a $1,500 scholarship.
– The Abe Team
#### The Paying For College Scholarship Sweepstakes[2](#f2)
Enter monthly for your chance to win a $1,500 scholarship. The award can be used for books, supplies, or whatever you may need for school. A new scholarship is awarded every month, and you can come back and enter at any time.
[Enter Sweeps](https://sweeps.smartborrowing.org?link_id=ABEPSL1&referrer_link=ORGANIC)
#### A Plain, Honest Guide to Private Student Loans
Abe believes that if you give people the honest, straightforward information they need to make good decisions, they will. That’s why we created the Abe Guide to Student Loans and invite you to download it here.
[Download Our Guide](https://www.abestudentloans.com/resources/)
---
### [Consent to Electronic Communications](https://www.abestudentloans.com/consent-to-electronic-communications/)
**Published:** April 8, 2024
**Author:** abelending
**Content:**

# Consent to Electronic Communications
DR Bank (“Lender”) is required by law to provide you certain information in writing. We will provide that information directly or through loan origination and servicing agents, including Monogram LLC. We may provide this information to you electronically, instead of in a paper copy, with your prior consent. Described below are the terms and conditions for us to provide you with electronic communications. Please read this Consent carefully.
### In this Consent:
- “You” and “your” means the person giving this consent, and also any co‐signer, authorized signer, or authorized representative.
- “Electronic Communications” means each disclosure, notice, agreement, fee schedule, statement, record, document, and other information we provide to you, or that you sign or submit or agree to at our request, including any notices or disclosures required by applicable law or regulation, sent by us to you electronically.
- The words “include” and “including,” when used at the beginning of a list of one or more items, indicate that the list contains examples – the list is not exclusive or exhaustive, and the items in the list are only illustrative. They are not the only possible items that could appear in the list.
### 1. Consent to Electronic Communications
By entering the code at the end of this Consent on our website, you specifically agree to receive and/or obtain Electronic Communications. This includes Electronic Communications related to your account from Lender or third party servicers. You specifically consent to receive electronic mail (email) and online communications and disclosures regarding your loan instead of receiving them by regular U.S. mail. Except as noted below or otherwise at our discretion communications will not be furnished on paper. Your consent will apply to all information we send to you, or disclose or communicate to you online, relating to your loan, including notices regarding your application and your credit agreement, and any disclosures that are required by law to be in writing, including, without limitation, Truth In Lending Act disclosures and tax forms. We may deliver a disclosure or notice to you by posting it to your online account, including adverse action notices in the event your application is declined, and may, at our discretion, chose to send you an email notification of the posting as a courtesy. Your consent remains in effect until you give us notice that you are withdrawing it.
### 2. Paper Version of Electronic Communications
You may request a paper version of an Electronic Communication. You acknowledge that we reserve the right to charge you a reasonable fee for the production and mailing of paper versions of Electronic Communications, unless charging a fee is prohibited by applicable law. To request a paper copy of an Electronic Communication, please call us at 1‐855‐444‐4645. Please note that a request for a paper version of one or more Electronic Communications will not by itself constitute a withdrawal of consent to receive Electronic Communications.
### 3. Revocation of Consent to Electronic Communications
You have the right to withdraw your consent to receive Electronic Communications at any time by calling us at 1‐855‐444‐4645. Your withdrawal of consent will become effective after we have had a reasonable opportunity to act upon it. Please note that withdrawing your consent to receive Electronic Communications may slow the speed at which we can complete certain steps in the loan application process.
### 4. Valid and Current Email Address, Notification and Updates
You agree to promptly notify us of any change in your telephone number, mailing address, or email address. You may modify your telephone number, mailing address, or email address by calling us at 1‐ 855‐444‐4645.
### 5. Hardware, Software and Operating System Requirements
You must be able to view, print, and retain information presented on‐screen in order to receive Electronic Communications. By entering the code at the end of this Consent on our website, you confirm that you are able to view Hyper Text Markup Language (HTML) files and read Adobe PDF files, and that you are able to print and save HTML and Adobe PDF files. If you are not able to do this, please make sure that you have Adobe Acrobat Reader installed on your computer. It can be downloaded for free at .
You also confirm that you have access to a Current Version of an Internet browser that we support: Google Chrome, Microsoft Internet Explorer, Microsoft Edge, Mozilla Firefox and Safari. “Current Version” means a version of the software that is currently being supported by its publisher.
### 6. Changes to Hardware and Software Requirements
If our hardware or software requirements change, and that change would create a material risk that you would not be able to access or retain your Electronic Communications, we will give you notice of the revised hardware or software requirements.
### 7. By Accepting This Consent and Entering the Code Below On Our Website, You Confirm That:
- You have the necessary hardware and software described above;
- You can access and read this Consent to Electronic Communications;
- You have an active email account;
- You can print this disclosure on paper, or save the disclosure to a place where you can print it, for future reference and access; and
- You agree to the terms and conditions of this
### Use This Access Code to Consent to Electronic Communications:
It is recommended that you print or save a copy of this Consent for future reference.
---
### [Terms & Conditions of Use](https://www.abestudentloans.com/terms-conditions-of-use/)
**Published:** April 8, 2024
**Author:** abelending
**Content:**

# Terms & Conditions of Use
Please carefully review the following terms and conditions of use (the “Terms of Use”) that govern your use of this website, associated sites linked to this website and to any mobile device-enabled website content and mobile application (collectively, the “Site”) and the products and services offered on the Site. Please also read our [](https://www.monogramllc.com/privacy-policy.php) regarding the information that you provide to us. The Site is the property of Monogram LLC. In these Terms of Use “we,” “us,” and “our” means Monogram and its subsidiaries and affiliates.
BY USING THE SITE, YOU AGREE TO THESE TERMS OF USE; IF YOU DO NOT AGREE, DO NOT USE THE SITE.
Monogram reserves the right at its sole discretion, to change, modify, add or remove portions of these Terms of Use and our Privacy Policy, at any time. Monogram also reserves the right to modify or discontinue, temporarily or permanently, the Site for any reason, at its sole discretion, with or without notice to you. You agree to check these Terms of Use and our Privacy Policy periodically for changes. Your continued use of the Site following the posting of changes will mean that you accept and agree to the changes.
### Privacy
Your privacy is very important to us. Please review our online [Privacy Policy](https://abelending.wpenginepowered.com/monogram-privacy-policy/) (which also governs your visit to the Site) to understand how we treat your personal information and protect your privacy when you use the Site. As discussed in our [Privacy Policy](https://abelending.wpenginepowered.com/monogram-privacy-policy/), we may share information with your school or any other party (such as the cosigner) on your loan.
By submitting an application, you understand and agree that Monogram, DR Bank and their respective agents will provide personally identifiable information to your school, including information about your loan or loan application, and you authorize your school to provide information and certification to us, DR Bank about you, including your attendance, financial aid, and status.
Additionally, by using the Site, you acknowledge and agree that Internet transmissions are never completely private or secure. You understand that any message or information you send to the Site may be read or intercepted by others, notwithstanding Monogram’s efforts to protect such transmissions.
### Your Use of the Site
As long as you comply with these Terms of Use, Monogram grants you a personal, non-exclusive, non-transferable, limited privilege to enter and use the Site. You agree to abide by all applicable local, state, national, and international laws and regulations in regard to your use of the Site. The Site is available only to individuals who are permitted to use it under applicable law. You must be of the age of majority in your state, which is 18 in most states, but 21 in Puerto Rico, 19 in Alabama and Nebraska (if you are a ward of the state). You may use the Site and apply for a loan if you are 17 if you are applying with a cosigner over the age of 18 (or age of majority in your state, whichever is greater). If you do not meet these age requirements, please do not use our Site.
You agree that all access and use of the Site and its contents is at your own risk. You agree to be solely responsible for your actions and the contents of your transmissions through the Site. You agree not to impersonate any person or entity or falsely state or otherwise misrepresent your identity or affiliation with a person or entity. You agree that we may terminate your password, account, or use of the Site in Monogram’s sole discretion for any reason as permitted by law.
By using the Site, you acknowledge that we specifically disclaim any liability (whether based in contract, tort, negligence, strict liability or otherwise) for any direct, indirect, incidental, common law, statutory, regulatory, consequential, compensatory, punitive, or special damages arising out of or in any way connected with your access to or use of the Site (even if we have been advised of the possibility of such damages) including, but not limited to, any liability associated with any viruses which may infect your computer equipment. In addition, Monogram may post notices or links to notices through the Site to inform you of changes to the Terms of Use, the Site, or other matters of importance.
You agree that you will not use any robot, spider or other automatic device, or manual process to monitor or copy the Site or the content contained in the Site without our prior written permission. You agree that you will not use any device, software or routine to interfere or attempt to interfere with the proper working of the Site or any information or technology obtained from the Site.
Calculators and tools on the Site provide you with ESTIMATES that may be different than actual amounts.
### Products and Services
The products and services described on the Site, including their terms, conditions, availability or pricing, are subject to change at any time, without notice. The availability of the products and services described on the Site, as well as their associated fees, charges, interest rates, and balance requirements, may differ among geographic locations. By offering information about products and services on the Site no solicitation is made by Monogram (or other third party offering the product or service) to any person whose use of such information, products or services in jurisdictions where such information, products or services is prohibited by law. Your eligibility for the products and services listed on the Site is subject to the final approval and acceptance of Monogram or other third party offering the product or service, such as our partner lender.
### Application
You may be presented with the opportunity to prequalify and/or apply for a loan through the Site. All information submitted to Monogram through the Site shall be deemed and remain the property of Monogram.
When prequalifying or applying for a loan on the Site, you agree to provide accurate, true, current and complete information about yourself. If any information you provide is inaccurate, untrue, not current or incomplete, Monogram (or other third party offering the loan) has the right to terminate your loan prequalification and/or application request and to decline to provide any and all future use of the Site.
Neither Monogram nor any third-party offering products or services has any obligation to approve an application for a loan. Upon final approval of an application, your loan remains subject to executing a credit agreement.
### Communications
By accepting these Terms of Use, you expressly consent to be contacted by Monogram, our agents, representatives, affiliates, or anyone calling on our behalf for any and all purposes arising out of or relating to your application or account, which includes, but is not limited to, contacting you to see if you would like to complete and submit your application or for collection and payment purposes, at any telephone number (including any mobile telephone number), or any physical, email, or electronic address you provide or at which you may be reached. You agree we may contact you in any way, including SMS messages (including text messages) calls using prerecorded messages or artificial voice, and calls and messages delivered using automatic telephone dialing systems (auto-dialer) or an automatic texting system. Automated messages may be played when the telephone is answered, whether by you or someone else. In the event that an agent or representative calls, he or she may also leave messages on your answering machine, voice mail, or send messages via text. You certify, warrant and represent that the telephone numbers that you have provided to us are your contact numbers. You represent that you are permitted to receive calls at each of the telephone numbers you have provided to us. You agree to promptly alert us whenever you stop using a particular telephone number. MONOGRAM AND OUR AGENTS, REPRESENTATIVES, AFFILIATES AND ANYONE CALLING ON OUR BEHALF MAY USE SUCH MEANS OF COMMUNICATION DESCRIBED IN THIS SECTION EVEN IF YOU WILL INCUR COSTS TO RECEIVE SUCH PHONE MESSAGES, TEXT MESSAGES, E-MAILS OR OTHER MEANS.
1. In order to access, view, and retain SMS messages that we make available to you, you must have an SMS-capable mobile phone, an active mobile phone account with a communication service provider; and sufficient storage capacity on your mobile phone.
2. All SMS messages in electronic format from us to you will be considered “in writing.”
3. There is no service fee for SMS messages, but you are responsible for any and all charges, including but not limited to fees associated with text messaging, imposed by your communications service provider. Please consult your mobile service carrier’s pricing plan to determine the charges for sending and receiving text messages. These charges will appear on your phone bill. Message frequency depends on account status or settings. We may modify or terminate our text messaging services from time to time, for any reason, and without notice, including the right to terminate text messaging with or without notice, without liability to you.
### Electronic Signatures and Communications
DR Bank is required by law to provide you certain information in writing, which it may provide electronically with your prior consent. DR Bank also needs your consent to use electronic signatures. To receive electronic communications and use electronic signatures, you must carefully read and agree to the Consent to Electronic Communications and Signatures contained on the Site.
### Your Site Account
You may be required to create an account to use certain parts of the Site. When you create an account, you will be required to pick a username and a password. You may not disclose your username or password to any third party. If you learn of any unauthorized use of your password or account, please contact us immediately.
### Your Credit Report
We may obtain a full credit report from a consumer reporting agency in connection with your application for credit and subsequently in connection with any extension of credit, update, renewal, review or collection of your account or any other lawful purpose. Upon your request, we will inform you of the name and address of the consumer reporting agency from which we obtained your credit report. You are allowed to receive one free credit report under the Fair Credit Reporting Act from each of the three U.S. nationwide consumer reporting agencies (Experian, Equifax, and TransUnion) during any twelve-month period. You may also be able to receive free credit reports as permitted by state law (you may contact your state or local consumer protection agency or state attorney general to learn more about your rights under state law). For information on obtaining your credit reports free of charge, contact [www.annualcreditreport.com](https://www.annualcreditreport.com/), or you can contact Experian, Equifax or TransUnion, individually, at [www.experian.com](https://www.experian.com/), [www.equifax.com](https://www.equifax.com/), and [www.transunion.com](https://www.transunion.com/).
### Use of Your Credit Report
By submitting a loan application, you are certifying that you understand that the services being requested are regulated by the Fair Credit Reporting Act and that Monogram and DR Bank have a permissible purpose to obtain and use your credit report provided by a consumer reporting agency. By using the Site to request a loan rate quote or submit a loan application, you certify that you have initiated a transaction with Monogram and DR Bank and you agree that Monogram and DR Bank may order and use your personal credit profile and credit report for such transaction. You acknowledge that your credit profile and credit report information may be used to verify your eligibility for the loan for which you have applied as well as to confirm your identity to avoid fraudulent transactions in your name.
### Use of Information Provided by You
By submitting information, data, passwords, usernames, PINs, other sign-in information, materials and other content to Monogram through the Site, you are permitting Monogram, DR Bank and their respective agents to use such information for the purpose of evaluating your loan application, and potentially originating a loan to you, servicing such loan, and providing related services to you. Monogram may use and store the content to evaluate your loan rate request, loan application and to provide ongoing services to you. Monogram will store and use this information from such connected accounts for a reasonable period of time, but not more than thirty (30) days, in connection with your loan application or loan. By submitting this content to Monogram, you represent that you are entitled to submit it to Monogram for use for this purpose.
Anonymous, aggregate information, comprised of data related to your loan application or loan, may be used by us and/or our third-party vendors to conduct certain analytical research, performance tracking and benchmarking. We or our third-party vendors may publish summary or aggregate results relating to metrics comprised of research data, from time to time, and distribute or license such anonymous, aggregated research data for any purpose, including but not limited to, helping to improve products and services and assisting in troubleshooting and technical support.
### Intellectual Property
The contents of the Site including its text, graphics, images, logos, button icons, editorial content, notices, software (including html-based computer programs), and other material are protected under both United States and foreign copyright, patent, trademark, and other laws. The contents of the Site belong to Monogram (except as otherwise expressly stated). All rights, title and interests therein shall remain the property of Monogram and/or such third parties. Except with the express written consent of Monogram, the contents of the Site may not be copied, transmitted, displayed, performed, distributed (whether for compensation or otherwise), licensed, altered, framed, stored for subsequent use or otherwise used-in whole or in part-except to the extent as expressly permitted by applicable law and then only with clear and conspicuous notice of Monogram’s proprietary rights.
You are authorized solely to view and retain a copy of the pages of the Site for your own personal, non- commercial use. You may also view and make copies of relevant documents, pages, images or other materials on the Site for the purpose of transacting business with Monogram and DR Bank You agree that you will not: (i) remove or alter any author, trademark or other proprietary notice or legend displayed on the Site (or printed pages produced from the Site); or (ii) make any other modifications to any documents obtained from the Site, other than in connection with completing information required to transact business with Monogram or DR Bank
### Improper Use
As a condition of your use of the Site, you agree that you will not, and you will not take any action intended to: (i) access data that is not intended for you; (ii) invade the privacy of, obtain the identity of, or obtain any personal information about any other user of the Site; (iii) probe, scan or test the vulnerability of the Site or the Monogram network or breach security or authentication measures without proper authorization by Monogram; (iv) attempt to interfere with service to any user, host or network or otherwise attempt to disrupt our business, including, without limitation, via means of submitting a virus to the Site, overloading, “scraping,” “flooding,” “spamming,” “credential stuffing,” “mail bombing,” or “crashing;” or (v) send unsolicited email or other electronic communication, including promotions and/or advertising of products and services. Violations of system or network security may result in civil or criminal liability.
### Indemnification
You agree to defend, indemnify and hold Monogram, and its affiliates, shareholders, directors, officers, employees, agents, and independent contractors harmless from and against all losses, claims, damages and expenses, including attorney’s fees, arising out of your violation of these Terms of Use or your misuse of the Site or any of the products or services provided on the Site.
### No Warranty
Monogram does not warrant the accuracy, adequacy or completeness of the information provided on the Site and expressly disclaims liability for any errors or omissions in such information. No warranty of any kind, implied, expressed or statutory including but not limited to the warranties of non- infringement of third party rights, title, merchantability, fitness for a particular purpose and freedom from computer virus, is given in conjunction with the information.
### Links
The Site may contain links to websites maintained by non-affiliated third parties. Such websites may have Terms of Use, Privacy Policies, or security practices that are different from those of Monogram. Monogram does not endorse or recommend, and hereby disclaims any liability for, any information or products offered at such websites.
### Potential for Disruption in Services
You understand and agree that from time to time the Site may be unavailable, limited due to slow speed, or otherwise delayed. This may be caused by a wide variety of reasons outside of the control of Monogram and despite commercially reasonable processes and procedures implemented by Monogram to maintain the Site. You also understand that, from time to time, the Site may be unavailable due to regular or other maintenance. You agree that we will not be responsible for any loss, damages, costs, or expenses which you may suffer or incur, directly or indirectly, as a result of the unavailability of the Site, regardless of whether it could be shown that we could have prevented or reduced the duration of such unavailability by taking any action within our reasonable control.
### Limitation of Liability
You agree that all access and use of the Site and its contents is at your own risk. In no event shall Monogram be held liable for any damages, including without limitation direct or indirect, special, incidental, or consequential damages, losses or expenses arising in connection with the Site or any linked site or use thereof or inability to use by any party, or in connection with any failure of performance, error, omission, interruption, defect, delay in operation or transmission, computer virus or line or system failure, even if Monogram, or representatives thereof, are advised of the possibility of such damages, losses or expenses.
### Entirety, Severability and Waiver
These Terms of Use constitute the entire agreement between you and Monogram with respect to the Site and supersede all prior or contemporaneous understandings and agreements, whether written or oral, with respect to the Site. Except as expressly set forth in these Terms of Use, in the event of a conflict between these Terms of Use and any applicable terms, these Terms of Use shall govern. Any failure by Monogram to exercise any rights or enforce any of these Terms of Use shall not constitute a waiver of such rights or terms. If any provision of these Terms of Use is held to be invalid or unenforceable to any extent, the remainder of these Terms of Use shall not be affected thereby, and each provision or these Terms of Use shall be valid and enforced to the fullest extent permitted by law.
### Arbitration
Any dispute or claim relating in any way to the Site, its content or these Terms of Use (a “Claim”) will be submitted to and resolved on an individual basis by binding arbitration under the Federal Arbitration Act, 9 U.S.C. §1 et seq. (the “FAA”) before the American Arbitration Association (“AAA”) under its Consumer Arbitration Rules, in effect at the time the arbitration is brought, or before any other party mutually agreed to in writing, provided that such party must not have in place a formal or informal policy that is inconsistent and purports to override the terms of this arbitration agreement. The AAA Rules are available online at [www.adr.org](https://www.adr.org/). These terms include any party named as a co-defendant with Monogram in a Claim asserted by you.
The FAA governs the interpretation and enforcement of this provision; the arbitrator shall apply Massachusetts law to all other matters. Notwithstanding anything to the contrary, any party to the arbitration may at any time seek injunctions or other forms of equitable relief from any court of competent jurisdiction. WE EACH AGREE THAT ANY AND ALL DISPUTES MUST BE BROUGHT IN THE PARTIES’ INDIVIDUAL CAPACITY AND NOT AS A PLAINTIFF OR CLASS MEMBER IN ANY PURPORTED CLASS OR REPRESENTATIVE PROCEEDING. BY ENTERING INTO THIS AGREEMENT AND AGREEING TO ARBITRATION, YOU AGREE THAT YOU AND MONOGRAM ARE EACH WAIVING THE RIGHT TO FILE A LAWSUIT AND THE RIGHT TO A TRIAL BY JURY. IN ADDITION, YOU AGREE TO WAIVE THE RIGHT TO PARTICIPATE IN A CLASS ACTION OR LITIGATE ON A CLASS-WIDE BASIS. YOU AGREE THAT YOU HAVE EXPRESSLY AND KNOWINGLY WAIVED THESE RIGHTS.
This arbitration provision and class action waiver does not apply to any product that constitutes “consumer credit” under the Military Lending Act (or its implementing regulations) that you may obtain from or through us if you are a covered borrower under the Military Lending Act at the time you obtain such product.
IF YOU DO NOT WANT THIS ARBITRATION PROVISION TO APPLY, YOU MUST SEND US A SIGNED NOTICE WITHIN 30 CALENDAR DAYS OF THE DATE ON WHICH YOU ELECTRONICALLY SUBMIT AN APPLICATION FOR A PRODUCT OR SERVICE OFFERED THROUGH THE SITE. YOU MUST SEND THE NOTICE IN WRITING (AND NOT ELECTRONICALLY) TO MONOGRAM LLC, 200 CLARENDON STREET, 20TH FLOOR, BOSTON, MA 02116 ATTN: WEBSITE ARBITRATION OPT OUT NOTICE. YOU MUST PROVIDE YOUR NAME, ADDRESS, TELEPHONE NUMBER, LOAN NUMBER, IF APPLICABLE, AND STATE THAT YOU “OPT OUT” OF THE ARBITRATION PROVISION. OPTING OUT WILL NOT AFFECT THE OTHER PROVISIONS OF THESE TERMS OF USE OR ANY OTHER AGREEMENT GOVERNING THE SITE OR WITH MONOGRAM OR DR BANK IF YOU DO NOT OPT OUT, YOU WILL BE BOUND BY THIS ARBITRATION PROVISION IN THESE TERMS OF USE.
Please note that if you enter an agreement with Monogram or DR Bank that contains a different arbitration provision with a right to opt out, opting out of this arbitration provision is not a rejection of the arbitration provision in the other agreement. You will need to separately opt out of the arbitration provision in the other agreement if you do not want it to apply.
ANY CAUSE OF ACTION OR CLAIM YOU MAY HAVE ARISING OUT OF OR RELATING TO THESE TERMS OF USE MUST BE COMMENCED WITHIN ONE (1) YEAR AFTER THE CAUSE OF ACTION ACCRUES OTHERWISE SUCH CAUSE OF ACTION OR CLAIM IS PERMANENTLY BARRED.
### Governing Law and Jurisdiction
You represent and warrant that you possess the legal right and ability to enter into these Terms of Use and to use the Site in accordance with these Terms of Use. You agree that your use of the Site and these Terms of Use (excluding the arbitration provision) shall be governed by all applicable federal laws and the laws of the Commonwealth of Massachusetts, without giving effect to any principles of conflict of law. You agree to submit to the sole and exclusive jurisdiction of the state and federal courts sitting in Boston, Massachusetts.
### Contact Us
If you have any questions about these Terms of Use, please contact us by mail at Monogram LLC, 200 Clarendon Street, 20th Floor, Boston, Massachusetts 02116.
---
### [Monogram Privacy Information Request](https://www.abestudentloans.com/monogram-privacy-information-request/)
**Published:** April 8, 2024
**Author:** abelending
**Content:**
Monogram - Consumer Privacy Act Information request [](https://www.monogramllc.com)

# Monogram Privacy Information Request
Under state privacy laws, you have the right to request the personal information that we have collected about you in the course of providing services to you. Please complete the required fields to submit your request. Upon successful identity verification, you will receive your report via email.
\* Required Field
First Name*
Required Field.
Last Name*
Other First Name
Other Last Name
Date Of Birth*
/
/
(E.g., 02/31/1980)
U.S. Social Security Number*
-
-
(E.g., 123-45-6789)
Email Address*
Confirm Email Address*
REQUIRED PRIVACY COMMUNICATIONS You must open and read the Privacy Policy before you check the box acknowledging receipt and also confirm your identity in order to submit this request.
I have read the [ Privacy Policy](javascript:openPrivacyNoticePdf() and understand the categories and sources of personal information collected, the business purposes for collecting that information, and the categories of third parties with which the information is shared.
Under penalty of perjury, I hereby confirm that I am the consumer whose information I am requesting. I authorize Monogram to validate my identity and to disclose the categories and specific pieces of personal information collected which Monogram maintains.
[](#) © Monogram | 200 Clarendon Street 20th Floor, Boston, MA 02116
[Legal notice](https://www.monogramllc.com/legal-notice.php) | [Privacy Policy](https://www.monogramllc.com/privacy-policy.php) | [Monogram Privacy Information Request](dataprivacy.jsf)
---
### [Consent to Electronic Communications and Signatures](https://www.abestudentloans.com/consent-to-electronic-communications-and-signatures/)
**Published:** April 8, 2024
**Author:** abelending
**Content:**

# Consent to Electronic Communications and Signatures
DR Bank (“Lender”) is required by law to provide you certain information in writing. We will provide that information directly or through loan origination and servicing agents, including Monogram LLC. We may provide this information to you electronically, instead of in a paper copy, with your prior consent. We also need your consent to use electronic signatures. Described below are the terms and conditions for us to provide you with electronic communications and use electronic signatures. Please read this Consent carefully.
### In this Consent:
- “We,” “us,” “our” and “Lender” means DR Bank, its loan origination or servicing agents, including Monogram LLC, any subsequent assignees or holders of your loan and any subsidiaries and affiliates of any of the
- “You” and “your” means the person giving this consent, and also any co‐signer, authorized signer, or authorized representative.
- “Electronic Communications” means each disclosure, notice, agreement, fee schedule, statement, record, document, and other information we provide to you, or that you sign or submit or agree to at our request, including any notices or disclosures required by applicable law or regulation, sent by us to you electronically.
- The words “include” and “including,” when used at the beginning of a list of one or more items, indicate that the list contains examples – the list is not exclusive or exhaustive, and the items in the list are only illustrative. They are not the only possible items that could appear in the list.
### 1. Consent to Electronic Communications
By entering the code at the end of this Consent on our website, you specifically agree to receive and/or obtain Electronic Communications. This includes Electronic Communications related to your account from Lender or third party servicers. You specifically consent to receive electronic mail (email) and online communications and disclosures regarding your loan instead of receiving them by regular U.S. mail. Except as noted below or otherwise at our discretion communications will not be furnished on paper. Your consent will apply to all information we send to you, or disclose or communicate to you online, relating to your loan, including notices regarding your application and your credit agreement, and any disclosures that are required by law to be in writing, including, without limitation, Truth In Lending Act disclosures and tax forms. We may deliver a disclosure or notice to you by posting it to your online account, including adverse action notices in the event your application is declined, and may, at our discretion, chose to send you an email notification of the posting as a courtesy. Your consent remains in effect until you give us notice that you are withdrawing it.
### 2. Paper Version of Electronic Communications
You may request a paper version of an Electronic Communication. You acknowledge that we reserve the right to charge you a reasonable fee for the production and mailing of paper versions of Electronic Communications, unless charging a fee is prohibited by applicable law. To request a paper copy of an Electronic Communication, please call us at 1‐855‐444‐4645. Please note that a request for a paper version of one or more Electronic Communications will not by itself constitute a withdrawal of consent to receive Electronic Communications.
### 3. Revocation of Consent to Electronic Communications
You have the right to withdraw your consent to receive Electronic Communications at any time by calling us at 1‐855‐444‐4645. Your withdrawal of consent will become effective after we have had a reasonable opportunity to act upon it. Please note that withdrawing your consent to receive Electronic Communications may slow the speed at which we can complete certain steps in the loan application process.
### 4. Valid and Current Email Address, Notification and Updates
You agree to promptly notify us of any change in your telephone number, mailing address, or email address. You may modify your telephone number, mailing address, or email address by calling us at 1‐ 855‐444‐4645.
### 5. Electronic Signature Consent and Agreement
By entering the code at the end of this Consent on our website, you acknowledge that you have read, understand and agree to the following:
- You are voluntarily choosing to sign your loan documents, including your credit agreement, electronically;
- You understand that the documents we present electronically will replace the use of paper documents;
- You understand and agree that your electronic signature will bind you to the terms and conditions to the same extent as if you signed your loan documents on paper with an ink signature;
- You understand and agree that no certification authority or other third party verification is necessary to validate your electronic signature and that the lack of such certification or third party verification will not in any way affect the enforceability of your electronic signature or any resulting contract between you and us; and
- You understand that you have the right to withhold your consent to the use of electronic signatures, and that you have the right to withdraw your consent at any time prior to completing the e‐sign process.
### 6. Hardware, Software and Operating System Requirements
You must be able to view, print, and retain information presented on‐screen in order to receive Electronic Communications. By entering the code at the end of this Consent on our website, you confirm that you are able to view Hyper Text Markup Language (HTML) files and read Adobe PDF files, and that you are able to print and save HTML and Adobe PDF files. If you are not able to do this, please make sure that you have Adobe Acrobat Reader installed on your computer. It can be downloaded for free at .
You also confirm that you have access to a Current Version of an Internet browser that we support: Google Chrome, Microsoft Internet Explorer, Microsoft Edge, Mozilla Firefox and Safari. “Current Version” means a version of the software that is currently being supported by its publisher.
### 7. Changes to Hardware and Software Requirements
If our hardware or software requirements change, and that change would create a material risk that you would not be able to access or retain your Electronic Communications, we will give you notice of the revised hardware or software requirements.
### 8. By Accepting This Consent and Entering the Code Below On Our Website, You Confirm That:
- You have the necessary hardware and software described above;
- You can access and read this Consent to Electronic Communications and Signatures;
- You have an active email account;
- You can print this disclosure on paper, or save the disclosure to a place where you can print it, for future reference and access;
- You consent to use and sign electronically an electronic version of any loan documents; and
- You agree to the terms and conditions of this Consent
### Use This Access Code to Consent to Electronic Communications:
It is recommended that you print or save a copy of this Consent for future reference.
---
### [Monogram Privacy Policy](https://www.abestudentloans.com/monogram-privacy-policy/)
**Published:** April 8, 2024
**Author:** abelending
**Content:**

# Monogram Privacy Policy
### 1. General
Monogram LLC and its subsidiaries, U.S.-based entities, (together, “Monogram”, “our”, “we, or “us”) understands that confidentiality of information is important to you. We have created this privacy policy (this “Privacy Policy”) to demonstrate our commitment to keeping your information confidential. This Privacy Policy describes our information collection and sharing practices and is effective as of August 15, 2023.
### 2. Collecting Information
This section describes the categories of information we collect and how we use that information. We collect the following categories of information (collectively, “Information”):
#### **a. Loan Application Information**
Our website may be used to initiate and complete loan applications. We will collect information provided by you that is required by lender partners to process each application (collectively, “Loan Application Information”). We will use Loan Application Information to evaluate, process, and underwrite the application on behalf of our lender partners. We will also retain and use Loan Application Information, including to establish and administer loan accounts, for fraud protection, and to satisfy certain regulatory requirements.
Except where prohibited by law, we may use the email, physical address, and phone number provided in the Loan Application Information to deliver marketing communications to you via email or direct mail or to contact you for information about your experience with our website, products, and services. When we send marketing communications via email, we provide unsubscribe options within our emails so that you can opt-out of receiving future marketing communications via email. Even if you opt-out of receiving marketing communications by email, we may still use the email address to send transactional information related to an application or a loan. You may opt-out of receiving marketing or user-experience related phone calls by contacting us at the address provided in Section 10 of this Privacy Policy.
We may use or provide to third parties certain Loan Application Information for analysis purposes. For example, we may use such Loan Application Information to analyze the effectiveness of loan solicitations or underwriting. Loan Application Information used or shared in this manner will not contain your personally identifiable information.
We may provide to third parties certain Loan Application Information for product or service offerings. For example, we may use such Loan Application Information to identify pertinent financial products and share the Information with existing and future lender partners with whom we have contractual arrangements to offer such products. In all cases, our collection, use and disclosure of Loan Application Information will be in accordance with this Privacy Policy, and the requirements of applicable law.
#### **b. Cookie and Tracking Information**
We use internet address information (“Cookie Information”) to help diagnose problems with our servers, to track user traffic patterns, and to administer our website. We make use of a standard feature of browser software called a “cookie” to assign you a unique, random number. A “cookie” is a small file that identifies your computer as a unique user when you visit a website. When you visit the site again, the cookie allows that site to recognize your browser. Most browsers are initially set up to accept cookies. You can set or amend your browser controls to accept or refuse cookies or to indicate when a cookie is being sent. If you choose to reject cookies, you may still use our website though your access to some functionality and areas of our website may be restricted.
Our website uses cookies to recognize you as a user of our website, to direct you to our home page or to other pages on our website, and to help keep track of what you do on the website. A cookie cannot read data off of your computer’s hard drive. We track user activity on our website, such as automatically collecting the date and time of your access to our services. However, we do not respond to web browser “do not track” signals or similar mechanisms, so when you use our website, third parties may collect personally identifiable information about your online activities.
Technologies are used to remember settings, preferences and usage similar to browser cookies but these are managed through a different interface than the one provided by your web browser. These technologies create locally stored objects (LSOs). Depending on the settings of your computer or mobile device (“Device”), we may also collect Device make, model, screen resolution, plug-in information, language preference, browser type and language; country and timezone in which the Device is located; and metadata stored on the Device. This information is collected through cookies and/or LSOs.
We may use a software technology called clear gifs (a.k.a. Web Beacons/Web Bugs) for some website and email interactions. This technology is used to inform us of what content is effective so we can better manage and target our marketing content. Clear gifs are tiny graphics with a unique identifier, similar in function to cookies, and are used to track the online movements of web users. In contrast to cookies, which are stored on a user’s computer hard drive, clear gifs are embedded invisibly on web pages or in emails and are about the size of the period at the end of this sentence. We use clear gifs or pixels in our HTML-based emails to let us know which emails have been opened by recipients. This allows us to gauge the effectiveness of certain communications and the effectiveness of our marketing campaigns. We tie the information gathered by clear gifs in emails to User Supplied Information (see Section 2.d. below) profiles.
#### **c. Survey Information**
After receiving a submitted loan application, we may ask you to complete a survey. You are not required to complete the survey. We use the information provided in survey responses to improve our products and services.
#### **d. User Supplied Information**
You may be asked to supply contact information in order to receive information or materials that you request, to request being added to an e-mail list, or to participate in a contest or sweepstakes. We will collect information from you including name, email address, phone number, and education information (collectively, “User Supplied Information”).
Except where prohibited by law, we may use the email address provided to deliver marketing communications to you or to communicate information, tools, products and service offerings, including loan products funded by our lender partners. When we send marketing communications via email, we provide unsubscribe options within our emails so that you can opt-out of receiving future marketing communications via email.
We may provide to third parties certain User Supplied Information for product or service offerings or marketing purposes. For example, we may use such User Supplied Information to identify pertinent financial products and share the information with lenders, schools or service providers offering such products. In all cases, our collection, use and disclosure of User Supplied Information will be in accordance with this Privacy Policy, and the requirements of applicable law.
### 3. Sharing Information
This section describes how we share the Information we collect. The following are the ways we disclose or share Information:
**a. Access to Information by Employees.** Monogram and employees of Monogram have access to Information. Monogram policy requires each employee to agree to keep all Information confidential.
**b. Sharing Loan Application Information with Lender Partners.** We will share Loan Application Information with our lender partners with whom we have contractual arrangements. If a lender directs us to do so, we may also share Loan Application Information and related Information with other service providers who support the lender’s loan programs, such as loan servicing companies, collection agencies and credit bureau agencies. Lenders maintain independent privacy programs and are contractually required to safeguard all Information. You should also review your lender’s privacy policy or notice for more information about that lender’s specific information sharing practices.
**c. Access to Information by Service Providers.** We may share Information with service providers with whom we have contracted to perform services on our behalf or on behalf of our lender partners, such as companies that help process and service loans, and, where permitted by law, companies that market products and services. We may use third-party service providers to store Information and facilitate communication with you. All contracted third-party service providers are contractually required to safeguard all Information.
**d. Sharing Aggregated Information.** We may share aggregated Information that is not identified with any particular individual with our business partners and our affiliates.
**e. Sharing Loan Application Information With Cosigners.** If two applicants apply for a loan together as student borrower and cosigner, each applicant will have access to the other’s Loan Application Information.
**f. Sharing Information with Schools.** We may share Loan Application Information and related Information with your school for the purposes of processing a loan application and administering the loan account.
**g. Sharing User Supplied Information with Non-Affiliates.** . We may share User Supplied Information with non-affiliated entities including lenders, schools or service providers that offer financial products.
**h. Sharing Information with Other Parties.** We will not share any Information about you with any third party, other than as provided in this Privacy Policy unless Monogram is required (or has the good faith belief that it is required) to share Information in order to (i) comply with applicable law, (ii) in response to valid requests by public authorities, including for national security, law enforcement, or regulatory requirements, (iii) respond to any legal process served on Monogram or any applicable lender, or (iv) to protect the rights or property of Monogram or any lender. We do not sell Information.
**i. Limiting Information Sharing.** You may limit the sharing of certain information in accordance with your lender’s Privacy Notice.
### 4. Collecting Information About Children
Monogram neither intends to collect, nor knowingly collects, any information from or about children. It is possible that a minor child impersonating a parent or other adult may provide the child’s name, address, phone number, fax number, email address and/or social security number in an attempt to submit a loan application. Monogram cannot always determine if a visitor to our websites or the sender of an e-mail is a minor child.
### 5. Accessing and Updating Information
We do not currently provide the ability to update information online. You may contact us by mail, as provided in Section 10 of this Privacy Policy to update Loan Application Information.
### 6. Links to Other Websites
This website contains links to other websites. By clicking on such links, you will leave this website and enter the other websites. The privacy practices of such linked websites are not covered by this Privacy Policy, and Monogram is not responsible for the privacy practices, data collection, security or content of other websites. You should be careful to review any privacy policies posted on linked websites before using them.
### 7. Security
All Information gathered on this website is encrypted during transmission stored within secure databases and protected by firewalls and other security features. As effective as current encryption technology is, however, no security system is impenetrable. We cannot guarantee the security of our databases, nor can we guarantee that Information which you supply will not be intercepted while being transmitted to us over the Internet.
### 8. Changes to Privacy Policy
We may change our policies (including this Privacy Policy) at any time. If we decide to change this Privacy Policy, we will post the changes to this page so that you may be aware of our actions. Any change to this Privacy Policy will become effective when posted here.
### 9. Contacting Monogram
For additional information about Monogram, this website or this Privacy Policy, please contact us by mail at Monogram Customer Service, 200 Clarendon Street, 20th Floor, Boston, Massachusetts 02116.
---
## Categories
### [Uncategorized](https://www.abestudentloans.com/category/uncategorized/)
---
### [Press Release](https://www.abestudentloans.com/category/press-release/)
---
### [Review](https://www.abestudentloans.com/category/review/)
---
### [Scholarships](https://www.abestudentloans.com/category/blog/scholarships/)
---
### [Federal Loans](https://www.abestudentloans.com/category/blog/federal-loans/)
---
### [Blog](https://www.abestudentloans.com/category/blog/)
---
### [News](https://www.abestudentloans.com/category/news/)
---